In brief · summary: El Paso
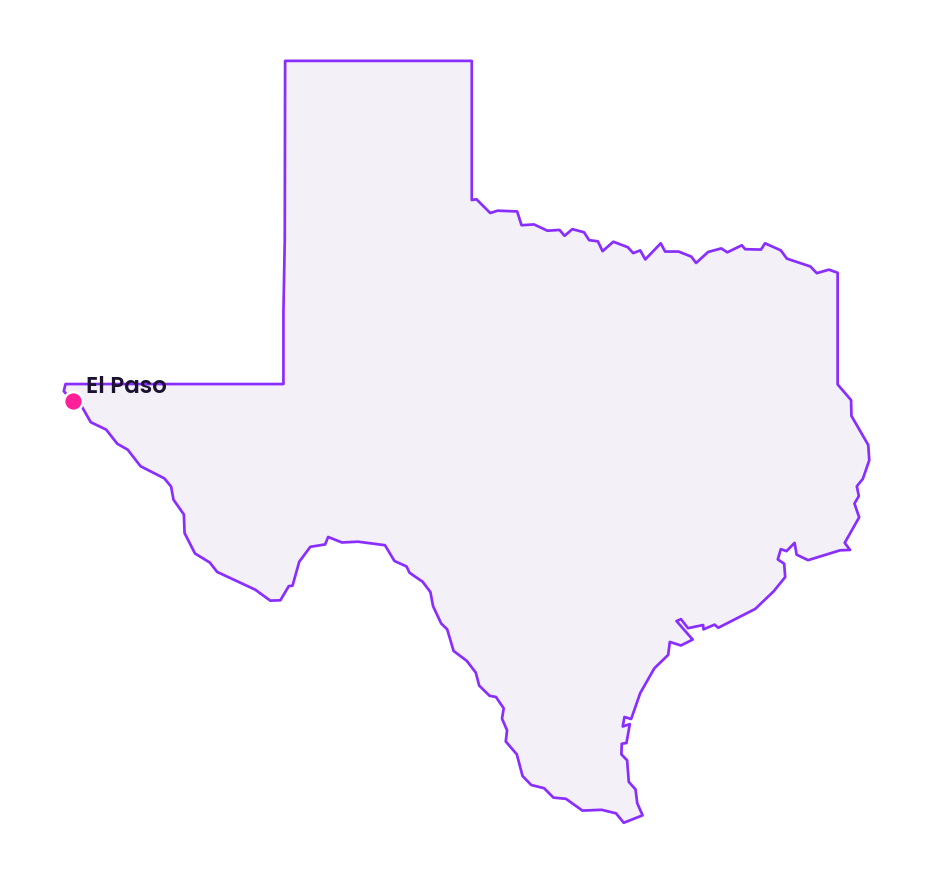
El Paso sits at the far western tip of Texas, forming a single binational metropolis with Ciudad Juárez across the Rio Grande and functioning as one of the most important manufacturing and logistics gateways on the United States and Mexico border. The city held about 681,723 residents as of the Census Bureau estimate for July 1, 2024, inside a metropolitan area of roughly 879,392 people.
The defining economic features are the Fort Bliss military installation, which stabilizes the economy across cycles, and a booming industrial and logistics sector driven by nearshoring and cross border manufacturing. The metro unemployment rate measured 4.9% in June 2026, and total nonfarm employment stood near 366,364.
The asset class picture is led decisively by industrial. Cross border demand and nearshoring have produced record absorption, with the market posting about 1.6 million square feet of net absorption in the second quarter of 2026 even as heavy speculative construction kept vacancy in the double digits near 11.3% and asking rents near $8.25 per square foot on a net basis. Multifamily is tight and late in its supply cycle, with average effective rent near $1,082 per month, occupancy near 94.1%, and a construction pipeline that has collapsed to just 136 units, which points to firm occupancy ahead. Single …
Section 01Executive Summary
El Paso sits at the far western tip of Texas, forming a single binational metropolis with Ciudad Juárez across the Rio Grande and functioning as one of the most important manufacturing and logistics gateways on the United States and Mexico border. The city held about 681,723 residents as of the Census Bureau estimate for July 1, 2024, inside a metropolitan area of roughly 879,392 people. The defining economic features are the Fort Bliss military installation, which stabilizes the economy across cycles, and a booming industrial and logistics sector driven by nearshoring and cross border manufacturing. The metro unemployment rate measured 4.9% in June 2026, and total nonfarm employment stood near 366,364.
The asset class picture is led decisively by industrial. Cross border demand and nearshoring have produced record absorption, with the market posting about 1.6 million square feet of net absorption in the second quarter of 2026 even as heavy speculative construction kept vacancy in the double digits near 11.3% and asking rents near $8.25 per square foot on a net basis. Multifamily is tight and late in its supply cycle, with average effective rent near $1,082 per month, occupancy near 94.1%, and a construction pipeline that has collapsed to just 136 units, which points to firm occupancy ahead. Single family housing is affordable, with the county median sale price near $275,000. Office is the weak sector, with vacancy elevated near 18%. The market's principal cautions are low household incomes with a poverty rate near 19.6%, exceptionally high Texas property taxes near a 2.03% effective rate, desert water scarcity, and sensitivity to trade and tariff policy given the cross border economy. El Paso reads as a defensive, affordable, industrially driven border market with a stabilizing military anchor and a genuine nearshoring tailwind, tempered by trade policy risk and a flat core city population.
Section 02Population and Migration
El Paso's population is essentially flat at the city level and modestly growing at the metro level, a pattern that has held for more than a decade. The city recorded about 681,723 residents as of the Census Bureau Population Estimates Program vintage for July 1, 2024, up from its April 2020 base of 678,959 and up about 0.4% from the 2023 estimate, leaving the core city population essentially flat over the period. The following table shows the recent trajectory and the metro anchor.
| Metric | Value | Source basis |
|---|---|---|
| City population, 2024 | 681,723 | Census PEP vintage 2024 |
| City population, 2020 base | 678,959 | Census PEP vintage 2024 |
| City change, 2023 to 2024 | +2,765 (+0.4%) | Census PEP vintage 2024 |
| Metro area population, 2024 | 879,392 | Census PEP vintage 2024 |
The metro area, which is essentially coextensive with El Paso County, grew modestly, on the order of 0.1 to 0.2 percent per year since 2020 according to Census and HUD analysis of the data. The demographic profile is young, with a city median age near 34.5 years, and heavily Hispanic, reflecting the deep cross border ties with Ciudad Juárez. The investor takeaway is that El Paso is not a population growth story in the mold of Austin or Dallas, and the flat core city population is a genuine caution for long term demand. Rental and housing demand here is underpinned less by in migration than by the military presence, natural increase, and the binational economy, which makes economic drivers rather than headcount growth the key to underwriting.
Section 03Jobs and Economic Anchors
El Paso's labor market is anchored by the military, health care, education, and cross border manufacturing and logistics. Total nonfarm employment in the metro measured about 366,364 in June 2026 on a seasonally adjusted basis, per the Dallas Federal Reserve series carried through FRED, and the metro unemployment rate was 4.9% in June 2026, not seasonally adjusted, per the Bureau of Labor Statistics. That unemployment reading is moderate, and the market's employment has been more stable than higher beta metros because of its large public and military base.
The single most important anchor is Fort Bliss, the largest employer in the metropolitan area, with about 47,628 total employees according to HUD analysis, including roughly 28,800 active duty military personnel who are not counted in nonfarm payrolls. This installation provides a durable, countercyclical employment and housing demand base that most private economies lack. Health care and social assistance is the largest civilian sector, employing about 48,830 people per American Community Survey data, anchored by hospital systems and a growing medical presence. Education, including the El Paso Independent School District and the University of Texas at El Paso, and retail trade round out the base, while the manufacturing and logistics economy is tightly integrated with the maquiladora factories of Ciudad Juárez, where components and finished goods flow across the border in both directions. The investor conclusion is that El Paso offers unusual employment stability for a market of its size, thanks to Fort Bliss and the public sector, combined with a cross border manufacturing engine that is currently benefiting from nearshoring, though that same cross border exposure introduces trade policy sensitivity that a purely domestic economy would not carry.
Section 04Income
Household incomes in El Paso are low by national and Texas standards, which is the market's most important demand side constraint and also the foundation of its affordability. The following table compares the city with state and national benchmarks.
| Geography | Median household income | Per capita income | Poverty rate |
|---|---|---|---|
| El Paso city | $52,338 | $24,978 | 19.6% |
| Texas | $75,780 | about $39,775 | about 14% |
| United States | $77,719 | about $43,000 | 12.5% |
The El Paso city figures are the Census QuickFacts American Community Survey 2019 to 2023 estimates, and the state and national figures provide context. The city median household income of $52,338 is about 33% below the national median, per capita income near $24,978 is roughly 42% below the national figure, and the poverty rate near 19.6% runs about 7 percentage points above the national rate. These figures have direct investment implications. Low incomes cap the rent and price levels the local market can support, which is why average apartment rents sit near $1,082 and home prices remain affordable, and they mean that workforce and moderate rate housing, not luxury product, is the natural target. The elevated poverty rate calls for disciplined tenant screening and professional management, and it makes El Paso a market where affordability is the core value proposition and where rent growth is inherently constrained by the local wage base rather than by supply alone.
Section 05Housing and Multifamily
The multifamily market is tight, stable, and firmly in the late stage of its supply cycle, which is a favorable position for existing owners. According to MMG Real Estate Advisors, the El Paso average effective rent was about $1,082 per month in the first quarter of 2026, up 2.2% over the year, with all submarkets posting positive rent growth, and stabilized occupancy stood at 94.1%, a 20 basis point improvement over the year. Net absorption over the trailing four quarters was about 686 units, outpacing the roughly 665 units delivered. RentCafe, drawing on Yardi Matrix data, placed the average apartment rent near $1,131 as of August 2026, up about 2.72% over the year, and Yardi Matrix tracks roughly 57,080 apartment units across 378 properties in the market. The following table summarizes the apartment picture.
| Metric (El Paso multifamily) | Value | Period | Source |
|---|---|---|---|
| Average effective rent | $1,082 | Q1 2026 | MMG |
| Annual rent change | +2.2% | Q1 2026 | MMG |
| Stabilized occupancy | 94.1% | Q1 2026 | MMG |
| Net absorption, trailing 4 quarters | +686 units | Q1 2026 | MMG |
| Units under construction | 136 | Q1 2026 | MMG |
The standout figure is the construction pipeline, which contracted about 83% over four quarters to just 136 units, equal to roughly 0.3% of inventory, with zero trailing twelve month starts. This is an exceptionally supply constrained setup that positions El Paso to hold high occupancy and steady rent growth with almost no near term delivery pressure, a sharp contrast to oversupplied Sun Belt markets. MMG Real Estate Advisors' 2026 forecast for the El Paso multifamily market calls for effective rent growth near 1.0% and occupancy near 94.2% as deliveries step down about 77%. The investor conclusion is that El Paso multifamily is a defensive, high occupancy income asset with limited supply risk, well suited to buyers seeking durable cash flow, with the caveat that low local incomes cap the ceiling on rent growth.
Section 06Rents
Apartment rents in El Paso are among the most affordable in Texas, reflecting the market's low wage base, and they are growing at a measured pace. The average effective rent near $1,082 per month in the first quarter of 2026, or near $1,131 in the RentCafe reading, sits well below the Texas major metros and the national average. Rent growth of about 2.2% over the year is modest but positive across every submarket, and forecasts point to continued low single digit growth as the supply pipeline empties.
The key underwriting insight is that El Paso rent growth is constrained more by local incomes than by supply. With a median household income near $52,338 and a poverty rate near 19.6%, the market cannot sustain the aggressive rent escalations seen in higher income metros, so pro forma assumptions in the range of 1% to 3% annual growth are defensible while anything higher is not. The offsetting strength is stability, because the same affordability that caps growth also insulates the market from the sharp rent declines that oversupplied luxury markets have experienced. The collapse in new deliveries should support firm occupancy and give owners the pricing discipline to push rents at the pace local wages allow. For an income investor, El Paso offers reliable, if unspectacular, rent performance with low downside volatility.
Section 07Vacancy
Vacancy conditions vary by property type but are broadly healthy outside of office. Multifamily occupancy near 94.1%, implying vacancy near 5.9%, is tight and supported by the empty construction pipeline. Industrial vacancy is elevated in the double digits, near 11.3% in first quarter 2026 tracking, but this reflects a deliberate wave of speculative construction meeting record demand rather than weak fundamentals, and vacancy has been declining as new space leases up. Office is the soft sector, with vacancy elevated near 18% in recent tracking, down from higher levels but still the weakest of the major property types.
The single family for sale market shows no vacancy problem but rather affordability driven demand, with the county median sale price rising about 3.8% over the year. The investor conclusion is that El Paso vacancy is favorable across residential and improving in industrial, where the double digit reading should not be read as distress given the record absorption, while office carries genuine structural softness. Capital should follow the tight residential and strengthening industrial sectors and treat office selectively.
Section 08Supply Pipeline
Supply dynamics differ dramatically by sector, and this divergence is central to the El Paso investment case. In multifamily, the pipeline has essentially emptied, with just 136 units under construction and no trailing starts, which is the most supply constrained major property type in the market and the strongest forward indicator for apartment owners. In single family, homebuilding continues at a measured pace consistent with the market's affordability, without the oversupply seen in some faster growing metros.
Industrial is the opposite story, with an aggressive and continuing construction pipeline driven by nearshoring demand. CBRE reported about 6.6 million square feet under construction across 20 projects as of the second quarter of 2026, with more than 1.9 million square feet of new starts in the quarter and deliveries of about 1.5 million square feet, and Colliers documented more than 2 million square feet of deliveries in the second half of 2025 across the combined El Paso and Santa Teresa market. This heavy speculative development is the direct cause of elevated industrial vacancy, and it means industrial investors must underwrite lease up risk carefully even as demand runs at record levels. The investor conclusion is that El Paso pairs an extremely tight residential supply outlook, which favors apartment and single family owners, with a robust industrial pipeline that requires careful timing and basis discipline to acquire well as new buildings absorb.
Section 09Single Family Homes
The single family market is affordable and steadily appreciating, supported by the market's low price base and constrained resale inventory. Redfin reported the El Paso County median sale price near $275,000 in early 2026, up about 3.8% over the year, with a median price per square foot near $162, up about 2.5% over the year. The Redfin city of El Paso figure runs lower, near $256,949 for the three months ending June 2026, up about 1.4% over the year, so the county figure is used here as the broader market reference. The following table summarizes the housing indicators.
| Indicator | Value | Scope | Source |
|---|---|---|---|
| Median sale price | $275,000 | county, early 2026 | Redfin |
| Median price per square foot | $162 | county, early 2026 | Redfin |
| Annual price change | +3.8% | county, early 2026 | Redfin |
| Price per square foot change | +2.5% | county, early 2026 | Redfin |
| Median sale price | $256,949 | city, 3 months to June 2026 | Redfin |
The single family rental angle is compelling on affordability. With a county median sale price near $275,000, apartment rents near $1,082, and a low local income base, El Paso homes remain attainable and rental demand is deep among households not positioned to buy. The market's affordability and steady appreciation make it well suited to single family rental and build to rent operators seeking durable, moderate cost inventory, and the constrained resale supply supports continued price stability. The investor conclusion is that El Paso single family is a value and yield play anchored by affordability and military demand, best approached as a long hold, with the important caveat that Texas property taxes near a 2.03% effective rate materially raise the carrying cost and must be modeled explicitly against the rental yield.
Section 10Commercial Real Estate and Retail Centers
Commercial fundamentals are dominated by the strength of industrial, which is the defining commercial story of the El Paso and Santa Teresa border market. The following table summarizes industrial and office using the most recent firm brokerage readings.
| Asset class | Vacancy | Asking rent | Period and source |
|---|---|---|---|
| Industrial | 11.3% | $8.25 NNN | Q1 2026 Cushman |
| Office | about 18% | see note | Q2 2026 Colliers |
Industrial is exceptionally active. The market posted about 1.6 million square feet of net absorption in the second quarter of 2026, a record high, and vacancy declined by 30 basis points over the quarter and 100 basis points over the year even as large blocks of new speculative space delivered, per CBRE. Cushman and Wakefield placed first quarter 2026 industrial vacancy near 11.3% with net asking rent near $8.25 per square foot, the elevated vacancy reflecting the deliberate speculative build out to capture nearshoring and cross border logistics demand from the Ciudad Juárez maquiladora complex. This is the sector where El Paso most clearly outperforms, and the combination of record absorption and rising rents underpins strong investor interest despite the double digit headline vacancy. Office is the weak sector, with vacancy elevated near 18% in recent tracking, down from higher levels but still soft, and it should be approached selectively. The investor conclusion is to favor industrial and logistics, where the nearshoring tailwind and record absorption are strongest, to pursue grocery anchored retail selectively given tight necessity demand, and to treat office cautiously.
Section 11Transactions and Capital Markets
Transaction activity in El Paso reflects both the national repricing under higher interest rates and the market's distinctive border industrial appeal. Multifamily lending remained available, with quoted rates on larger El Paso apartment loans near 5.63% in mid 2026 according to one commercial lender, and regional cap rate aggregators placed El Paso multifamily cap rates for higher quality product in the low 5% range with value add acquisitions nearer 6.86%, though a single authoritative published El Paso multifamily transaction cap rate series is not available, so these are framed as reference points from lender and aggregator data rather than a precise market print. Industrial has drawn strong institutional and cross border investor interest given the sector's record absorption and rent growth, and pricing has firmed accordingly.
The capital markets conclusion for an accredited investor is that El Paso sits in the same national price discovery period as other markets, with a wider bid ask gap and thinner volume than the peak years, but with a differentiated demand driver in cross border industrial that supports pricing in that sector. Multifamily benefits from the empty supply pipeline and high occupancy, which supports stable valuations, while the high property tax burden and the low income ceiling on rents are the two factors that most constrain achievable pricing. Patient capital can find wider going in yields here than in primary coastal markets, particularly in industrial and workforce multifamily, provided the tax load and trade policy exposure are underwritten explicitly.
Section 12Taxes
Texas imposes no state income tax, and it funds local government substantially through property taxes, which in El Paso are notably high and a central underwriting consideration. Property is assessed at 100% of market value, and the El Paso County effective property tax rate is about 2.03%, producing a median annual property tax bill near $3,660, well above the national average. This high rate reflects the combined levies of the county, the city, the school districts, the community college, the hospital district, and other special districts, all stacked on the full market value of the property.
Several structural features moderate the burden for certain owners. Texas caps the annual growth in the taxable value of a homestead at 10% under state law, which limits increases for owner occupants but does not apply to investment property, and homestead and over sixty five exemptions reduce bills for qualifying owners. For an investor, the key point is that the roughly 2% effective rate is a heavy and non trivial drag on net operating income and on single family rental yields, materially higher than the property tax load in many other states, and it must be modeled at full market value with the expectation that investment property does not benefit from the homestead cap. The offsetting advantage is the absence of any state income tax, which benefits the after tax return on Texas real estate income. The practical conclusion is to underwrite El Paso deals with the full local tax stack applied to market value and to treat the high property tax as one of the defining features of the market's economics.
Section 13Insurance
Property insurance in El Paso is a moderate cost input, lower than in the coastal and hail prone parts of Texas but subject to the general firming of the Texas insurance market. Because El Paso sits in a high desert far from the Gulf Coast, it faces no hurricane risk and lower hail and severe convective storm exposure than Dallas, Houston, or the Texas plains, which works in the market's favor on premiums. No official public figure specific to the El Paso market is published at the city level for average homeowners or commercial property premiums, so a precise local number is not stated here.
The principal insurable perils in El Paso are flash flooding in the desert arroyos during intense monsoon season rainfall, extreme heat, and to a lesser degree wind and dust events, rather than the catastrophe perils that drive coastal pricing. The most important insurance related diligence item is flood exposure, because FEMA issued revised preliminary flood maps for El Paso County in 2025 that update the mapped flood hazard areas, and desert flash flooding can affect properties in and near arroyos even where rainfall is generally low. The investor conclusion is that insurance is a manageable and relatively stable line item in El Paso relative to coastal Texas, with flash flood zone verification against the current and revised FEMA maps being the essential property specific step before closing.
Section 14Landlord Tenant and Regulatory Environment
Texas is one of the most landlord favorable states in the country, and El Paso operates entirely under that state framework with no additional local rent regulation. There is no rent control anywhere in Texas, because Local Government Code section 214.902 preempts municipalities from enacting rent caps except under a governor approved disaster housing emergency that no city has invoked, so owners may set and raise rents freely with proper notice. There is no statutory cap on security deposit amounts, and while most landlords charge one to two months of rent, the law imposes no limit. A landlord must refund the deposit, or provide a written itemized statement of deductions, within 30 days after the tenant surrenders the premises under Texas Property Code section 92.103, with the clock triggered once the tenant provides a written forwarding address, and bad faith retention exposes the landlord to $100 plus three times the wrongfully withheld amount plus attorney fees.
Eviction in Texas is among the fastest in the nation. A landlord must give at least a three day written notice to vacate before filing a forcible detainer action under Property Code section 24.005, and the lease may shorten that period, after which an uncontested eviction can proceed to a writ of possession in as little as roughly 21 days. Texas is not a just cause state, so a landlord may decline to renew without stating a reason. The investor conclusion is that the regulatory environment is highly favorable to owners, with no rent control, no deposit cap, and a fast eviction process, which reduces operational risk and carrying costs relative to tenant protective states, while the strict 30 day deposit return rule and the bad faith penalty require disciplined move out procedures.
Section 15Infrastructure
El Paso's infrastructure is built around its role as a major border crossing and logistics hub, which is the foundation of its industrial economy. The metro is served by multiple international ports of entry connecting it to Ciudad Juárez, including the Bridge of the Americas, the Ysleta and Zaragoza crossing, and the downtown Paso del Norte and Santa Fe bridges, which together handle enormous volumes of commercial truck traffic and cross border commerce. Interstate 10 runs through the metro as the primary east west corridor, connecting El Paso to the broader Texas and Arizona markets, and Union Pacific and BNSF rail lines plus the El Paso International Airport round out the freight network. The adjacent Santa Teresa industrial area, just across the state line in New Mexico, functions as part of the same logistics market and has attracted major distribution and manufacturing investment.
Fort Bliss adds a vast military installation with its own infrastructure and a large, stable payroll. For an investor, the infrastructure picture directly underwrites the strength of the industrial and logistics sector, because the border crossings and the integration with the Ciudad Juárez manufacturing base give El Paso a structural advantage in cross border trade and nearshoring that inland markets cannot replicate. The principal long term infrastructure constraint is water, which is addressed in the climate section, but on transportation and logistics the region is exceptionally well positioned.
Section 16Climate and Physical Risks
El Paso's physical risk profile is distinctive, dominated by heat, drought, and flash flooding rather than the storm perils of most of Texas, with water scarcity as the defining long term concern. The Federal Emergency Management Agency National Risk Index rates El Paso County as Relatively High, driven substantially by flood, heat, and social vulnerability rather than by hurricane or tornado exposure. The following table summarizes the principal hazards.
| Hazard | Assessment | Source |
|---|---|---|
| Flash flooding (desert arroyos) | Primary local hazard; FEMA issued revised preliminary maps in 2025 | FEMA |
| Extreme heat and drought | High and rising; central to the water scarcity risk | FEMA NRI, NOAA |
| Earthquake | Low to moderate | FEMA NRI |
| Composite FEMA National Risk Index | Relatively High | FEMA NRI |
The most important nuance for investors is water. El Paso is a high desert city dependent on the Rio Grande and on groundwater aquifers, and long term water availability is the single most significant physical constraint on the region's growth, a factor that prudent long horizon investors should weigh even though it does not affect near term operations. Flash flooding during the summer monsoon can affect properties in and near arroyos despite the generally arid climate, which is why the 2025 FEMA map revisions matter for property level diligence. Extreme heat is intensifying and raises cooling costs and infrastructure stress. The investor conclusion is that El Paso faces no coastal catastrophe risk and low storm exposure, which is favorable for insurance, but that flash flood verification and a clear eyed view of long term water scarcity are the essential physical risk considerations in this market.
Section 17Neighborhoods and Submarkets
The metro spans a range of submarkets from the dense urban core near the border to the growing suburbs of the east and northwest. The West Side, including the areas along North Mesa and near the University of Texas at El Paso, is among the higher income and higher value residential areas. The East Side and the far East Side, including the Horizon City area, have been the primary directions of residential and retail growth, driven by newer single family construction and their proximity to Fort Bliss. The Northeast is closely tied to Fort Bliss and its military housing demand. The Lower Valley and the areas near the central business district and the border crossings carry the older, denser, and lower income housing stock, and downtown has seen uneven redevelopment. Across the state line, the Santa Teresa area in New Mexico anchors the industrial and logistics submarket alongside the East El Paso and airport industrial corridors.
For rental strategy, the East Side and Northeast submarkets offer the deepest workforce and military renter demand and the strongest recent growth, while the West Side supports somewhat higher price product. Industrial opportunity is concentrated in the Santa Teresa, airport, and East corridors near the ports of entry and Interstate 10. Grocery anchored and necessity retail demand is broadly distributed across the growing suburban trade areas. The investor conclusion is to match product to submarket, targeting workforce multifamily and single family rental in the East and Northeast near Fort Bliss and the growth corridors, industrial near the border crossings and Santa Teresa, and necessity retail across the expanding suburbs.
Section 18Opportunities
The clearest opportunity is cross border industrial and logistics, where nearshoring and the integration with the Ciudad Juárez manufacturing base have produced record absorption near 1.6 million square feet in a single quarter and rising rents near $8.25 per square foot, with the caveat that the heavy speculative pipeline requires careful timing and basis discipline to acquire well as new buildings lease up. The second opportunity is workforce multifamily acquired into an essentially empty construction pipeline, where just 136 units under construction and occupancy near 94.1% point toward firm occupancy and steady rent growth with minimal supply risk, an unusually favorable setup relative to oversupplied Sun Belt markets.
Single family rental and build to rent capitalize on El Paso's affordability, with a county median sale price near $275,000 and deep demand from military and workforce households, provided the high property tax load is modeled against the yield. Grocery anchored and necessity retail benefits from tight demand and the dense border population. The unifying opportunity thesis is that El Paso offers a differentiated nearshoring industrial tailwind, an extremely supply constrained residential market, genuine affordability, a stabilizing military anchor, and no coastal catastrophe risk, a combination attractive to investors who can underwrite the trade policy exposure and the high tax and low income constraints.
Section 19Risks
The primary risk is trade and tariff policy. El Paso's industrial boom and much of its broader economy depend on cross border manufacturing and logistics with Ciudad Juárez, so changes in United States trade policy, tariffs, or border friction could sharply alter the nearshoring tailwind that currently drives the market, and this policy sensitivity is a genuine and specific risk that domestic focused markets do not carry. The second risk is the low income base, with a city median household income near $52,338 and a poverty rate near 19.6%, which caps achievable rents and prices and demands careful tenant screening and management.
Additional risks include the high Texas property tax burden near a 2.03% effective rate applied to full market value, which materially reduces net operating income and single family rental yields, the flat core city population that constrains long term demand growth, and the elevated industrial vacancy near 11.3% that reflects a large speculative pipeline requiring successful lease up. Longer term, desert water scarcity is a structural constraint on the region's growth that prudent investors should weigh. Extreme heat and flash flood exposure are manageable but real physical risks. Data measurement risk is also present, as El Paso specific figures for office, retail, and multifamily cap rates are thinner than in larger markets and vary by provider. None of these risks is disqualifying, but the trade policy exposure and the high property tax load in particular should be explicitly stress tested rather than assumed away.
Section 20Investor Implications
For an accredited investor weighing El Paso against a South Florida baseline, the trade is a lower income, lower growth market with a differentiated nearshoring industrial engine and much lower insurance and catastrophe risk, set against a higher property tax burden and trade policy exposure. El Paso's apartment supply pipeline is far tighter than South Florida's, its property insurance is a moderate and stable line item rather than the valuation impairing cost that has repriced dramatically in the Florida market, and Texas provides no state income tax and a highly landlord favorable legal regime with no rent control and fast evictions. What El Paso gives up is the population and income growth of a high migration coastal market, and it carries the specific cross border trade sensitivity and the roughly 2% property tax load that South Florida does not.
The practical positioning is income first and affordability focused, with conservative low single digit rent growth assumptions reflecting the local wage ceiling, explicit modeling of the high property tax at full market value, careful stress testing of trade and tariff exposure for industrial, and flash flood verification against the revised FEMA maps. Cross border industrial and logistics is the sector with the strongest tailwind and the highest conviction for investors who can underwrite the policy risk and the speculative pipeline, workforce multifamily offers defensive income with minimal supply risk, and single family rental capitalizes on affordability and military demand. The empty apartment pipeline and the stabilizing Fort Bliss anchor make this a market where downside is contained, while the nearshoring dynamic offers upside contingent on trade policy remaining supportive.
Section 21Conclusion
El Paso is an affordable, industrially driven border market with a stabilizing military anchor and a genuine nearshoring tailwind, well suited to defensive, income oriented investors who can underwrite its specific risks. Its multifamily market is tight and late in the supply cycle, with occupancy near 94.1% and an essentially empty construction pipeline that supports firm occupancy ahead. Its industrial sector is booming on cross border and nearshoring demand, with record absorption and rising rents, tempered by a heavy speculative pipeline. Single family housing is affordable and steadily appreciating, the regulatory environment is among the most landlord favorable in the country, and physical risk is dominated by manageable heat and flash flood exposure rather than coastal catastrophe. The clear cautions are low household incomes and elevated poverty, a high Texas property tax burden near a 2.03% effective rate, a flat core city population, long term desert water scarcity, and a real sensitivity to trade and tariff policy given the binational economy.
The market will not deliver rapid growth, and its cross border exposure and tax load must be underwritten carefully. But for capital seeking a differentiated nearshoring industrial tailwind, an exceptionally supply constrained residential market, genuine affordability, and low insurance and catastrophe risk, El Paso presents a defensible and distinctive case at the present point in the cycle. As always, this analysis frames the opportunity and the risks so that decision makers can weigh them; it does not render a verdict, and every figure herein should be independently verified against the cited sources before any capital is committed.