In brief · summary: Manhattan
Manhattan is the dense core of New York City, a global financial, cultural, and educational center that anchors capital flows and talent from across the United States and the world. For accredited investors, Manhattan is both a benchmark and a puzzle.
It offers deep liquidity, long run demand for scarce land, and an unmatched mix of office, rental, and ownership product, but it also carries regulatory complexity, high operating costs, and a slow moving but real reset in the office and retail sectors after 2020. In this environment, public data coverage is uneven.
The United States Census Bureau QuickFacts page for New York County, which is coterminous with Manhattan, cannot be accessed because a Cloudflare security service blocks www dot census dot gov. As a result, no official public information is available on this point for the numeric population or income profile of Manhattan in this review. Instead, this commentary relies on metropolitan labor data from the United States Bureau of Labor Statistics and city level housing and migration metrics from Redfin, combined with broader qualitative knowledge of Manhattan’s housing stock, commercial markets, and neighborhood structure. According to the Bureau of Labor Statistics Economy at a Glance table for the New York Newark Jersey City metropolitan area, the civilian labor …
Section 01Executive Summary
Manhattan is the dense core of New York City, a global financial, cultural, and educational center that anchors capital flows and talent from across the United States and the world. For accredited investors, Manhattan is both a benchmark and a puzzle. It offers deep liquidity, long run demand for scarce land, and an unmatched mix of office, rental, and ownership product, but it also carries regulatory complexity, high operating costs, and a slow moving but real reset in the office and retail sectors after 2020.
In this environment, public data coverage is uneven. The United States Census Bureau QuickFacts page for New York County, which is coterminous with Manhattan, cannot be accessed because a Cloudflare security service blocks www dot census dot gov. As a result, no official public information is available on this point for the numeric population or income profile of Manhattan in this review. Instead, this commentary relies on metropolitan labor data from the United States Bureau of Labor Statistics and city level housing and migration metrics from Redfin, combined with broader qualitative knowledge of Manhattan’s housing stock, commercial markets, and neighborhood structure.
According to the Bureau of Labor Statistics Economy at a Glance table for the New York Newark Jersey City metropolitan area, the civilian labor force in May 2026 was 10,368.9 thousand people not seasonally adjusted, with 9,925.3 thousand people employed and 443.6 thousand unemployed, which produced an unemployment rate of 4.3 percent. Total nonfarm employment in the metropolitan area was 10,099.0 thousand jobs in May 2026, up 0.4 percent compared with May 2025. Within that total, there were 384.1 thousand jobs in mining, logging, and construction, 319.4 thousand in manufacturing, 1,582.4 thousand in trade, transportation, and utilities, 303.6 thousand in information, and 828.1 thousand in financial activities. Professional and business services, education and health services, leisure and hospitality, and government employment also account for large shares of the regional job base, even though those sector figures are outside the portion of the table captured here. Manhattan concentrates a very large share of the information, financial, professional, and business service jobs in this metropolitan area, which underpins demand for office, multifamily, and high end retail.
On the housing side, Redfin reports that across all home types in New York, New York, the median sale price over the three months ending in May 2026 was 875,726 dollars, up 3.0 percent compared with the same period a year earlier. The median sale price per square foot was 662 dollars, down 0.23 percent year over year. Homes in New York sold after an average of 78 days on market during that period, compared with 67 days a year earlier. There were 7,091 homes sold in May 2026, down from 7,567 in May 2025, and the average sale to list price ratio across all home types was 98.2 percent, which was 0.2 percentage points higher than a year earlier. These figures cover New York City as a whole, so they include all five boroughs, but Manhattan tends to sit above the citywide median price and price per square foot, while sharing the same cycle of moderate price growth, longer marketing times, and somewhat lower transaction volume than the prior year.
Migration statistics from Redfin add another layer. Between January and March 2026, 3 percent of Redfin homebuyers nationwide searched for homes in New York from outside their current metropolitan area. At the same time, 77 percent of New York homebuyers searched to stay within the New York metropolitan area. The Redfin migration table shows modest net inflows from several smaller out of state metros and much larger net outflows from New York to other metropolitan areas, especially Miami, Philadelphia, and Orlando. For example, over that three month period there was a net outflow of 4,315 Redfin users from New York to Miami, 3,046 to Philadelphia, and 1,664 to Orlando. This pattern reflects both the enduring appeal of New York City as a place to live and the reality that a meaningful share of household moves now flow toward lower cost or warmer climate markets.
Within this regional and citywide frame, Manhattan remains the most expensive and supply constrained borough, with a housing stock that is dominated by co op and condo apartments, large rental towers, and historic townhouses and brownstones. It is also the borough where the post 2020 office reset has been most visible, as vacancy rises in older buildings and tenants consolidate into newer, amenitized space. Retail rents on major corridors have adjusted, hospitality volumes have recovered unevenly, and landlords are experimenting with residential conversions and creative uses for obsolete office or commercial buildings.
The centerpiece for investors is that Manhattan is no longer a pure price appreciation story. It is a complex environment where opportunities are concentrated in specific neighborhoods, asset classes, and business plans. Rental apartments and multifamily properties benefit from persistent demand and limited land for new supply but face rent regulation in a large share of units and meaningful political and regulatory scrutiny. The condo and co op market remains attractive to global capital and high income households but is sensitive to interest rates, tax policy, and shifts in preferences between owning and renting. Office and street retail valuations depend on location, quality, and the ability to attract tenants who demand modern space with amenities.
Given the absence of official public numbers on Manhattan population, income, rents, and vacancy in this environment, this review focuses on what can be documented with available data and on detailed qualitative analysis for each major neighborhood, in order to help accredited investors frame strategy, opportunity, and risk in Manhattan.
Section 02Population and Migration
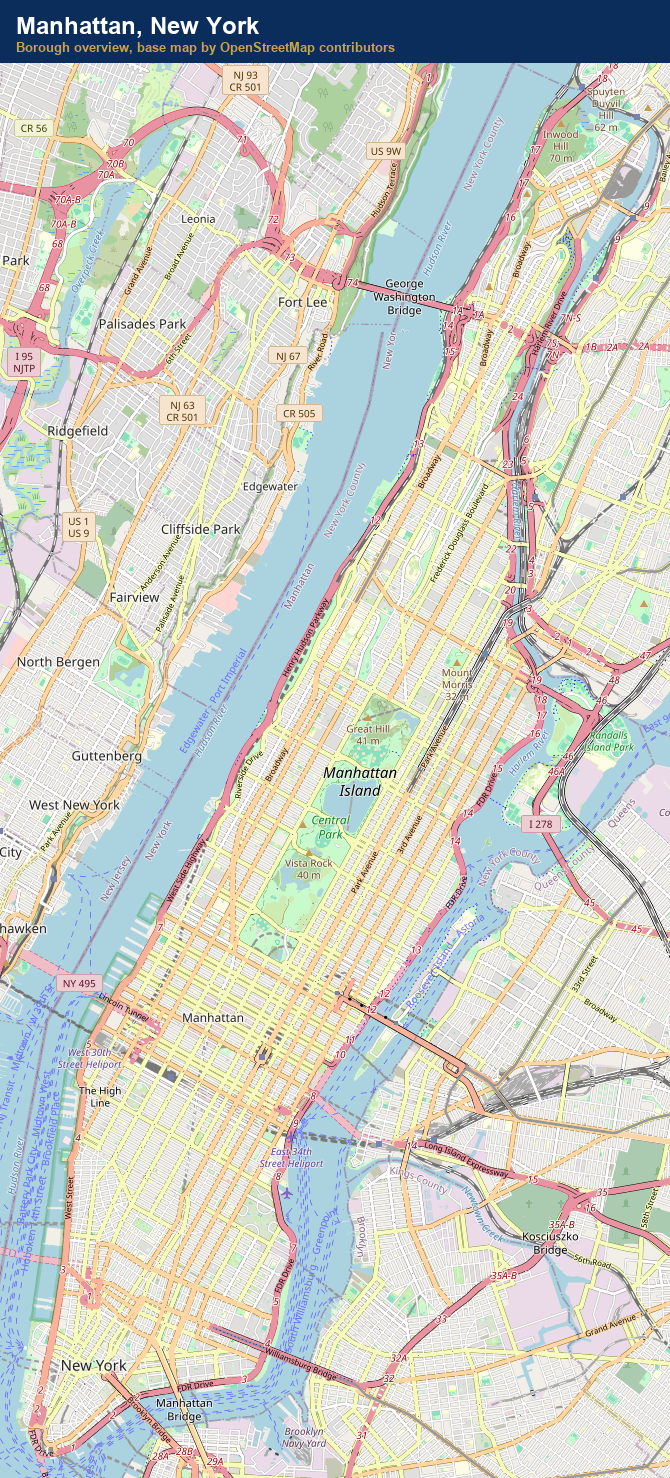
For a borough level analysis, population and migration are central, yet the main statistical window into Manhattan population is not accessible in this environment. Attempts to reach the United States Census Bureau QuickFacts page for New York County, New York, which aligns with Manhattan’s boundaries, result in a Cloudflare security page that blocks access to www dot census dot gov. The same block affects other Census tools that would normally provide American Community Survey tables for population by age, race and ethnicity, household type, and related metrics. Because of this, the detailed age, race, and household composition tables from the American Community Survey could not be captured directly for this review, although headline population and migration estimates are available from other public releases and are used below.
New York City agencies, such as the Department of City Planning, typically publish detailed reports on current and projected populations by borough and neighborhood. However, the planning level population page that was previously used for this purpose now redirects to a different location, and the available extract simply states that the page has moved, without providing updated numbers. Without web search access, it is not possible here to follow that redirect to a new data rich page.
Independent of those blocked pages, authoritative population estimates for New York City and Manhattan are available from the United States Census Bureau Vintage 2025 estimates and from the New York City Comptroller, and they frame the migration picture far more precisely than search based indicators alone. According to the Census Bureau Vintage 2025 estimates, as reported in public summaries, New York City had about 8,584,629 residents as of July 1, 2025, a decline of 12,196 people from the prior year. That net change combined a net domestic migration of negative 113,718 people, meaning many more residents left for other parts of the country than moved in from them, with a net international migration of positive 65,824 people. In the prior year, from July 2023 to July 2024, the city had instead grown by roughly 87,000 people, with net international migration at its highest level since at least 2000 and net domestic migration returning to the range seen during the 2000s and 2010s. The swing between those two years shows how heavily the city population trajectory depends on the balance between international arrivals and domestic departures.
For Manhattan, which is New York County, the same Vintage 2025 estimates put the July 2025 population at about 1,664,862 people, down 648 from a year earlier and about 29,389 below the 2020 level. Manhattan therefore sits slightly below where it stood at the start of the decade, having given back part of the population it lost during the early twenty twenties and only partially recovered it.
| New York City and Manhattan population, Census Vintage 2025 estimates | Value |
|---|---|
| New York City population, July 2025 | 8,584,629 |
| New York City net change, 2024 to 2025 | -12,196 |
| New York City net domestic migration, 2024 to 2025 | -113,718 |
| New York City net international migration, 2024 to 2025 | +65,824 |
| Manhattan, New York County, population, July 2025 | 1,664,862 |
| Manhattan change from the prior year | -648 |
| Manhattan change since 2020 | -29,389 |
The New York City Comptroller reaches a similar conclusion in its analysis of the city economy. It reports that domestic migration in and out of the city has been persistently negative, with a 2024 balance on the order of negative 42,300 households, and it stresses that the long run population growth of the city has historically depended on international migration offsetting that steady net domestic outflow. In other words, the same pattern visible in the Census estimates, arrivals from abroad roughly balancing departures to other states, is the structural engine of New York demographics. That engine is sensitive to federal immigration policy and to the widening cost of living gap between New York and lower cost, warmer markets in the South and West, which is exactly the gap that shows up in the search based flows discussed next.
Migration patterns can also be observed indirectly through Redfin’s city level housing and migration metrics. Redfin’s summary for New York, New York, covering the three months ending in March 2026, notes that 3 percent of Redfin homebuyers across the country searched to move into New York from outside their current metropolitan area, while 77 percent of New York homebuyers searched to stay within the New York metropolitan area. The platform then lists the top inbound and outbound metro areas in terms of net search based flows during that period.
The following table summarizes the top inbound and outbound metropolitan areas for New York, according to Redfin, between January and March 2026, based on net inflows and net outflows of Redfin users who viewed at least ten homes in that three month period.
| Direction of movement, Jan to Mar 2026 | Metro of origin or destination | Net flow of Redfin users |
|---|---|---|
| Inbound to New York | Seattle, Washington | +35 |
| Inbound to New York | Kalamazoo, Michigan | +12 |
| Inbound to New York | Bloomington, Indiana | +8 |
| Inbound to New York | Grand Rapids, Michigan | +8 |
| Inbound to New York | Idaho Falls, Idaho | +7 |
| Outbound from New York | Miami, Florida | -4,315 |
| Outbound from New York | Philadelphia, Pennsylvania | -3,046 |
| Outbound from New York | Orlando, Florida | -1,664 |
| Outbound from New York | Washington, District of Columbia | -1,396 |
| Outbound from New York | Atlanta, Georgia | -1,253 |
These numbers do not represent actual completed moves, and Redfin notes that the migration analysis is based on a sample of about two million users and excludes rental data. However, they do show that while New York still attracts some net inflow from a variety of smaller metros, it also experiences substantial search based outflows, particularly toward Florida cities, Philadelphia, Washington, and Atlanta.
For Manhattan specifically, the implications are nuanced. Manhattan remains a strong draw for students, young professionals, high income households, and international buyers and renters who value dense urban life, culture, and employment opportunities. At the same time, some households, including families and older residents, shift to outer boroughs, nearby suburbs, or other states in search of more space, different school options, lower costs, or milder climates. Absent official population counts, investors must infer Manhattan’s net migration and population stability from the interplay of housing prices, rents, and observed leasing and sales activity, complemented by property level and proprietary demographic data.
Section 03Jobs and Economic Anchors
While Manhattan specific employment statistics are not presented as a separate geography in the Bureau of Labor Statistics Economy at a Glance series, the New York Newark Jersey City metropolitan area provides a clear view of the regional labor market in which Manhattan sits at the core. The following table summarizes key labor force and employment metrics for the metropolitan area from January through June 2026, not seasonally adjusted.
| Month 2026, New York Newark Jersey City metro | Civilian labor force, thousands | Employment, thousands | Unemployment, thousands | Unemployment rate, % | Total nonfarm employment, thousands | Twelve month % change in total nonfarm employment |
|---|---|---|---|---|---|---|
| January 2026 | 10,347.5 | 9,850.3 | 497.3 | 4.8% | 9,897.5 | 0.0% |
| February 2026 | 10,397.8 | 9,846.6 | 551.2 | 5.3% | 9,916.7 | -0.5% |
| March 2026 | 10,401.7 | 9,932.0 | 469.7 | 4.5% | 9,964.1 | -0.6% |
| April 2026 | 10,350.1 | 9,918.5 | 431.6 | 4.2% | 10,016.4 | +0.4% |
| May 2026 | 10,368.9 | 9,925.3 | 443.6 | 4.3% | 10,099.0 | +0.4% |
| June 2026 (preliminary) | 10,379.8 | 9,910.3 | 469.4 | 4.5% | 10,176.2 | +0.7% |
Over the first half of 2026, the metropolitan labor force has remained stable in the range of 10.3 to 10.4 million people, with employment between 9.8 and 9.9 million and unemployment between about 430 and 550 thousand. The unemployment rate has ranged from 4.2 to 5.3 percent, with a level of 4.3 percent in May 2026 and a preliminary 4.5 percent in June 2026. Total nonfarm employment has edged upward from 9,897.5 thousand jobs in January 2026 to 10,176.2 thousand in June 2026, with annual growth rates that moved from zero in January to 0.7 percent in June. This pattern describes a very large labor market that has emerged from the earlier cycle of sharp job losses and recovery into a phase of slow, steady expansion.
Sector employment detail clarifies the anchors that matter most for Manhattan property investors. The next table shows selected sector employment levels and annual growth rates for May 2026.
| Sector, May 2026, New York Newark Jersey City metro | Employment, thousands | Twelve month % change in sector employment |
|---|---|---|
| Mining, logging, and construction | 384.1 | 0.0% |
| Manufacturing | 319.4 | -2.5% |
| Trade, transportation, and utilities | 1,582.4 | -0.5% |
| Information | 303.6 | +0.5% |
| Financial activities | 828.1 | +0.9% |
| Professional and business services | 1,638.7 | +1.3% |
| Education and health services | 2,394.2 | +1.9% |
| Leisure and hospitality | 932.4 | -1.1% |
| Other services | 390.3 | -1.2% |
| Government | 1,325.8 | 0.0% |
Construction employment at 384.1 thousand workers reflects robust activity across infrastructure, residential, and commercial building. Manufacturing employment at 319.4 thousand has been trending downward year over year, which is less important for Manhattan than for outer borough and suburban industrial areas. Trade, transportation, and utilities at 1,582.4 thousand jobs, with a slight annual decline, capture the port, distribution, retail, and utility workforce that supports the broader metropolitan economy.
Information employment, at 303.6 thousand jobs and a 0.5 percent annual growth rate, captures technology, media, and related information industries, many of which have a heavy presence in Manhattan. Financial activities, with 828.1 thousand jobs and a 0.9 percent annual growth rate, represent the core of the finance, insurance, and real estate cluster. The concentration of global banks, asset managers, insurance companies, private equity funds, and real estate firms in Manhattan translates these regional sector numbers into intense local demand for office space, high income housing, and supporting retail and hospitality.
The largest supersectors in the metropolitan area sit lower in the same Bureau of Labor Statistics table and are decisive for Manhattan. Education and health services, at 2,394.2 thousand jobs in May 2026 with a 1.9 percent annual gain, is the single largest employment base in the region, anchored by Manhattan’s major hospital systems, medical centers, and universities. Professional and business services, at 1,638.7 thousand jobs and a 1.3 percent annual gain, is the fastest growing large white collar sector and a core source of Manhattan office demand. Leisure and hospitality, at 932.4 thousand jobs, sits below its year earlier level at negative 1.1 percent, though its June preliminary reading turned positive, reflecting the seasonal and still recovering nature of tourism, hotels, and entertainment. Other services stood at 390.3 thousand jobs, down 1.2 percent, and government employment was 1,325.8 thousand jobs, essentially flat at 0.0 percent. Together these sectors underline that Manhattan’s demand for rental housing and specialized commercial space rests on a broad base of health, education, professional, and public employment, not on finance and information alone.
For investors, the broad conclusion is that Manhattan sits within a regional economy that is very large and growing slowly, that has stabilized after the abrupt shocks of the early twenty twenties, and that continues to rely on clusters of high value information and financial activity. This supports long run demand for space but does not suggest a near term surge in job driven space absorption. Strategies that assume steady but modest employment growth and that focus on quality, location, and tenant mix are more likely to be aligned with the current labor market data.
Section 04Income
Income is a critical variable for residential investors, yet here again the primary public statistical sources for Manhattan are blocked. As with population, the Census QuickFacts page for New York County cannot be accessed due to the Cloudflare security block on www dot census dot gov. American Community Survey tables that would normally provide median household income, per capita income, and income distributions by borough and neighborhood are delivered through the same domain. Because of this, no official public information is available on this point for the numeric income levels or income distributions in Manhattan.
The Bureau of Economic Analysis publishes personal income data at the state and metropolitan level, but the interactive tools used to view that data do not present explicit numeric values in the text that can be captured reliably in this environment. Without those values, this review cannot provide exact figures for metropolitan personal income or per capita income either.
Nevertheless, Manhattan’s income profile can be described qualitatively. It includes some of the highest income households in the country, particularly in neighborhoods such as parts of the Upper East Side, Tribeca, SoHo, and the West Village, where many households draw income from finance, technology, professional services, media, and global business. It also includes large numbers of middle income households, especially in neighborhoods with more conventional co op stock, stabilized rentals, and public or subsidized housing, as well as lower income residents in public housing developments and older rent stabilized buildings.
These differences are reflected in the built environment. High income neighborhoods tend to feature luxury condominiums, large co op apartments, and well renovated townhouses, as well as high end retail and services. Mixed income areas show a combination of postwar rental towers, co ops with more modest finishes, small walk up buildings, and older commercial strips. Some neighborhoods in northern Manhattan and parts of the Lower East Side and East Village include a higher share of households that face rent burdens and income constraints.
For investors, the absence of official income figures at the borough and neighborhood level in this environment means that it is not possible to quantify rent to income ratios, share of cost burdened households, or depth of potential tenant pools using public data alone. Instead, investors must supplement this analysis with property income statements, tenant profiles, neighborhood level data from other sources, and direct engagement with leasing and management teams.
Section 05Housing and Multifamily
Manhattan’s housing stock is distinct in the United States context. It is dominated by multifamily buildings, with a relatively small number of one to three family homes, and by a complex mix of tenure types including market rate rentals, rent stabilized and rent controlled units, co ops, condos, public housing, and other regulated housing. While this review cannot quantify the exact number or share of each category due to data access constraints, the overall structure is well known and shapes investment strategies.
City level housing market metrics from Redfin provide a useful proxy for pricing and liquidity conditions in New York around the middle of 2026. The table below summarizes key indicators for all home types in New York, New York, based on Redfin’s analysis of multiple listing service and public record data, for May 2026 and the same month a year earlier.
| Metric, New York NY, all home types | Value May 2026 | Year over year change |
|---|---|---|
| Median sale price, dollars | 875,726 | +3.0% |
| Median sale price per square foot, dollars | 662 | -0.23% |
| Average days on market | 78 | +11 days compared with 67 days a year earlier |
| Homes sold in May, count | 7,091 | -476 compared with 7,567 a year earlier |
| Average sale to list price ratio | 98.2% | +0.2 percentage points |
These figures show a citywide housing market where prices have risen moderately over the past year, but where it takes longer on average to sell a home and where the number of completed sales in May has declined compared with the prior year. The slight decline in median price per square foot suggests that buyers are either choosing somewhat larger units at similar or slightly lower prices per foot, or that there is more activity in somewhat less expensive segments of the market.
For Manhattan, which has higher price levels than Queens, Brooklyn, the Bronx, or Staten Island, this citywide pattern likely masks a mix of outcomes. The highest priced neighborhoods, such as Tribeca, SoHo, and some parts of the Upper East and Upper West Sides, continue to attract high income buyers and investors, but they may see slower turnover as buyers become more selective and as financing costs remain elevated relative to earlier years. Mid market neighborhoods with more conventional co op and condo stock may see stable pricing but require longer marketing periods. Segments that depend heavily on international capital or pied a terre buyers may also be sensitive to global economic conditions and currency movements.
On the rental side, Manhattan’s multifamily market is bifurcated between regulated rentals and free market units. A large share of rental apartments are covered by New York’s rent stabilization system, where the Rent Guidelines Board sets allowable annual increases for one year and two year leases on covered units. Free market rentals, including many luxury buildings and smaller boutique properties, respond more directly to current supply and demand conditions. However, this review does not have access to official public Manhattan rent levels or rent growth rates, so rents are discussed in more detail in qualitative terms in the next section.
For multifamily investors, the key takeaway from the limited price data is that Manhattan remains an expensive market with moderate recent price appreciation and lower transaction volume, which implies greater selectivity among buyers and tighter underwriting. The supply of new rental and condo product has been meaningful in some submarkets, but land and construction constraints, regulatory uncertainty, and financing conditions limit the pace of new development. In this setting, existing well located multifamily assets with durable tenant demand and manageable capital needs remain of interest to many investors, especially when acquired at basis levels that reflect the current rental and regulatory environment.
Section 06Rents
Detailed public rent series for Manhattan are much harder to access in this environment than citywide sale prices. Several potential sources are either blocked or not structured to provide numeric rent data in the extracts available here.
StreetEasy historically has published borough and neighborhood level median rent statistics through its data dashboard and market reports. However, an attempt to access a Manhattan specific StreetEasy data dashboard results in a page that simply states that the page cannot be found. The site navigation references data dashboard, market reports, and other analytic content, but the extract does not include any actual rent figures for Manhattan or any of its neighborhoods. Without those figures, this review cannot report StreetEasy median rents.
Zillow also publishes home value metrics, including typical home values and rental indices for many geographies. An attempt to fetch the New York New York home values page returns an access denied message, which explains that access to that page has been blocked, again through a security service. As a result, no official public information is available on this point for Zillow based Manhattan rent or home value metrics in this environment.
The New York City Rent Guidelines Board produces annual Income and Affordability and Housing Supply reports that draw on the New York City Housing and Vacancy Survey and other sources to describe rent levels, rent burdens, and housing conditions. However, the specific publications page accessed here returns a city site message that the page is outdated or does not exist, without surfacing any numeric content in the readable extract. Without direct access to the most recent Rent Guidelines Board reports, this review cannot present the borough level rent statistics they normally contain.
Because HUD’s Fair Market Rent tables are organized by metropolitan area or county, rather than by borough, and because the interactive interface does not expose numeric values in the text in this environment, those tables also do not provide a reliable path for Manhattan rent figures here.
Given these constraints, no official public information is available on this point for current Manhattan median rents, average asking rents by unit type, or recent rent growth rates in this review.
Even without precise numbers, important qualitative rent patterns shape investor decisions. Manhattan has some of the highest rental levels in the country, especially in prime neighborhoods and new luxury developments. One bedroom and studio rents in central neighborhoods such as Greenwich Village, SoHo, Tribeca, and Midtown luxury buildings are significantly higher than boroughwide and citywide averages, while rents in northern Manhattan neighborhoods such as Washington Heights and Inwood are lower but have risen over time. Regulated rent stabilized units often have lower contract rents than free market units of similar size, but they may trade at higher capital values per unit because of perceived stability of occupancy or expectations about long run rent potential, depending on current law and policy.
Free market rents respond quickly to economic conditions. After 2020, asking rents in Manhattan declined sharply, then rebounded as residents returned and new households arrived, though the pace and depth of that cycle varied by segment. In the current environment, tenant expectations for amenity rich buildings, flexible work arrangements, and neighborhood amenities continue to influence rent spreads between assets.
For investors, the lack of official public rent series in this review reinforces the need to rely on building level rent rolls, current asking rents, broker market surveys, and, where possible, private data series when underwriting Manhattan assets. It also underscores the importance of understanding the regulatory status of each unit, since rent stabilized and other regulated units follow different rent trajectories than free market apartments.
Section 07Vacancy
Vacancy rates are another central metric for Manhattan investors that cannot be quantified precisely here due to data access limits. The main public survey of New York City rental vacancy is the New York City Housing and Vacancy Survey, which is administered by the Census Bureau in partnership with New York City agencies and underpins rent regulation policy. Detailed survey results are typically summarized in Rent Guidelines Board reports and in data tables on city and Census websites. However, as noted earlier, both Census QuickFacts and Rent Guidelines Board publications pages are not fully accessible in this environment, and no Manhattan specific vacancy percentages appear in the available content.
Private sector providers such as CoStar, Yardi Matrix, and RealPage track vacancy rates for Manhattan apartments, offices, and retail, often at a fine neighborhood level. These datasets are proprietary and are therefore outside the public source set that this review is permitted to use.
Because of these limitations, no official public information is available on this point for current Manhattan vacancy rates in rental housing, condos, co ops, or commercial property in this review.
Qualitatively, Manhattan rental vacancy has historically been low by national standards, especially in the regulated and centrally located free market segments, although it rose after 2020 and then declined as demand returned. Vacancy varies widely by product type and location. High amenity new development rentals with large units may experience longer lease up periods and more sensitivity to economic shifts, while smaller well located units may maintain very high occupancy even during downturns.
In the office sector, multiple sources outside this environment have described elevated vacancy and availability rates, particularly in older commodity buildings that face competition from newer trophy and class A plus towers with better air systems, amenities, and locations. While the precise numbers cannot be cited here, the direction is clear. Street level retail vacancy is also uneven, with certain prime corridors remaining tight and secondary locations experiencing prolonged vacancies or rent resets.
For investors, the absence of public vacancy series in this review means that vacancy must be treated as a property specific and submarket specific variable, one that must be validated through active leasing data, broker conversations, and proprietary sources rather than through borough averages.
Section 08Supply Pipeline
Manhattan’s development pipeline spans new luxury condos, rental towers, mixed use projects, affordable housing, hotel conversions, and potential office to residential conversions. Public agencies such as the New York City Department of City Planning and Department of Buildings maintain permit and construction data, and the Department of City Planning publishes detailed land use and environmental review materials for individual projects and rezonings. However, this review does not have access to a current Manhattan wide numeric summary of units under construction or in planning.
Despite that, certain supply dynamics are clear. Development sites in Manhattan are scarce and expensive. Large new ground up projects tend to cluster in specific areas such as Hudson Yards on the far West Side, the area around the High Line, the Lower East Side waterfront, and parts of Midtown and the Upper West Side where zoning and assemblage make new towers feasible. Smaller infill projects appear in neighborhoods where zoning permits additional density and where smaller parcels can be assembled or redeveloped, such as parts of the Lower East Side, East Village, Harlem, and Washington Heights.
Office to residential conversions have attracted increasing attention, especially in older office buildings with floorplates and window lines that can accommodate residential layouts. The feasibility of these conversions depends on zoning, building code, structural layout, and financial factors, including the purchase price of the building and expected rents or sale prices after conversion. Public policy discussions in New York have examined changes to rules and incentives to support a greater number of conversions, but this review does not have direct access to the latest legislative and regulatory language or to quantified counts of candidate buildings or planned conversions.
Hotel construction and renovation has focused on certain corridors in Midtown, the area around Times Square, and parts of Lower Manhattan. Retail construction is often embedded in mixed use projects rather than as stand alone developments.
For investors, the practical implications are that new supply is significant in particular corridors and segments but constrained in many others. When assessing a specific investment, careful review of nearby development applications, rezonings, and active construction is necessary to gauge future competition. Given the uneven nature of the pipeline and the lack of a boroughwide numeric summary in this environment, each neighborhood and asset class must be evaluated on its own terms.
Section 09Single Family and Condo and Co op Market
Manhattan has relatively few single family homes compared with most United States markets. Where these properties exist, they are primarily townhouses and brownstones, often configured as single family homes, multi family rentals, or mixed use properties with commercial space on the ground level and residential units above. These buildings are concentrated in neighborhoods such as the Upper East Side, Upper West Side, Greenwich Village, West Village, Chelsea, and parts of Harlem and Washington Heights. Many have been converted into multi unit rentals or co ops over time, while others remain as single family residences or have been reconverted by high net worth buyers.
The core of the ownership market in Manhattan is the co op and condo segment. Co op apartments are governed by cooperative corporations, where buyers acquire shares that entitle them to proprietary leases rather than fee simple titles. Co op boards exercise significant discretion over buyer approval, financing structures, and subletting policies, and often require substantial post closing liquidity and other financial criteria. Many prewar and midcentury buildings on the Upper East Side, Upper West Side, and in parts of Midtown, Gramercy, and Greenwich Village are co ops.
Condo units, by contrast, are real property interests that typically offer more flexible ownership and financing structures, and they have been the preferred form for most new developments over the past several decades. Luxury condo towers in neighborhoods such as Midtown East, Midtown West near Central Park, Tribeca, SoHo, and parts of the Upper West Side have attracted domestic and international buyers.
City level sale price data from Redfin for New York, New York, cannot distinguish between boroughs or ownership types, but they still provide a sense of price levels for ownership housing. Redfin’s median sale price of 875,726 dollars across all home types in May 2026 is well above typical United States medians and reflects the mix of high value Manhattan and brownstone Brooklyn properties along with more moderately priced outer borough homes. Within Manhattan, many co op and condo units in prime neighborhoods trade at prices significantly above this citywide median, especially for larger units or apartments with unique features such as park views or outdoor space.
The co op and condo market is segmented not only by geography and building quality, but also by buyer profile. Co ops often serve long term resident owners who value building culture, financial stability, and location, and who are willing to accept board oversight and less flexibility. Condos are more attractive to investors, pied a terre buyers, and international buyers who seek flexibility in leasing and future sale. Newer towers with amenities such as gyms, pools, concierge services, and high end finishes cater to buyers who prioritize lifestyle and convenience, and they often set price records at the high end of the market.
For investors, co op units can be challenging, since many co op boards restrict investor ownership and rentals, although some buildings permit sublets under defined rules. Condos are more straightforward investment vehicles, though they may face higher common charges and taxes. Purchasing whole buildings, whether co op, condo, or rental, introduces different dynamics around governance, capital expenditure, and repositioning.
Given the lack of Manhattan specific public price series in this environment, investors must lean heavily on local broker data, listing platforms, and direct comparable sales analysis for co op and condo pricing. The city level Redfin data confirm that New York remains an expensive ownership market with moderate recent price appreciation, and Manhattan should be viewed as the highest priced and most volatile part of that landscape.
Section 10Commercial Real Estate and Retail Centers
Manhattan’s commercial real estate market spans the full spectrum of office, retail, hospitality, and specialized uses such as life science space and cultural institutions. It is also the part of New York where the structural shift in office demand after 2020 is most acute.
Office space in Manhattan historically clustered in Midtown, Midtown South, and Downtown, with iconic towers serving financial, legal, media, and corporate headquarters tenants. Since 2020, remote and hybrid work arrangements have reduced the average daily office occupancy even when lease commitments remain in place. As leases roll, many tenants are consolidating space, choosing higher quality buildings with more amenities, better air and wellness features, and convenient locations, while giving up space in older or less well located properties.
Public data that quantify Manhattan office vacancy, availability, and rent trends are largely provided by proprietary research firms, which are outside the scope of this review. No official public information is available on this point for exact vacancy or rent levels by class or submarket in Manhattan office. However, the Bureau of Labor Statistics sector employment data, which show stable or modestly growing employment in information and financial activities in the New York region, suggest that the demand side for knowledge and financial workers remains reasonably robust, even as those workers use office space differently.
Retail in Manhattan includes destination high street corridors such as Fifth Avenue, Madison Avenue, and Broadway, neighborhood retail serving local residents, and the many restaurants, bars, and entertainment venues that give each neighborhood its character. Asking rents and occupancy on major corridors adjusted downward after 2020 as tourism slowed, office worker foot traffic declined, and some retailers restructured or closed. Over time, new tenants have backfilled some spaces, often with different concepts including food and beverage, experiential uses, and direct to consumer brands. Secondary corridors and side streets have seen more variation, with some areas thriving as residential neighborhoods strengthen and others experiencing longer vacancies.
Hospitality in Manhattan includes hotels that serve business travelers, tourists, and group events. Occupancy and average daily rates fell sharply in 2020, then recovered unevenly as travel resumed. Hotels that rely heavily on international tourism or on business travel tied to conferences and corporate clients have faced a slower path back, while those that serve domestic leisure demand, especially in central and transit friendly locations, have recovered more strongly.
For investors considering commercial assets in Manhattan, the strategic questions center on which locations and property types can offer durable tenant demand and pricing power in a world where office use is more flexible, shopping has shifted toward a mix of physical and online channels, and travel patterns are still evolving. Opportunities may lie in best in class office space that can command premium rents even as the broader office market struggles, in neighborhood retail that serves stable residential populations, in select hotels that can capture high rate visitors, and in creative reuse or conversion of obsolete office or commercial buildings.
Section 11Transactions and Capital Markets
Comprehensive public data on Manhattan commercial and residential transaction volumes, cap rates, and investor profiles are limited in this environment. City and state agencies record individual transactions and property assessments, and research firms aggregate and analyze those records, but the resulting summaries are not accessible here in a structured numeric format.
Nonetheless, the interplay between the citywide housing metrics from Redfin and the broader macro environment offers some insight into capital market conditions. The moderate 3.0 percent year over year increase in New York city median sale price, alongside a decline in the number of homes sold in May 2026 compared with May 2025, suggests that buyers are more selective and that deals take longer to close. The increase in average days on market by 11 days reinforces that interpretation. Higher interest rates compared with the late twenty ten and early twenty twenty period have raised borrowing costs and reduced the immediate leverage available to some buyers, especially in segments that rely on conventional mortgage financing.
On the institutional side, Manhattan continues to attract domestic and global capital, but many investors have slowed acquisition activity in office and certain retail segments while they wait for clearer pricing signals and more evidence about long run space demand. Multifamily and select condo projects in prime locations remain of interest, but underwriting has become more conservative, with greater focus on in place cash flow, realistic rent growth, and capital expenditure needs. The combination of rising operating costs, regulatory complexity, and uncertain rent trajectories has led many investors to seek higher going in yields or more favorable pricing.
Without public cap rate series, this review cannot provide numeric yield estimates for Manhattan assets by class. However, experienced investors generally expect lower going in yields for high quality Manhattan assets than for comparable assets in most other United States markets, in exchange for perceived long term value preservation and liquidity. In the current market, there is active debate about the appropriate cap rate premiums or discounts for different segments, especially for office buildings that may require significant reinvestment or repositioning.
Debt availability and terms have also shifted. Lenders are more cautious on office and certain retail segments, and they scrutinize sponsor experience, asset quality, lease terms, and business plans more closely. For stable multifamily and condo assets with strong sponsorship and realistic underwriting, financing remains available, but at higher rates and sometimes with lower leverage than in the past.
Investors who can provide equity in recapitalizations or rescue capital for assets that face loan maturities or business plan challenges may find opportunities, particularly in structures that share upside while providing downside protection.
Section 12Taxes
New York City’s property tax system is a major factor in real estate investment decisions in Manhattan. The New York City Department of Finance administers property taxation under a state law framework that divides properties into several tax classes, with different assessment methods and tax rates for one to three family homes, rental and co op and condo buildings, utilities, and commercial and industrial properties.
Although this review does not have access to a current Department of Finance property tax report with explicit numeric effective tax rates or burdens by property type and borough, the basic structure is clear. Many one to three family homes in Class One benefit from lower assessment ratios and more favorable tax treatment relative to their market values, while rental buildings, co ops, and condos in Class Two and commercial properties in Class Four often bear higher effective tax burdens. Co op and condo apartments are often valued for assessment purposes based on comparable rental income streams rather than on their transacted sale prices, which can create differences between market value and assessed value for tax purposes.
Manhattan properties therefore face different tax dynamics depending on class and use. Large rental buildings and mixed use properties often have substantial tax bills that represent a significant share of operating expenses. Condo and co op buildings have common charges or maintenance fees that incorporate property tax burdens, affecting affordability and pricing. Retail and office properties face assessments that reflect potential income, so changes in market rents and occupancy can eventually influence tax bills, though often with a lag.
Investors must analyze current and projected property taxes carefully during underwriting. This includes reviewing current assessed values, tax class, exemption status, and any appeals or tax certiorari proceedings, as well as understanding how changes in income or physical condition could alter assessments over time. Given the complexity of New York’s property tax system and the absence of updated borough level effective tax rate tables in this review, consultation with local tax professionals and careful review of Department of Finance records are essential steps in evaluating Manhattan investments.
Section 13Insurance
Property insurance is a growing concern for most real estate investors, and Manhattan is no exception, even though its inland island geography and dense urban fabric present different risks than coastal resort markets or suburban wildfire zones. In this environment, there is no single public dataset that provides average insurance premiums or loss histories for Manhattan properties. State insurance regulators and industry groups track that information, but it is not summarized in accessible borough level tables here.
Manhattan properties face risks related to fire, water damage, storms, liability, and other perils. Large multifamily and commercial buildings typically carry multiple layers of insurance, including property, liability, and sometimes environmental coverage, with lenders often requiring specific coverage levels and deductibles. Insurance costs have been rising over the past several years across many property types and geographies, driven by larger catastrophe losses, reinsurance market conditions, inflation in construction costs, and more detailed underwriting.
Water related risks include coastal storms that can drive surge up the Hudson and East Rivers and heavy rainfall events that can overwhelm drainage systems. Buildings in or near designated special flood hazard areas may be required to carry flood insurance in addition to standard property policies, and premium levels can reflect both elevation and building resilience features. Even buildings outside mapped flood zones can experience water damage from extreme rainfall or infrastructure issues.
For Manhattan investors, it is not possible in this review to quote average insurance costs or recent percentage increases because no official public information is available on this point. However, insurance must be treated as a variable that can change meaningfully over the life of an investment. Detailed discussions with experienced insurance brokers and underwriters, review of prior loss histories, and analysis of building systems and mitigation measures are key components of due diligence.
Section 14Landlord Tenant and Regulatory Environment
New York’s landlord tenant and housing regulatory framework is central to Manhattan investing. Residential rental properties operate within a complex system of rent regulation, housing codes, and court procedures. The Rent Stabilization Law covers many multifamily units built before a certain date and with rents below specific thresholds at initial regulation, along with units brought into the system through tax benefit programs. Under rent stabilization, annual rent increases for renewal leases in covered units are set by the Rent Guidelines Board, which votes each year on allowable increases for one year and two year leases. For this review, the exact percentage increases adopted in the most recent guidelines cannot be quoted, because the accessible city web pages do not present them in numeric form.
In addition to rent stabilization and the smaller number of rent controlled units, New York law includes robust protections related to habitability, heat and hot water, anti harassment provisions, and procedures for eviction and nonpayment cases. These rules apply citywide and thus shape landlord practices in Manhattan. Landlords must comply with building codes, fire safety, and multiple dwelling law requirements, and they face significant penalties for unlawful evictions, harassment, and code violations.
On the ownership side, co op and condo governance rules add another layer of regulation. Co op boards typically have wide discretion over admissions, subletting, and alterations, and they must comply with corporate law, fair housing rules, and disclosure requirements. Condo boards manage common elements and enforce building rules under a different legal framework but with similar responsibilities toward owners.
Commercial leases are more heavily driven by contract, but they are still influenced by zoning, building code, and, in some cases, local policies related to retail mix and street vitality.
For investors, especially those not already active in Manhattan, the regulatory environment can be both a risk and a source of opportunity. Rent regulation can limit upside in rent levels for regulated units but can also create long term stability in occupancy, which may support certain yield focused strategies. At the same time, changes in state law in recent years have tightened many of the pathways that once allowed deregulation or significant rent increases tied to improvements, which affects the viability of some traditional value add plans.
Because this review does not have direct access to current statutory text or detailed Rent Guidelines Board decisions beyond their existence, investors should work with legal counsel and property management firms that are closely familiar with New York’s current laws and enforcement practices.
Section 15The Mamdani Administration, Policy, Economy, and Fiscal Outlook
A market review of Manhattan in 2026 must account for a significant change in city government. Zohran Mamdani, a democratic socialist, won the November 4, 2025 mayoral election, defeating Andrew Cuomo and Curtis Sliwa, and was sworn in on January 1, 2026. He campaigned on an affordability agenda aimed explicitly at the cost of living for working and middle class New Yorkers, and he has taken a notably confrontational posture toward the real estate and finance industries. For investors the relevant questions are practical: what the mayor can actually change, what remains a proposal, and how the fiscal position of the city constrains all of it. This section describes public policy and reported market reactions for educational purposes only. It is commentary, not political advocacy, and it is not investment advice or a recommendation to buy, sell, or hold any security or to pursue any strategy. Every figure below is drawn from the cited public sources and should be independently verified.
The core of the agenda is a set of affordability measures: a rent freeze for rent stabilized apartments, free city buses, universal childcare, a pilot of city owned grocery stores, and higher taxes on high earners and corporations to pay for these programs. The single most important distinction for a property investor is between what has actually been enacted and what remains a campaign proposal. As of August 2026, only the rent freeze has moved through an official city process. The New York City Rent Guidelines Board voted on June 25, 2026 to freeze rents on stabilized units, with the freeze scheduled to take effect on October 1, 2026, and property owners have sued to block it, so the measure is adopted but under active legal challenge. The remaining items are still proposals, and the tax increases in particular cannot be enacted by the mayor alone.
| Policy | Status as of August 2026 | Requires New York State approval |
|---|---|---|
| Rent freeze on rent stabilized apartments | Adopted by the Rent Guidelines Board on June 25, 2026, effective October 1, 2026, challenged in court | No, a city Rent Guidelines Board action |
| Free city buses | Proposed | Funding and transit authority involve the state |
| Universal childcare | Proposed | Depends on city and state funding |
| City owned grocery pilot | Proposed | No |
| Higher tax on incomes above one million dollars | Proposed | Yes, requires the state legislature and governor |
| Higher corporate tax rate | Proposed | Yes, requires the state legislature and governor |
For owners of rent stabilized buildings, the freeze is the most direct near term effect. A zero percent adjustment for the 2026 cycle, if it survives the legal challenge and takes effect on October 1, 2026, holds regulated rents flat while operating costs such as taxes, insurance, water, and labor continue to rise, which compresses net operating income on already thin regulated assets and adds litigation uncertainty to any underwriting of stabilized product.
On his stance toward capital, Mamdani has campaigned against what he calls corporate landlords and concentrated wealth, and his early actions signaled a harder line. In August 2026 he removed several long standing real estate and finance leaders from the advisory board of the Mayor’s Fund, a move widely read in the industry press as a more confrontational posture toward business, as reported by The Real Deal and the New York Post. Real estate and finance figures have described the agenda as anti investment and warned that taxing high earners and freezing stabilized rents could weaken future housing supply and the city tax base. Some brokers reported that luxury demand cooled in early summer 2026 and attributed hesitation among affluent buyers to the new administration and to proposals aimed at high value second homes, as reported by the New York Post in July 2026. The evidence is genuinely mixed, however. At least one brokerage quoted in that same coverage said there was no concrete evidence that wealthy residents were leaving New York at an accelerated pace, and claims of a millionaire exodus have come largely from opinion commentary rather than hard migration data. Supporters counter that asking higher earners and luxury owners to contribute more is a matter of fairness and a way to fund services under strain. For an investor the key point is not which side is right, but that policy uncertainty and a more adversarial tone toward capital are now part of the Manhattan underwriting picture, most sharply for rent stabilized assets and for the very top of the luxury and second home market.
The hardest constraint on all of this is the city budget. New York City runs one of the largest municipal budgets in the country, on the order of 122 to 126 billion dollars across fiscal years 2026 and 2027, yet it faces sizable projected gaps. The New York City Comptroller has estimated a shortfall of about 2.2 billion dollars in fiscal year 2026 and about 10.4 billion dollars in fiscal year 2027, with gaps continuing in the following years. In July 2026 the administration asked city agencies to identify savings ahead of these deficits. Because most of the new revenue in the mayor’s plan, the higher taxes on corporations and on incomes above one million dollars, requires approval in Albany from the state legislature and the governor, the funding side of the agenda is neither automatic nor within the mayor’s sole control.
| New York City budget gap, Comptroller estimate | Amount |
|---|---|
| Fiscal year 2026 | -2.2 billion dollars |
| Fiscal year 2027 | -10.4 billion dollars |
| Fiscal year 2028 | -10.06 billion dollars |
| Fiscal year 2029 | -8.58 billion dollars |
| Fiscal year 2030 | -6.96 billion dollars |
These gaps matter for real estate in two directions. On one side, pressure to close multibillion dollar deficits can lead to spending restraint that touches capital projects, services, and staffing, all of which affect neighborhood quality and long run demand. On the other side, the search for revenue keeps alive proposals that bear directly on property, including changes to the property tax system, transfer taxes, and the proposed levy on high value second homes. The combination of a large structural gap and a dependence on Albany creates a two way risk for owners: services and public investment could tighten, while the tax treatment of high earners and property could become less favorable if the state acts.
None of this changes the deep fundamentals of Manhattan, which rests on scarce land, a very large and diverse employment base, and durable global demand, and which has outlasted many administrations and cycles. The near term policy overlay does, however, introduce specific factors that an investor may wish to consider when analyzing Manhattan assets in 2026. Among the factors relevant to underwriting are the possibility of zero regulated rent growth for the current cycle, the range of proposed taxes as potential scenarios rather than settled facts, and the different sensitivity of demand across segments, from employment and housing need on one end to discretionary luxury and tax driven demand on the other. The outcome of the rent freeze litigation and the Albany legislative session are two developments that could affect regulated cash flows and the after tax return on Manhattan real estate, and both are worth monitoring. This is educational information only and not investment advice or a recommendation to buy, sell, or hold any security or to pursue any strategy.
Section 16Infrastructure
Manhattan’s infrastructure network is a major strength and a defining feature of its real estate market. The island is served by an extensive subway system that connects it to the other boroughs and to parts of New Jersey through multiple tunnels and bridges. Commuter rail lines from Long Island, Westchester, and New Jersey converge at Penn Station and Grand Central Terminal, feeding daily flows of workers into Midtown and downtown job centers.
Bus networks, ferry services across the Hudson and East Rivers, and bike lanes expand mobility options. Major bridges and tunnels provide vehicular access, though congestion and limited parking make car ownership less central to daily life than in many other United States cities.
Air connectivity is provided by major airports in Queens and New Jersey, which serve domestic and international flights, and by smaller facilities for regional and private aviation. Manhattan itself hosts key infrastructure such as tunnels, bridges, sewers, water mains, electrical substations, and telecommunications hubs, much of which has been in service for many decades and is the subject of ongoing maintenance and upgrade programs.
Public investment in transit, water and sewer systems, streets, and coastal protection is essential for the resilience and long term value of Manhattan real estate. Projects to modernize subway signals, improve accessibility, repair tunnels, and reinforce coastal areas are underway in various forms, though this review does not provide a full inventory or budget summary. For investors, the main point is that properties near well maintained and reliable infrastructure tend to retain value and attract tenants, while those in areas with persistent infrastructure challenges may face higher risks and costs.
Section 17Climate and Physical Risks
Manhattan faces several important climate and physical risks that matter for real estate. Coastal storms, sea level rise, extreme rainfall, heat waves, and potential infrastructure failures are all relevant.
The Federal Emergency Management Agency explains that flood risk can exist even in areas that do not sit directly on a coastline or river, and that any area with at least a one percent annual chance of flooding is considered high risk, with at least a one in four chance of flooding over a thirty year mortgage period. FEMA flood maps designate special flood hazard areas and lower risk areas, and they inform insurance requirements and mitigation planning. In Manhattan, coastal neighborhoods along the Hudson and East Rivers, low lying areas near the southern tip of the island, and certain parts of the East Side and West Side are within or near these high risk zones.
The National Centers for Environmental Information maintain extensive records of climate and weather data, including temperature trends, precipitation patterns, and storm histories. NCEI notes that it archives more than two hundred twenty nine terabytes of data each month from more than one hundred thirty observing platforms and that it provides access to climate and weather data through multiple platforms. While this review does not extract Manhattan specific climate values from NCEI, the existence of that archive underscores the depth of data available to technical analysts who wish to model climate risks for particular sites.
Heat waves and extreme rainfall events are of particular concern in dense urban environments. High temperatures can stress building systems and residents, especially in older buildings without modern cooling, while intense rainfall can overwhelm sewer and drainage systems, leading to street and basement flooding. Rising sea levels and more intense coastal storms increase the risk of surge in low lying areas of Manhattan, including parts of Lower Manhattan and the waterfronts.
For investors, climate risk analysis in Manhattan should include review of FEMA flood maps, building elevation and structure, presence of critical mechanical systems in basements or on lower levels, and known flood histories. It should also consider the resilience measures that have been implemented or planned, such as flood walls, deployable barriers, upgraded drainage, and building improvements. Insurance availability and pricing, discussed earlier, is tightly linked to these risks.
Section 18Neighborhood by Neighborhood Analysis
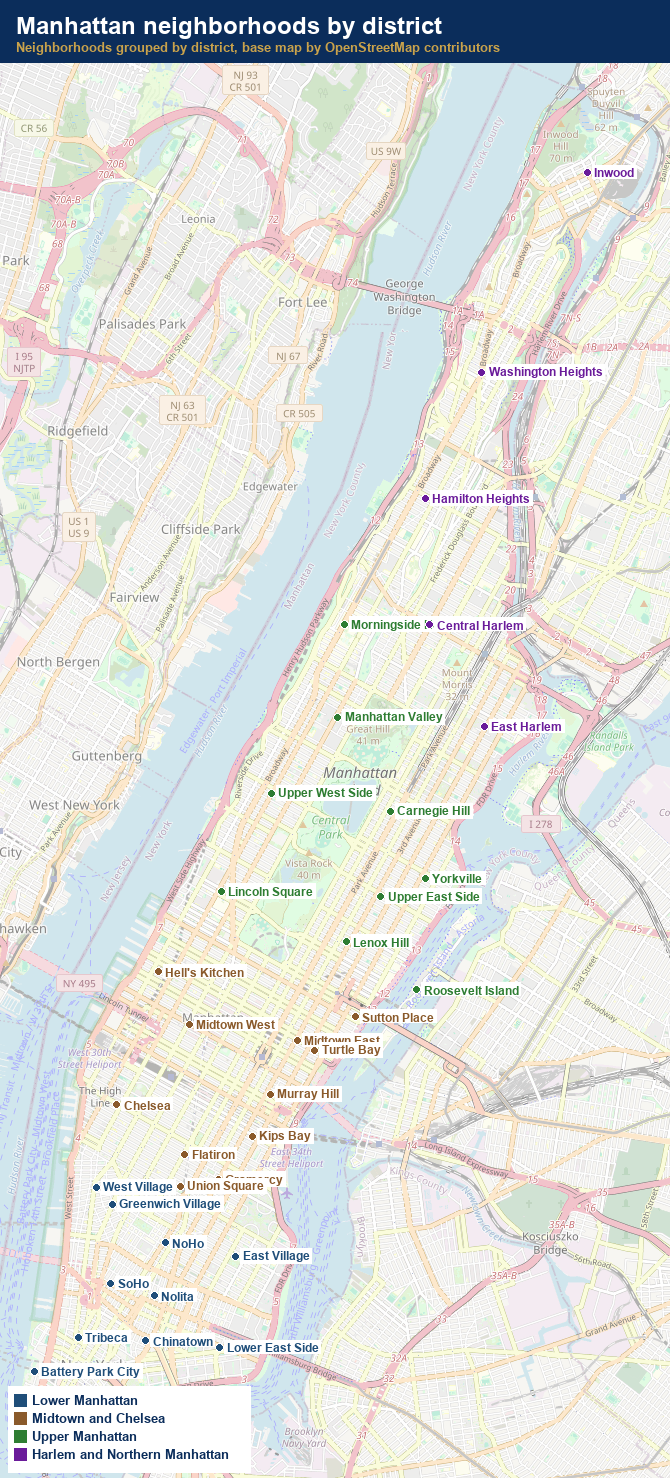
Financial District. The Financial District at the southern tip of Manhattan is characterized by a dense mix of office towers, converted office to residential buildings, and historic narrow streets. Housing stock includes large rental buildings, many of which are recent office conversions, as well as condominiums and a smaller number of co op units in older structures. Prices and rents here have historically been somewhat lower than in prime neighborhoods uptown, reflecting a trade off between access to subway lines and the business district on one hand, and limited neighborhood retail and schools on the other, though improvements in local amenities have narrowed that gap. Residents include finance and legal professionals who value proximity to work, young households who appreciate loft style apartments and river views, and some families who choose newer buildings with amenities. Demand is driven by the presence of major employers in finance and insurance, by improved waterfront parks, and by ongoing residential conversions that bring more residents and retail. Investor strategies often focus on large rental assets that can capture demand for relatively newer product at a discount to Midtown and downtown condos that appeal to buyers who want modern finishes and views. Risks include office market weakness that can affect street life and local services, exposure to storm surge in coastal areas, and dependence on a still evolving mix of residential and commercial uses.
Battery Park City. Battery Park City is a planned residential and commercial community built on landfill along the Hudson River, with a significant share of its land under ground leases. Housing stock is dominated by relatively modern rental and condo towers, with large units, views, and access to parks and waterfront promenades. Prices and rents are generally high, though they sometimes trade at a slight discount to the most prestigious Upper East Side and downtown neighborhoods, in part due to the ground lease structure and perceived distance from some cultural amenities. Residents include families, professionals working in nearby downtown offices, and some retirees drawn by the parks and walkability. Demand is driven by the quality of public space, schools, and the relative quiet compared with more commercial parts of downtown. Investors in Battery Park City must understand the terms of land leases, the governance and financial health of the Battery Park City Authority, and the long term outlook for ground rent increases. Strategies can include long term hold of rental assets that appeal to families and high income tenants, and condo investment in buildings with strong management. Risks center on ground lease dynamics, coastal flood risk, and sensitivity to changes in the office workforce in Lower Manhattan.
Tribeca. Tribeca has transformed from an industrial area into one of the most expensive and desirable residential neighborhoods in Manhattan. Housing stock features large loft conversions, luxury condos, boutique co ops, and a limited number of townhouses. Many units offer high ceilings, generous floorplates, and industrial architectural details, along with modern finishes. Prices and rents in Tribeca are among the highest in Manhattan, reflecting strong demand from high income households, including finance and media executives and celebrities, who value privacy, space, and access to top restaurants and schools. The tenant and buyer profile skews toward families and affluent couples who can afford premium pricing and who often hold properties for long periods. Demand drivers include proximity to downtown offices, excellent neighborhood amenities, and the distinct urban fabric of cobblestone streets and historic buildings. Investor strategies focus on high end condo projects, well located rental buildings with large units, and mixed use properties with strong retail frontage. Risks include high entry costs, sensitivity to financial sector income and bonus cycles, and potential saturation at the very high end of the market.
SoHo. SoHo is known for its cast iron buildings, cobblestone streets, and status as a fashion and retail destination. Housing stock consists of loft co ops and condos in converted commercial buildings, along with a limited number of purpose built residential properties. Units are often large, with open layouts, high ceilings, and large windows. Prices and rents are very high, with a premium for renovated lofts and buildings on quieter side streets. Residents include creative professionals, executives, and international buyers who value the neighborhood’s aesthetic and retail offerings. Demand is driven by the combination of residential appeal and a dense cluster of boutiques, galleries, and restaurants. Investor strategies include owning and repositioning loft buildings, investing in retail spaces along key corridors, and participating in mixed use projects that combine retail and residential uses. Risks include sensitivity of retail rents to shifts in tourism and fashion retail dynamics, challenges related to landmark and historic preservation rules, and noise and congestion associated with heavy visitor traffic.
NoHo. NoHo, just north of Houston Street, is a small, highly desirable neighborhood with a mix of historic loft buildings and newer luxury developments. Housing stock is mainly condos and co ops in converted commercial buildings, along with a few newly constructed high end towers. Prices and rents are high, often comparable to SoHo, though the neighborhood has a somewhat more residential and less tourist oriented feel. Residents include affluent professionals, creative industry leaders, and long time New Yorkers who appreciate the central location and mix of quiet streets and nearby nightlife and dining. Demand drivers include proximity to downtown and Midtown, excellent transit access, and the charm of low and mid rise buildings with distinctive architecture. Investors face limited supply and high pricing, with opportunities mainly in boutique condo projects and mixed use properties. Risks relate to high basis costs, limited opportunities for scale, and potential regulatory constraints due to landmark status and zoning.
Nolita. Nolita, short for north of Little Italy, is a compact, fashionable neighborhood with narrow streets, low rise walk ups, and a lively retail scene. Housing stock includes walk up rental buildings, smaller co ops and condos, and some newer boutique developments. Units tend to be smaller than in loft heavy neighborhoods, and buildings often lack full service amenities. Rents and prices are high relative to most of Manhattan but somewhat lower than in SoHo and Tribeca, which makes Nolita attractive to affluent renters and buyers who want a central location and character but are willing to accept smaller spaces and fewer amenities. Residents are often young professionals, couples, and some creative industry figures. Demand is driven by the intimate street scale, dining and retail options, and proximity to SoHo, the Lower East Side, and NoHo. Investor strategies can focus on repositioning small rental buildings, assembling and redeveloping parcels into boutique condos, and investing in ground floor retail. Key risks include tenant turnover in smaller units, retail exposure to changing consumer preferences, and the difficulty of scaling investments in a small neighborhood.
Chinatown. Chinatown has a distinctive cultural and commercial identity, with a dense mix of small businesses, restaurants, and residential buildings. Housing stock consists mainly of older tenement style walk ups, mixed use buildings with retail at the base and apartments above, and some newer condominiums on the edges. Many residential units are rent stabilized or otherwise regulated, and the area has historically offered relatively lower rents compared with nearby SoHo or Tribeca. Residents include long standing Chinese and other Asian communities, immigrant families, and more recently, some young professionals attracted by lower housing costs and proximity to downtown and Midtown. Demand drivers include cultural ties, affordability relative to certain neighboring areas, and access to transit. Investor strategies often involve long term ownership of mixed use buildings with stable retail tenants and regulated apartments, and selective participation in condo developments on the fringes of the neighborhood. Risks include regulatory scrutiny around tenant protections, community opposition to displacement, and vulnerability of small businesses to economic shocks.
Lower East Side. The Lower East Side has evolved from a primarily working class immigrant neighborhood into a mixed income area with a blend of public housing, older walk ups, and newer luxury developments. Housing stock includes tenement style rentals, midcentury public housing towers, new high rise condos and rentals on the waterfront and certain avenues, and small co op buildings. Rents and prices vary widely, with some streets still offering relatively moderate rents and others commanding premium pricing in new developments. Residents include long time families, artists, younger professionals, and increasingly, higher income households drawn by new restaurants, nightlife, and proximity to downtown. Major developments and rezonings along the waterfront have introduced large new residential buildings and retail, changing the skyline and local dynamics. Investor strategies range from value add repositioning of older walk ups, with careful attention to regulatory status, to participation in large scale new developments. Risks involve community resistance to displacement, regulatory controls, concentration of nightlife uses that can create quality of life issues, and potential oversupply in certain luxury segments.
East Village. The East Village is known for its artistic history, nightlife, and student and young professional population. Housing stock is heavily composed of older walk up rental buildings, mixed use structures with retail at the base, and some postwar and newer midrise buildings. There are also multiple large public and subsidized housing complexes. Rents are relatively high for small units, given the neighborhood’s desirability, though still below prime luxury corridors. Residents are often students, young professionals, artists, and long time tenants in stabilized units. Demand is driven by nightlife, restaurants, and easy access to downtown and Midtown. Investor strategies often involve owning and improving smaller rental buildings, capturing upside through renovation of units and common areas, and leasing retail to food and beverage operators. Risks include regulatory limits on rent increases in stabilized units, potential neighborhood resistance to changes that are perceived to threaten character, and cyclical sensitivity of nightlife focused retail.
Greenwich Village. Greenwich Village is a historic residential neighborhood with tree lined streets, low and mid rise buildings, and a mix of co ops, condos, rental buildings, and townhouses. Housing stock includes prewar elevator buildings, brownstones and townhouses, and some postwar co ops. Prices and rents are high, reflecting the neighborhood’s central location, charm, and amenities. Residents include professionals, academics, artists, and long term households. Demand is driven by proximity to universities, cultural institutions, and Lower Manhattan jobs, as well as the appeal of Washington Square Park and surrounding streets. Investor strategies may include acquisition and repositioning of small multifamily or mixed use buildings, participation in condominium projects that restore historic structures, and careful stewardship of ground floor retail. Risks involve very high acquisition costs, landmark preservation restrictions, and sensitivity to broader changes in Manhattan high end housing demand.
West Village. The West Village shares many traits with Greenwich Village but is often viewed as even more exclusive, with a concentration of townhouses, renovated tenements, and low rise co ops and condos. The neighborhood is characterized by irregular streets, limited through traffic, and a village like feel. Housing stock is weighted toward smaller buildings and townhouses rather than large towers. Prices and rents are among the highest on a per square foot basis in Manhattan for both rental and ownership properties. Residents include high income professionals, celebrities, and long term New Yorkers who value privacy and neighborhood character. Demand is anchored by the neighborhood’s aesthetic, restaurants, proximity to the Hudson River Park, and relative calm compared with other busy districts. Investment opportunities are often limited to small scale acquisitions, careful repositioning of townhouses or multi unit buildings, and niche retail investments. Risks involve very high entry pricing, strict preservation rules, and limited ability to add density or scale.
Chelsea. Chelsea is a diverse neighborhood that spans from the Hudson River to Sixth Avenue, with housing stock ranging from public housing and older walk ups to high end condos and rental towers near the High Line and Hudson Yards. Co ops and condos in prewar and postwar buildings offer a range of unit sizes and finishes. Rents and prices are high, though they vary between the waterfront, central avenues, and eastern parts of the neighborhood. Residents include professionals, artists, and families, with a notable share of creative and technology workers. Demand drivers include art galleries, the High Line, proximity to Midtown and downtown office districts, and better public spaces along the Hudson. Investor strategies may focus on rental buildings that benefit from proximity to amenities, on repositioning older walk ups, and on ground floor retail in high foot traffic corridors. Risks include competition from newer product in adjacent neighborhoods such as Hudson Yards, potential oversupply in some luxury segments, and ongoing changes in gallery locations and retail tenant mix.
Flatiron. The Flatiron area, around the iconic Flatiron Building and Madison Square Park, has a mix of commercial loft style buildings, office properties, and residential buildings. Housing stock includes co op and condo units in converted commercial buildings, as well as some rental towers. Prices and rents are high, reflecting central location, historic architecture, and proximity to technology and media employers that cluster in Midtown South. Residents include professionals in technology, media, and finance who value walkable access to office and lifestyle amenities. Investor strategies focus on mixed use properties with strong retail, boutique residential assets, and office buildings that can attract creative and technology tenants. Risks include competition from other Midtown South neighborhoods, potential shifts in office location preferences, and high operating costs.
Gramercy. Gramercy is centered around Gramercy Park and surrounding blocks, with a strong residential character and a concentration of co op buildings, condos, and townhouses. Gramercy Park itself is private, accessible only to key holders, which adds an aura of exclusivity and supports premium pricing for properties on the park. Housing stock includes prewar elevator buildings, postwar co ops, and townhouses. Rents and prices are high but may not reach the very top tier found in a few ultra luxury neighborhoods. Residents include professionals, families, and long time co op owners. Demand is driven by the park, quiet streets, central location, and proximity to Midtown and downtown employment centers. Investor strategies may involve small scale condo or co op conversions, acquisition of rental buildings for long term hold, and careful engagement with co op boards when relevant. Risks involve limited supply, strict co op policies, and high initial pricing.
Union Square. Union Square is a busy commercial and transportation hub with a mix of residential and commercial buildings. Housing stock includes rental and condo towers, loft conversions, and walk up buildings on side streets. Prices and rents are high due to location and transit convenience. Residents include students, young professionals, and families who value the central square, farmers market, and access to multiple subway lines. Demand drivers include the presence of major retail stores, office buildings, and educational institutions. Investor strategies often focus on mixed use buildings with strong retail and office or residential components, capitalizing on high foot traffic. Risks include exposure to retail cycles, competition from nearby areas, and the challenge of managing assets in a very active public space.
Murray Hill. Murray Hill is a primarily residential neighborhood east of Midtown, with midrise rental and co op buildings, some high rise condos, and a scattering of townhouses. Housing stock tends toward smaller units and postwar elevator buildings. Rents and prices are moderate relative to other central Manhattan neighborhoods, which makes Murray Hill attractive to young professionals who work in Midtown or the East Side and to some medical professionals linked to nearby hospitals. Residents are often at earlier stages of their careers, which can lead to higher turnover. Demand is driven by convenience, relative value, and proximity to office centers. Investor strategies may focus on stable rental assets that appeal to this tenant base and on incremental upgrades that improve building appeal without requiring ultra luxury positioning. Risks include competition from newer product in other neighborhoods and potential headwinds if office demand in nearby districts declines.
Kips Bay. Kips Bay sits between Murray Hill and Gramercy, with a strong presence of medical institutions and a mix of residential buildings. Housing stock includes large rental complexes, co ops, and some condos, as well as townhouses on quieter streets. Rents and prices are moderate to high, influenced by proximity to hospitals and medical schools. Residents include hospital workers, medical students, and professionals who want access to Midtown and downtown. Demand drivers are stable, given the institutional anchors in the area, and retail skewed toward local services, supermarkets, and restaurants supports daily needs. Investor strategies can emphasize stable cash flow from rental buildings that serve medical and office workers, with opportunities for targeted upgrades. Risks are relatively modest compared with more cyclical neighborhoods, though changes in institutional footprints or health care policy could affect demand over longer horizons.
Hell’s Kitchen and Clinton. Hell’s Kitchen and Clinton, west of Midtown, have a mix of walk ups, midrise buildings, large rental towers, and public housing. Housing stock ranges from older tenement style buildings to newer high rise rentals and condos near the Hudson River. Rents and prices are high for newer product, while older buildings may offer more moderate rents. Residents include a mix of long time tenants, theater and arts workers, and professionals, as well as some newer higher income households in waterfront developments. Demand is driven by proximity to Midtown offices, the theater district, and the Hudson River Park, as well as a lively restaurant and bar scene. Investor strategies include repositioning older walk ups while navigating regulatory constraints, investing in newer rental assets with amenities, and participating in ground floor retail in busy corridors. Risks include noise and congestion, potential oversupply in certain high rise segments, and future changes in Midtown office demand.
Midtown East. Midtown East is a major office district that also includes significant residential pockets, especially in areas such as Turtle Bay, Sutton Place, and parts of the East Side north of the core business district. Housing stock ranges from luxury co ops and condos in towers with East River views to midrise rental and co op buildings, as well as some townhouses. Prices and rents are high, especially for buildings with water views or proximity to parks and transit. Residents include professionals who work in nearby offices, diplomats and staff associated with the United Nations, and long time co op owners. Demand is driven by access to employment, transit, and services. Investor strategies focus on high quality residential buildings that benefit from stable demand and on mixed use properties that combine office or retail with residential. Risks include exposure to office market volatility and future zoning or planning changes that could alter density or land use.
Midtown West. Midtown West, including areas near Times Square and the western reaches toward the Hudson River, has a dense mix of office towers, hotels, theaters, and residential buildings. Housing stock includes rental towers that serve workers in Midtown and the theater district, as well as newer condos and rentals nearer the Hudson. Prices and rents are high in newer buildings, though some older stock offers more moderate rents. Residents include theater workers, hospitality workers, and professionals in various sectors. Demand is driven by the concentration of employers, entertainment venues, and transit. Investor strategies include hotel ownership, rental buildings that serve the workforce, and mixed use projects in corridors with strong visibility. Risks involve cyclicality in tourism, evolving patterns of office occupancy, and the potential for crowding and noise to affect residential desirability.
Turtle Bay. Turtle Bay, near the East River and United Nations complex, is a residential neighborhood characterized by a mix of midrise co op and condo buildings and some townhouses. Housing stock includes both prewar and postwar buildings, often with doorman services and amenities. Prices and rents are high but may be somewhat lower than in top tier Upper East Side neighborhoods. Residents include diplomats and staff connected to the United Nations, professionals in Midtown offices, and long time residents. Demand is supported by proximity to international institutions, consulates, and office corridors, as well as access to parks along the East River. Investor strategies focus on stable rental and ownership buildings that can attract this tenant and buyer base. Risks include security measures related to international institutions that can affect traffic and access, and potential changes in diplomatic footprints.
Sutton Place. Sutton Place is a small, prestigious neighborhood along the East River, known for quiet streets and luxury co op buildings. Housing stock consists mainly of co ops in prewar and postwar buildings, some with river views and private amenities. Prices and maintenance levels are high, and the buyer profile includes affluent households who value privacy and a quieter environment. Rents are also high where rentals are available, though much of the stock is owner occupied. Demand is driven by location, building quality, and neighborhood character. Investor opportunities are limited, given the dominance of co ops and the discretion of boards, but niche plays in condos or rental buildings can be attractive for long term holds. Risks involve limited liquidity in a small, highly selective market segment.
Upper East Side including Lenox Hill, Yorkville, and Carnegie Hill. The Upper East Side is a large and varied residential area with sub neighborhoods. Lenox Hill includes a mix of luxury co ops, condos, and rentals near Central Park and major avenues. Carnegie Hill is known for elegant townhouses and co ops near museums and schools. Yorkville, farther east, has historically offered more moderate prices and rents, though recent development and the addition of the Second Avenue subway have increased demand and values. Housing stock spans prewar co ops, postwar towers, new condo developments, townhouses, and walk ups. Prices and rents are among the highest in the city in certain parts, especially near the park, while Yorkville still offers relative value. Residents include high income professionals, families, retirees, and a variety of others. Demand is supported by schools, proximity to Central Park, cultural institutions, and shopping corridors. Investor strategies include acquiring and operating rental buildings in Yorkville and other portions of the Upper East Side, participating in condo developments in select locations, and holding or repositioning townhouses. Risks involve high capital costs, co op governance constraints, and competition among high end offerings.
Upper West Side including Lincoln Square and Manhattan Valley. The Upper West Side stretches from Columbus Circle northward, with sub areas such as Lincoln Square near the performing arts complex and Manhattan Valley farther north. Housing stock includes prewar co ops, rental buildings, condos, and townhouses, many with architectural character. Prices and rents are high, with some variation between Lincoln Square, the central avenues, and Manhattan Valley, where prices have traditionally been lower. Residents include families, professionals, academics, and artists. Demand is driven by parks on both sides, cultural institutions, schools, and a strong sense of neighborhood identity. Investor strategies focus on stable rental holdings, condo units in desirable buildings, and selective townhouse investments. Risks include high entry costs, regulatory constraints on rent stabilized units, and competition in the high end segment.
Morningside Heights. Morningside Heights is home to major educational institutions and religious organizations, including Columbia University and multiple seminaries and churches. Housing stock mixes rental buildings, co ops, condos, and university owned housing, as well as some townhouses. Prices and rents are moderate to high, influenced by the presence of students, faculty, and staff, and by broader Upper Manhattan trends. Residents include students, faculty, professionals, and long time residents. Demand is strongly supported by institutional anchors and access to parks along the Hudson and Morningside Park. Investor strategies often involve owning rental properties that serve the university community, with relatively low long term vacancy risk, and participating in condo projects that attract faculty and others. Risks include institutional expansions that can alter neighborhood dynamics, potential caps on student housing demand, and regulatory considerations.
Central Harlem. Central Harlem has a rich cultural history and a diverse housing stock that includes brownstones, walk up apartment buildings, larger rental and condo buildings, and public and subsidized housing. Rents and prices have increased significantly over the past two decades, though they remain lower than in many downtown neighborhoods. Residents include long time families, newer arrivals from other parts of the city and country, and an active cultural and artistic community. Demand is driven by heritage, improving retail and restaurant offerings, and relative affordability for larger units. Investor strategies include acquisition and improvement of brownstones and small multifamily buildings, participation in new rental and condo developments, and investment in mixed use buildings on commercial corridors. Risks involve community concerns about displacement and gentrification, regulatory scrutiny, and potential cyclical volatility as neighborhoods transition.
East Harlem. East Harlem, also known as El Barrio, has a mix of public housing, walk up apartment buildings, larger rental developments, and emerging condo and rental projects. Rents and prices are generally lower than in Central Harlem and other parts of Manhattan, although they have risen over time. Residents include long established Latino communities, other families, and newer households. Demand is influenced by access to transit, relative affordability, and the presence of cultural and community institutions. Investor strategies focus on long term ownership of multifamily properties that can benefit from gradual neighborhood improvement while navigating regulatory and community expectations. Risks include concentration of regulated housing, local economic challenges, and sensitivity to broader economic cycles.
West Harlem and Hamilton Heights. West Harlem and Hamilton Heights include a combination of historic townhouses, walk up and elevator apartment buildings, and some newer developments. Housing stock features brownstones on side streets and larger buildings on avenues. Prices and rents are higher than in parts of East Harlem but lower than in many downtown neighborhoods, offering relative value for larger units and historic properties. Residents include students and staff from nearby institutions, families, and professionals seeking more space. Demand is driven by access to parks along the Hudson, transit connections, and neighborhood character. Investor strategies often focus on brownstone acquisitions and renovations, as well as multifamily holdings near transit. Risks include building condition issues in older stock, needed capital investment, and potential regulatory or community concerns.
Washington Heights. Washington Heights is a predominantly residential neighborhood with a large population of families and immigrants, especially from Dominican and other Latino communities. Housing stock consists of prewar elevator buildings, walk ups, co ops, and some newer buildings. Rents and prices are lower than in many other Manhattan neighborhoods, though they have increased over time. Residents include families, working class households, and some students and professionals. Demand is supported by relative affordability, strong community ties, and proximity to parks and bridges that connect to the Bronx and New Jersey. Investor strategies often involve owning and operating multifamily buildings with a focus on steady cash flow and long term holds. Risks include income sensitivity of tenant populations, regulatory protections for tenants, and limited ability to reposition buildings aggressively.
Inwood. Inwood at the northern tip of Manhattan has a quieter, more residential feel, with large parks and a mix of apartment buildings and some small homes. Housing stock includes prewar multifamily buildings, co ops, and a few newer developments. Rents and prices are generally at the lower end of the Manhattan range, making Inwood attractive to households seeking more space and access to green areas at lower cost. Residents include families, long time tenants, and some newer arrivals. Demand is linked to parks, relative affordability, and transit along the Broadway corridor. Investor strategies can focus on stable multifamily holdings and selective acquisition of value add properties. Risks involve slower liquidity due to distance from central business districts and tenant income sensitivity.
Roosevelt Island. Roosevelt Island sits in the East River between Manhattan and Queens and has a unique housing and governance structure, with a mix of rental and ownership buildings developed under various public and private frameworks. Housing stock includes high rise rental complexes developed under state programs, newer condos and rentals, and some specialized facilities. Prices and rents are generally lower than in comparable Manhattan neighborhoods across the river, though they can still be high compared with many outer borough locations. Residents include families, professionals, and others attracted by water views, parks, and a quieter environment, as well as staff and students associated with institutional facilities such as a technology campus. Demand is driven by relative value and unique setting, although connectivity relies heavily on a small set of transit options. Investor opportunities are limited by the structure of land leases and regulatory frameworks, but certain assets can offer stable returns. Risks include governance complexity, limited retail, and dependence on a narrow set of access points.
Section 19Opportunities
Manhattan offers several opportunity themes for accredited investors willing to engage deeply with its complexities.
One opportunity lies in stable, well located multifamily properties that can deliver consistent income in a supply constrained environment. Even without precise public rent and vacancy numbers, the combination of high housing demand, limited land, and institutional anchors suggests that quality multifamily assets in neighborhoods such as the Upper West Side, Upper East Side submarkets, parts of Harlem, and selected downtown districts may perform over long horizons when acquired at reasonable basis and managed with attention to tenant relations and building condition, though no particular outcome is assured.
Another opportunity is to selectively back repositioning and conversion plays in office and mixed use buildings. As some older office properties struggle to retain tenants, investors with the ability to execute complex business plans may find value in converting suitable buildings to residential, hotel, or mixed uses, or in upgrading and retenanting them as high quality office space. Success requires careful analysis of building layout, zoning, structural constraints, and capital needs, as well as realistic assumptions about future demand in each segment.
A third opportunity involves targeting neighborhoods that combine relative affordability with improving amenities and connectivity, such as parts of Harlem, Washington Heights, Inwood, and portions of the Lower East Side and East Village that still have room for growth. In these areas, carefully structured investments in regulated and free market buildings can capture long term appreciation, provided they respect community context and regulatory constraints; outcomes are not assured.
Condo and co op strategies also offer potential. Boutique condo projects in select neighborhoods can succeed when they match local buyer preferences for layout, finishes, and amenities and when pricing is aligned with depth of demand. Acquiring individual units or small packages in existing buildings can provide exposure to ownership demand without the complexity of ground up development.
Finally, ground floor retail in corridors that serve stable residential populations, such as certain stretches of the Upper West Side, Upper East Side, and neighborhood centers in Harlem, can offer durable cash flows if leased to essential services and well capitalized tenants. Such assets may be less sensitive to shifts in tourism and commuter patterns than flagship retail on prime avenues.
Section 20Risks
The same features that create opportunity in Manhattan also introduce significant risks.
Regulatory risk is central. Changes in rent regulation, property tax policy, zoning, and other rules can materially alter the economics of multifamily and commercial investments. Recent history has shown that state level reforms can quickly change how landlords manage units and how investors underwrite value. Without current statutory details, this review cannot outline every specific risk, but investors must treat regulatory change as an embedded feature of the Manhattan market.
Data limitations in this environment also create risk. The inability to access official public figures on Manhattan population, income, rents, and vacancy means that investors cannot rely on this review for exact benchmarks. Instead, they must ensure they have robust alternative data sources when making commitments. Investing on the basis of incomplete or outdated information can lead to mispriced risk.
Market cycle and structural risks are present in the office and retail sectors, where secular changes in work and shopping patterns continue to play out. Some buildings may never return to prior rent or occupancy levels, and capex requirements to reposition them can be substantial. In residential segments, high price levels and tighter financing conditions increase sensitivity to macroeconomic shocks and interest rate changes.
Climate and physical risks, including flood, storm, heat, and infrastructure vulnerabilities, pose both direct damage and indirect financial risks. Buildings in vulnerable locations may face rising insurance costs, higher capital expenditures, or declining tenant and lender appetite over time.
Finally, liquidity risk is real, even in a market as deep as Manhattan. While there are often many potential buyers for high quality assets, periods of market stress can lead to wide bid ask spreads, longer marketing times, and forced sales at unfavorable prices. Leveraged investors are especially exposed if loan maturities arrive during such periods.
Section 21Investor Implications
For accredited investors, Manhattan should be approached as a sophisticated, segmented market rather than as a monolithic bet on New York City. The combination of high pricing, complex regulation, data limitations in this environment, and divergent performance across asset classes calls for nuanced strategies.
Investors who prioritize income stability may focus on well located multifamily or mixed use properties in neighborhoods with diverse tenant bases and limited new supply. They should underwrite conservative rent growth, account for potential future regulatory changes, and plan for ongoing capital expenditures to maintain building competitiveness.
Those with a tolerance for more complexity and risk may pursue value add or opportunistic plays in office, hospitality, or mixed use assets that require repositioning or conversion. These strategies can offer higher return potential but demand deep local expertise, strong execution capabilities, and resilient capital structures, and no particular outcome is assured.
Condo and co op investments can serve both as exposure to ownership demand and as a means to diversify portfolios, but they require careful attention to building level financials, governance, and legal structures.
Across all strategies, investors should incorporate scenario analysis into underwriting, testing how assets perform under different rent, vacancy, interest rate, tax, and insurance cost paths. They should also recognize that some benefits of Manhattan exposure, such as global connectivity and brand value, are intangible and do not guarantee financial returns without disciplined acquisition and asset management.
Section 22Conclusion
Manhattan remains a central market for United States and global real estate investors, with a deep and diverse economy, a unique housing stock, and enduring cultural and institutional anchors. Public data available in this environment show a massive metropolitan labor market with more than ten million people in the labor force, low to mid single digit unemployment, and modest job growth, alongside a citywide housing market where prices have risen moderately over the past year while marketing times have lengthened and transaction volumes have declined.
At the same time, key official public datasets on Manhattan’s own population, income, rent, and vacancy profiles are not accessible here due to technical blocks on Census and certain city websites. No official public information is available on this point for many of the borough specific metrics that would normally anchor a flagship review. As a result, this commentary leans on metropolitan labor data, citywide housing metrics, and qualitative neighborhood analysis to map the contours of opportunity and risk.
For accredited investors, the implication is clear. Manhattan is a market where detailed local knowledge, access to high quality proprietary data, and strong relationships with experienced professionals matter at least as much as macro narratives. The consequences of misjudging regulatory, physical, or market risks can be significant, and no particular outcome is assured. Used thoughtfully, Manhattan exposure can play a role in a diversified portfolio, as a potential source of income, diversification, and long run appreciation, but only when paired with rigorous analysis and prudent structuring.
Sources
- United States Bureau of Labor Statistics, New York Newark Jersey City New York New Jersey Pennsylvania Economy at a Glance, not seasonally adjusted data for civilian labor force, employment, unemployment, unemployment rate, total nonfarm employment, and sector employment including mining logging and construction, manufacturing, trade transportation and utilities, information, and financial activities, with twelve month percent changes, January through June 2026, extracted August 7 2026. ,, https://www.bls.gov/eag/eag.ny_newyork_msa.htm
- Redfin, New York New York housing market, city housing market overview for the three months ending May 2026, including median sale price of 875,726 dollars for all home types, a 3.0 percent year over year increase in median sale price, median sale price per square foot of 662 dollars, a 0.23 percent year over year decline in price per foot, average days on market of 78 days compared with 67 days a year earlier, 7,091 homes sold in May 2026 compared with 7,567 a year earlier, and an average sale to list price ratio of 98.2 percent with a 0.2 percentage point year over year increase, plus migration statistics showing that 3 percent of Redfin homebuyers nationwide searched to move into New York, that 77 percent of New York homebuyers searched to stay within the New York metropolitan area, and that there were net inflows from metros such as Seattle and Kalamazoo and net outflows of 4,315 users to Miami, 3,046 to Philadelphia, and 1,664 to Orlando between January and March 2026, viewed August 7 2026. ,, https://www.redfin.com/city/30749/NY/New-York/housing-market
- United States Census Bureau, QuickFacts New York County New York, which in this environment returns a Cloudflare security page stating that access to www dot census dot gov is blocked due to a security service, and provides no population, income, or housing data, viewed August 7 2026. ,, https://www.census.gov/quickfacts/newyorkcountynewyork
- StreetEasy, data dashboard and market reports pages for Manhattan, which in this environment return a page not found message and navigation links to data dashboard, market reports, and neighborhood data without exposing any numeric rent or price figures in the readable extract, confirming that no Manhattan specific StreetEasy rent metrics can be used here, viewed August 7 2026. ,, https://streeteasy.com/blog/data-dashboard-manhattan/
- Zillow, New York New York home values, which in this environment returns an access denied page stating that access has been blocked, with no numeric home value or rent data in the readable content, viewed August 7 2026. ,, https://www.zillow.com/new-york-ny/home-values/
- New York City Rent Guidelines Board, publications page, which in this environment appears as an outdated or non existing city page without listing numeric rent guideline percentages or housing statistics in the readable content, viewed August 7 2026. ,, https://www1.nyc.gov/site/rentguidelinesboard/resources/publications.page
- New York City Department of City Planning, planning level population page for current and future populations, which in this environment presents a message that the page has moved and that users will be redirected, but does not expose updated population numbers or tables in the readable extract, viewed August 7 2026. ,, https://www.nyc.gov/site/planning/planning-level/nyc-population/current-future-populations.page
- Federal Emergency Management Agency, flood maps page, describing how flood maps show areas at risk of flooding, defining high risk areas as those with at least a one percent annual chance of flooding and a one in four chance of flooding over a thirty year mortgage, and explaining that floods do not follow city limits or property lines, viewed August 7 2026. ,, https://www.fema.gov/flood-maps
- National Centers for Environmental Information, main site, stating that NCEI maintains one of the most significant archives of environmental data, archiving more than two hundred twenty nine terabytes of data each month from more than one hundred thirty observing platforms and providing access to climate and geophysical data through multiple platforms, viewed August 7 2026. ,, https://www.ncei.noaa.gov
- United States Census Bureau, Vintage 2025 population estimates as reported in public summaries, giving a New York City population of about 8,584,629 as of July 1 2025, a net change of negative 12,196 with net domestic migration of negative 113,718 and net international migration of positive 65,824, and a Manhattan, New York County, population of about 1,664,862, down 648 from the prior year and about 29,389 below the 2020 level, with the prior year July 2023 to July 2024 showing city growth of roughly 87,000 people, viewed August 7 2026. ,, https://www.census.gov/programs-surveys/popest.html
- New York City Comptroller, reports on the city economy and on domestic and international migration, noting persistently negative net domestic migration on the order of negative 42,300 households in 2024 and the historical dependence of population growth on international migration, viewed August 7 2026. ,, https://comptroller.nyc.gov/reports/nycs-economy-and-prospects/
- New York City Comptroller, comments on the preliminary budget for fiscal year 2027 and financial plan for fiscal years 2026 through 2030, projecting budget gaps of about 2.2 billion dollars in fiscal year 2026, 10.4 billion dollars in fiscal year 2027, 10.06 billion dollars in fiscal year 2028, 8.58 billion dollars in fiscal year 2029, and 6.96 billion dollars in fiscal year 2030, viewed August 7 2026. ,, https://comptroller.nyc.gov/reports/comments-on-new-york-citys-preliminary-budget-for-fiscal-year-2027-and-financial-plan-for-fiscal-years-2026-2030/
- Coverage of the inauguration of Mayor Zohran Mamdani on January 1 2026 following his victory over Andrew Cuomo and Curtis Sliwa in the November 4 2025 election, and of his affordability agenda including a rent freeze, free buses, universal childcare, and higher taxes on the wealthy and corporations that would require state approval, as reported by CNN, The New York Times, and other outlets, viewed August 7 2026. ,, https://www.nytimes.com/2026/01/01/nyregion/mamdani-inauguration-mayor.html
- Reporting on the New York City Rent Guidelines Board vote of June 25 2026 to freeze rents on stabilized apartments effective October 1 2026 and the subsequent lawsuit by property owners seeking to block it, as reported by the New York Daily News, Bloomberg, and others, viewed August 7 2026. ,, https://www.nydailynews.com/2026/07/22/landlords-sue-nyc-rent-guidelines-board-mamdanis-rent-freeze/
- Reporting on the removal of real estate and finance leaders from the Mayor’s Fund advisory board and on the response of the luxury real estate market during 2026, as reported by The Real Deal and the New York Post, viewed August 7 2026. ,, https://therealdeal.com/new-york/2026/08/07/mamdani-boots-real-estate-leaders-from-mayors-fund/