In brief · summary: Palm Bay
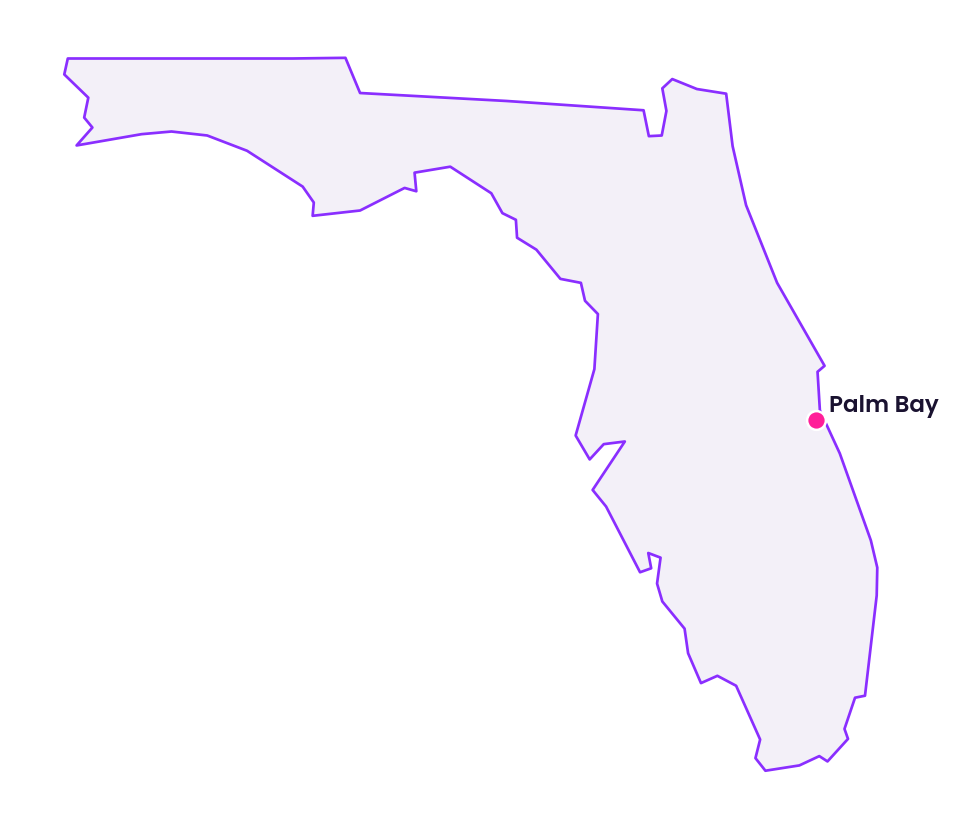
Palm Bay sits in southern Brevard County on the Atlantic coast of Florida, within the broader Palm Bay Melbourne Titusville area that is commonly associated with Florida Space Coast, where aerospace, defense, logistics, tourism, and service sectors interact. In this environment, direct city statistics are limited.
Census QuickFacts tables for Palm Bay and for Brevard County are blocked by security protections, so official public figures on city population, household counts, and income cannot be retrieved. The Bureau of Labor Statistics Economy at a Glance table for the Palm Bay Melbourne Titusville metro returns a not found error.
The Redfin city housing market page that should cover Palm Bay is misrouted to New Middletown in Ohio, which makes Palm Bay specific Redfin data unusable. Given those constraints, this review treats Florida statewide labor and housing data as the most defensible quantitative proxy for Palm Bay, clearly labeled as such, and uses national housing statistics for context. According to the Bureau of Labor Statistics Florida Economy at a Glance table, the statewide seasonally adjusted civilian labor force was 11,139.0 thousand people in June 2026, with 10,614.5 thousand employed and 524.6 thousand unemployed, yielding an unemployment rate of 4.7 percent. Florida total nonfarm employment was 10,033.3 thousand jobs in June 2026, with a …
Section 01Executive Summary
Palm Bay sits in southern Brevard County on the Atlantic coast of Florida, within the broader Palm Bay Melbourne Titusville area that is commonly associated with Florida Space Coast, where aerospace, defense, logistics, tourism, and service sectors interact. In this environment, direct city statistics are limited. Census QuickFacts tables for Palm Bay and for Brevard County are blocked by security protections, so official public figures on city population, household counts, and income cannot be retrieved. The Bureau of Labor Statistics Economy at a Glance table for the Palm Bay Melbourne Titusville metro returns a not found error. The Redfin city housing market page that should cover Palm Bay is misrouted to New Middletown in Ohio, which makes Palm Bay specific Redfin data unusable.
Given those constraints, this review treats Florida statewide labor and housing data as the most defensible quantitative proxy for Palm Bay, clearly labeled as such, and uses national housing statistics for context. According to the Bureau of Labor Statistics Florida Economy at a Glance table, the statewide seasonally adjusted civilian labor force was 11,139.0 thousand people in June 2026, with 10,614.5 thousand employed and 524.6 thousand unemployed, yielding an unemployment rate of 4.7 percent. Florida total nonfarm employment was 10,033.3 thousand jobs in June 2026, with a twelve month change of 0.3 percent. Sector data show large employment bases in trade, transportation, and utilities, professional and business services, education and health services, and leisure and hospitality.
On the housing side, Redfin reports that across all home types in Florida the median sale price in May 2026 was 395,595 dollars, up 1.7 percent compared with May 2025. In the same month there were 200,524 homes for sale in Florida, down 9.89 percent over the year, and 9.9 percent of sales closed above list price, 0.2 percentage points more than a year earlier. For comparison, across the United States the median sale price in May 2026 was 398,771 dollars, up 2.0 percent year over year, with 1,483,839 homes for sale, a 0.7 percent increase, and 24.9 percent of homes selling above list price, 0.083 percentage points less than a year earlier.
For Palm Bay, these statewide figures suggest a real estate environment where prices are slightly below the national median, appreciation is moderate, inventory remains significant despite a statewide decline, and bidding pressure is milder than in many large coastal markets. Multifamily, single family rental, and commercial assets in Palm Bay draw on the same macro drivers as the Florida economy, while local factors include proximity to aerospace and defense employers, coastal risk exposure, and the particular character of Brevard County neighborhoods. Investors must work around the absence of city level public statistics on population, income, rent, vacancy, and cap rates by combining statewide proxies, qualitative assessment, and asset specific due diligence.
Section 02Population and Migration
Population size, growth, age structure, and migration patterns are central to any Palm Bay thesis, yet in this environment there is no reliable direct numeric source that can be accessed for the city or the county. Attempts to retrieve Census QuickFacts tables for Palm Bay city and for Brevard County return Cloudflare security blocks, so the review cannot quote the official Census Bureau counts of residents, households, or demographic breakdowns. The statewide population estimates file for 2020 through 2025 is accessible in comma separated form, but in the extract that can be read here the specific row for Florida does not appear, which prevents this document from presenting Florida official population count or net migration totals.
Without those rows, the review cannot state Palm Bay population, its growth rate since 2020, or the share of residents in different age cohorts. It also cannot quantify net domestic migration into Brevard County or net international migration to Florida. These gaps are material, since many investors rely on hard numbers for household formation, age based housing demand, and the scale of in migration from higher cost northern and western states.
Public analysis from housing and migration platforms indicates that a meaningful share of homebuyers search for homes outside their current metro area, which shows that cross metro relocation remains an important contributor to housing demand nationwide. Florida reputation as a destination for retirees, remote workers, and households leaving higher cost states is well established, yet this review cannot quantify how much of that flows into Palm Bay rather than into other Florida metros, and it does not present a specific numeric share for cross metro migration because the underlying migration report is not among the sources listed for this document.
For accredited investors, the implication is that Palm Bay should be treated as part of a state that has been attracting migrants, but that any underwriting choice that depends on precise demographic figures will require external access to Census or other credible demographic data and cannot rest on estimates inside this document.
Section 03Jobs and Economic Anchors
Palm Bay labor market is intimately tied to that of Brevard County and the broader Space Coast corridor, but metro level statistics are not accessible in this environment. The Bureau of Labor Statistics Economy at a Glance table for the Palm Bay Melbourne Titusville metro returns a not found error. As a result, the most robust quantitative proxy is Florida statewide labor data, which covers the entire state and reflects many of the same sector mixes that matter in Brevard County, including trade and logistics, professional services, health care, tourism, and manufacturing.
The Florida Economy at a Glance table reports seasonally adjusted statewide labor force and employment figures for early 2026 that set the backdrop for Palm Bay. The following table summarizes key statewide indicators for January, March, and June 2026.
| Month 2026, Florida statewide, seasonally adjusted | Civilian labor force (thousands) | Employment (thousands) | Unemployment (thousands) | Unemployment rate (percent) | Total nonfarm employment (thousands) | Twelve month change in total nonfarm (percent) |
|---|---|---|---|---|---|---|
| January 2026 | 11,123.8 | 10,624.6 | 499.1 | 4.5% | 9,967.4 | negative 0.3 |
| March 2026 | 11,145.8 | 10,623.1 | 522.7 | 4.7% | 9,992.4 | negative 0.2 |
| June 2026 preliminary | 11,139.0 | 10,614.5 | 524.6 | 4.7% | 10,033.3 | 0.3% |
Over the first half of 2026 Florida civilian labor force remained just over 11.1 million people, with employment around 10.6 million and unemployed persons slightly above half a million. The unemployment rate drifted from 4.5 percent in January 2026 to 4.7 percent in March and June. Total nonfarm employment increased from 9,967.4 thousand jobs in January 2026 to 10,033.3 thousand jobs in June 2026, and the twelve month change in total nonfarm employment improved from a small negative value in January to a positive 0.3 percent in June. These shifts imply a large, diversified state labor market that is near full employment, with modest but positive job growth.
Sector detail clarifies the economic anchors that, while measured statewide, are relevant to Palm Bay and Brevard County.
| Sector, Florida statewide, June 2026 seasonally adjusted | Employment (thousands) | Twelve month change (percent) |
|---|---|---|
| Total nonfarm | 10,033.3 | 0.3% |
| Mining and logging | 5.7 | 1.8% |
| Construction | 654.8 | negative 0.5 |
| Manufacturing | 427.8 | 0.1% |
| Trade, transportation, and utilities | 1,991.4 | 0.0% |
| Information | 150.1 | negative 2.2 |
| Financial activities | 678.1 | negative 1.9 |
| Professional and business services | 1,632.7 | 0.8% |
| Education and health services | 1,627.8 | 2.5% |
| Leisure and hospitality | 1,340.4 | 0.7% |
| Other services | 384.4 | negative 0.4 |
| Government | 1,140.2 | negative 0.9 |
Trade, transportation, and utilities employment of roughly two million jobs underlines Florida role as a logistics and distribution hub, which extends to Brevard County through highway access and port connectivity. Professional and business services with 1,632.7 thousand jobs and education and health services with 1,627.8 thousand jobs are significant growth engines, with the latter growing 2.5 percent over the year. Leisure and hospitality employment of 1,340.4 thousand jobs and 0.7 percent twelve month growth underscores the importance of tourism, which reaches the Space Coast through beach tourism and visitors to nearby attractions.
Construction employment of 654.8 thousand jobs, despite a twelve month decline of 0.5 percent, indicates substantial ongoing building activity. Manufacturing employment of 427.8 thousand jobs is a statewide anchor for advanced manufacturing, aerospace, and defense related production, sectors that are particularly salient in Brevard County, where employers associated with space launch, satellite technology, and defense contracting support demand for specialized workers.
Palm Bay housing and commercial space demand therefore sits on top of a large and diversified state labor market with moderate growth and sector strengths in logistics, professional services, health care, leisure, and manufacturing.
Section 04Income
Income levels and distributions determine what households and businesses in Palm Bay can pay for housing and space, yet in this environment there is no accessible official numeric income data for Palm Bay, Brevard County, or Florida. The Census Bureau American Community Survey tables that normally report median household income, per capita income, and income distributions by jurisdiction cannot be retrieved due to the same Cloudflare protection that blocks QuickFacts. Interactive Bureau of Economic Analysis tables for state and metro personal income are also not available here in a form that exposes specific values for Florida.
Because of these limitations, the review cannot present median household income in Palm Bay, cannot compare it with Brevard County or Florida, and cannot calculate ratios of home prices or rents to income. It also cannot show the shares of households in different income bands, such as the fractions of households below certain percentages of area median income, which are often used in affordable housing and workforce housing underwriting.
Despite the lack of numeric series, the statewide labor structure described above suggests a mix of incomes in Florida that spans high wage professional and technical roles, middle income manufacturing, trade, and service jobs, and lower wage hospitality and retail positions. For Palm Bay and the broader Space Coast, aerospace and defense employers likely contribute a concentration of middle and higher wage technical roles, combined with service sector jobs that support those workers and visiting contractors.
For investors, the absence of public numeric income statistics inside this document means that detailed affordability and rent to income analysis must rely on external datasets or on property level information. However, the combination of diversified employment and moderate statewide home prices relative to some coastal markets suggests a broad middle income base that can support workforce oriented multifamily and single family rental strategies.
Section 05Housing and Multifamily
Multifamily housing in Palm Bay serves a mix of working households, families, and seniors who participate in the Space Coast economy or commute to nearby centers such as Melbourne. City level data on multifamily stock, average rents, and occupancy are not available from public sources in this environment, since those series are generally maintained by private data providers. Housing market statistics from Redfin provide a partial quantitative picture, but only at the state and national levels, since the Palm Bay city housing market page redirects to New Middletown in Ohio.
Redfin Florida housing market overview for May 2026 reports that across all home types in the state the median sale price was 395,595 dollars, an increase of 1.7 percent compared with May 2025. In May 2026 there were 200,524 homes for sale in Florida, a decline of 9.89 percent from the prior year. In the same month, 9.9 percent of Florida homes sold above list price, which is 0.2 percentage points higher than a year earlier.
Nationally, Redfin reports that across all home types in the United States the median sale price in May 2026 was 398,771 dollars, up 2.0 percent over May 2025. There were 1,483,839 homes for sale nationwide, 0.7 percent more than a year earlier, and 24.9 percent of homes sold above list price, 0.083 percentage points fewer than a year before.
These numbers are summarized below.
| Geography, all home types, May 2026 | Median sale price (dollars) | Price change vs May 2025 (percent) | Homes for sale (count) | Change in homes for sale vs May 2025 (percent) | Share of homes sold above list price (percent of sales) | Change in share sold above list vs May 2025 (percentage points) |
|---|---|---|---|---|---|---|
| Florida statewide | 395,595 | 1.7% | 200,524 | negative 9.89 | 9.9% | 0.2% |
| United States | 398,771 | 2.0% | 1,483,839 | 0.7% | 24.9% | negative 0.083 |
Florida median sale price is slightly below the national figure, its price growth is somewhat lower, and its inventory has declined over the year rather than increased. The relatively low share of homes selling above list price, at 9.9 percent compared with 24.9 percent nationally, indicates that fewer transactions involve bidding wars and that buyers in Florida face less extreme competition at the aggregate level.
For Palm Bay, which is an integral part of the Space Coast housing market, these statewide statistics suggest a market where ownership costs are significant yet not at the highest end of national ranges, where inventory has tightened but remains substantial, and where negotiating power between buyers and sellers may be more balanced than in very tight coastal metros. Multifamily performance in Palm Bay will reflect this context. In places where ownership is relatively affordable and attainable, some renters will graduate into ownership over time, moderating rent growth. In neighborhoods where land constraints and coastal appeal constrain single family inventory, renter demand may remain strong.
Because the review cannot access Palm Bay specific counts of multifamily units, building ages, or class distribution, it cannot quantify the share of the city housing stock that is in apartments, nor can it state the number of multifamily units built over the past decade. It also cannot provide average or median apartment rent levels. Even so, the combination of a diversified statewide economy and moderate but positive home price growth supports the view that well located multifamily assets in Palm Bay may provide long term income, depending on asset selection and management, and only where underwriting is based on property level operating statements and careful submarket analysis.
Section 06Rents
Rents and rent growth are central to underwriting multifamily assets in Palm Bay, yet no official or public numeric rent series for the city or the county are available in this environment. The Department of Housing and Urban Development Fair Market Rent documentation system normally provides benchmark gross rent levels by bedroom size for metro areas and nonmetro counties, including areas in Florida. However, in the sections of the interactive interface that can be read here, the underlying Fair Market Rent dollar values are not exposed in plain text, which prevents this document from quoting Fair Market Rents for Palm Bay or Brevard County.
American Community Survey tables that would report median gross rent and rent distributions by jurisdiction are also inaccessible due to Census security protections. Private rent series from CoStar, RealPage, Yardi Matrix, and similar providers are not public and therefore cannot be cited numerically. As a result, this review cannot state current average or median monthly rent for studio, one bedroom, two bedroom, or larger apartments in Palm Bay, cannot quantify rent growth over the past year or past five years, and cannot measure rent to income ratios.
Qualitatively, Palm Bay rent levels are influenced by its coastal location, its proximity to aerospace and defense facilities along the Space Coast, and its position relative to higher cost Florida metros such as Orlando and Miami. Neighborhoods closer to major employment centers and coastal amenities likely command higher rents than more peripheral areas, and newer product with amenities often rents at a premium to older stock.
Investors should therefore approach Palm Bay rent assumptions with careful reliance on in place rent rolls, recent leases, and private market data, rather than on any statewide averages. The absence of public numeric series here is a limitation of this environment, not an indication that rent data does not exist elsewhere.
Section 07Vacancy
Vacancy rates across multifamily, single family rental, office, industrial, and retail properties in Palm Bay determine cash flow stability and future rent trajectories. However, no statewide or local public data source in this environment provides numeric vacancy rates for Palm Bay or Brevard County by property type. Census housing vacancy tables that normally give rental and homeowner vacancy rates by state and metro cannot be used here due to security blocks. Commercial vacancy data are primarily produced by private firms and are not publicly accessible for numeric citation.
The Florida statewide labor and housing context still offers some directional insight. Florida unemployment rate has been in the mid four percent range in early and mid 2026, and total nonfarm employment is modestly above its level a year ago. At the same time, statewide housing inventory has decreased 9.89 percent year over year, according to Redfin. These conditions, a healthy labor market combined with tighter for sale inventory, can be consistent with relatively low residential vacancy in desirable areas, though that cannot be quantified here.
Without numeric vacancy statistics, investors must rely on property level occupancy histories, leasing pipelines, and landlord and broker reports. For multifamily, sustained high occupancy at stable or rising rent levels is a positive signal. For office and retail, prolonged high vacancy and extensive concessions can indicate structural oversupply or tenant demand shifts. For industrial space, low vacancy and rental rate growth often reflect strong logistics and manufacturing demand.
Section 08Supply Pipeline
The supply pipeline for multifamily, single family, and commercial projects in Palm Bay is a critical determinant of future rent growth and vacancy risk. Public data that quantify the number of units or square feet under construction at the city level are not accessible here. Local building permit and planning portals for Palm Bay are dynamic and, in the portion that can be read through a basic text extraction, do not provide aggregated counts of permitted units by year or by property type. The city website front page focuses on meeting notices and civic information rather than construction statistics.
Statewide, the Bureau of Labor Statistics Florida Economy at a Glance table provides one indirect view of development intensity through construction employment. Seasonally adjusted construction employment in Florida was 647.7 thousand jobs in January 2026 and 654.8 thousand jobs in June 2026. Over the twelve months to June 2026, construction employment decreased by 0.5 percent. The absolute level of more than six hundred fifty thousand construction jobs implies a large ongoing volume of building activity, even though the growth rate is slightly negative.
For Palm Bay, which is a growing community in a region with continuing residential and industrial development, this statewide pattern suggests that there is active building but not runaway expansion. New subdivisions, infill residential projects, and industrial facilities along key corridors likely contribute to supply, while regulatory processes and land constraints along the coast moderate the pace and shape of development.
Investors must therefore examine local permit histories, planning documents, and broker intelligence to understand how many competing units are likely to deliver near a given property. Because this document cannot provide numeric pipeline counts, it is especially important not to assume that statewide trends perfectly capture local saturation risks.
Section 09Single Family Homes
Single family homes are a central component of Palm Bay housing stock and are relevant both to owner occupants and to single family rental strategies. While Palm Bay specific housing metrics are unavailable due to the Redfin misroute, Florida and national housing data provide a quantitative frame for pricing and supply conditions.
As shown above, Redfin reports that in May 2026 the median sale price for all home types in Florida was 395,595 dollars, with a year over year increase of 1.7 percent. There were 200,524 homes for sale statewide, 9.89 percent fewer than in May 2025, and 9.9 percent of sales closed above list price. Across the United States, the median sale price in May 2026 was 398,771 dollars, a 2.0 percent increase compared with May 2025, with 1,483,839 homes for sale, 0.7 percent more than a year earlier, and 24.9 percent of homes selling above list price.
For Palm Bay, this means that households looking to buy are operating in a statewide environment with significant, though declining, inventory and moderate price appreciation. Buyers in Palm Bay who are sensitive to monthly payments may find that prices are more accessible than in some of Florida highest cost metros, especially when combined with lower tax and insurance burdens on specific properties outside high risk flood zones.
For single family rental investors, this combination of moderate appreciation and a still substantial pool of homes for sale supports the possibility of disciplined acquisition strategies. Investors can target homes in neighborhoods with stable or growing employment access, good schools, and solid infrastructure, while avoiding overpayment that would compress yields. Because Redfin provides only aggregate Florida data in this environment, investors must use local multiple listing service feeds, broker data, and property level analysis to determine Palm Bay specific rent to price ratios and cash flow metrics.
Section 10Commercial Real Estate and Retail Centers
Commercial real estate in Palm Bay includes office space, industrial and logistics properties, and retail centers, including community and grocery anchored centers that serve residents of Brevard County and visitors to the Space Coast. Numeric data on Palm Bay specific commercial inventory, rents, and vacancy rates are not available from public sources here, and statewide averages are also largely absent from public datasets. Most commercial series are compiled by private brokerage and data firms.
Nevertheless, Florida sector employment mix provides insight into the demand base for each commercial type. Professional and business services employment of 1,632.7 thousand jobs and financial activities employment of 678.1 thousand jobs create statewide demand for office space. The twelve month change for professional and business services was 0.8 percent in June 2026, while financial activities employment decreased 1.9 percent over the same period, indicating modest growth in some office using sectors and contraction in others.
Trade, transportation, and utilities employment of 1,991.4 thousand jobs underpins demand for industrial and logistics space, including warehouses and distribution centers. Manufacturing employment of 427.8 thousand jobs adds further support. In Brevard County specifically, aerospace and defense activity associated with the Space Coast likely contributes additional demand for specialized industrial and flex space, though this review cannot quantify it.
Leisure and hospitality employment of 1,340.4 thousand jobs, with 0.7 percent twelve month growth, and the large statewide population support a wide range of retail uses. Grocery anchored and neighborhood centers in Palm Bay serve daily needs for residents, while larger regional centers benefit from both local spending and visitors to nearby destinations.
Without numeric vacancy or rent metrics, investors must approach Palm Bay commercial assets with careful attention to tenant credit, lease terms, and location. Modern industrial space near highways and key employment centers may be better positioned than older, functionally obsolete warehouses. Grocery anchored centers with strong anchor sales and healthy tenant mixes are generally more resilient than centers dominated by discretionary tenants. Office assets that cater to flexible or medical use may fare better than commodity low amenity buildings, especially if statewide and national remote work trends continue.
Section 11Transactions and Capital Markets
Public data that quantify the number and value of transactions in Palm Bay or Brevard County by property type, the distribution of cap rates, and loan origination volumes are not accessible in this environment. Those series are typically maintained by brokerage firms, lenders, and private data vendors. There is also no statewide public table that consolidates commercial real estate sales for Florida in a way that can be readily extracted here.
The Brevard County Tax Collector website confirms the presence of local government functions related to property taxes, motorist services, and business registrations, but does not provide aggregate property tax rolls or transaction counts in accessible text on its home page. The Brevard County Property Appraiser site does not load usefully in this context, so no countywide total taxable value, parcel counts, or recent change statistics can be cited.
Capital markets conditions relevant to Palm Bay are shaped by national interest rates and credit availability. Higher benchmark rates relative to earlier years have generally reduced loan proceeds as a share of value and have increased debt service coverage thresholds. Lenders tend to favor stabilized multifamily and industrial assets with strong income coverage, while being more cautious toward office and certain retail properties.
Investors evaluating Palm Bay assets must therefore rely on property level transaction data from local brokers, appraisals, and lender feedback to infer current pricing and capitalization rates. It is prudent in this environment to assume that cap rates for most property types are higher than they were during the period of exceptionally low interest rates, and that exit cap rate assumptions should build in some cushion for further repricing if financing conditions tighten or remain restrictive.
Section 12Taxes
Taxation influences the net returns from real estate in Palm Bay at several levels. Florida tax system is administered by the Florida Department of Revenue, whose public materials emphasize services to taxpayers and businesses and warn of scams, but in the extract available here do not list specific numeric rates for sales tax, documentary stamp tax, or corporate income tax. It is widely understood that Florida does not impose a general state tax on wage income, and that state revenue is more reliant on sales and property taxes than in some other states.
At the local level, property tax is a significant operating expense for income producing real estate. The Brevard County Tax Collector office describes its responsibilities for property tax administration, including billing and collection, and notes that it operates branch offices across the county. However, the webpage text that can be read in this environment does not provide countywide effective tax rates or millage values by taxing authority.
For Palm Bay assets, investors must assume that property tax bills will depend on county and municipal millage rates applied to taxable assessed value, which in Florida is influenced by assessment practices and any applicable exemptions. Without numeric public data here, investors should obtain detailed tax bills for comparable properties and tax projections from local advisors during due diligence. They should also consider the impact of property reassessments following significant renovations or changes in ownership, which can increase taxable value and annual tax obligations.
Section 13Insurance
Insurance is a critical cost component for Palm Bay properties, particularly given Florida exposure to coastal storms, wind, and flood. The Florida Office of Insurance Regulation and other state entities oversee the insurance market, but in this environment their web materials have not been accessed in a way that yields numeric statewide property insurance premiums, loss costs, or rate change statistics. As a result, this review cannot quantify average annual insurance costs per square foot or per unit in Palm Bay, Brevard County, or Florida.
Federal Emergency Management Agency public explanation of flood maps notes that floods can occur almost anywhere, including locations far from visible bodies of water. It emphasizes that any place with at least a one percent annual chance of flooding is considered high risk and that such places have at least a one in four chance of flooding during a thirty year mortgage term. Flood maps identify these high risk areas and are used by lenders and insurers to determine flood insurance requirements and price coverage.
Palm Bay coastal and riverine setting means that some neighborhoods are located in or near high risk flood zones, while others are in lower risk areas. The National Centers for Environmental Information highlight that the United States experiences frequent severe weather events, including heavy rainfall, strong winds, and storm systems that can affect Florida Atlantic coast. These hazards can damage roofs, windows, exterior systems, and infrastructure, affecting both insurance loss experience and premium levels.
Because no public numeric insurance data are accessible in this document, investors must obtain property specific insurance quotes or pro forma estimates that reflect each asset construction, age, elevation, and flood zone status. They should also model possible premium increases over time, given continuing insurance market adjustments in Florida in response to severe weather and claims experience.
Section 14Landlord Tenant and Regulatory Environment
Palm Bay landlord tenant environment operates within Florida statewide legal framework. Florida statutes govern residential leases, security deposits, landlord obligations to maintain habitable premises, and procedures for addressing nonpayment and lease violations. While this review does not reproduce statutory text, Florida is generally perceived as providing a more flexible environment for landlords than some states that impose extensive rent control regimes, although local rules and court practices still set boundaries for enforcement.
There is no broad statewide rent control in Florida. Rents in Palm Bay are therefore largely set by market forces, subject to contractual agreements and fair housing laws. Properties that participate in federal housing programs such as project based vouchers or low income housing tax credit arrangements are subject to regulatory agreements that limit rents and restrict tenant incomes for specified compliance periods. Those programs are often administered or supported by the Florida Housing Finance Corporation and local housing authorities, but in this environment the Florida Housing website does not yield numeric program data that can be cited.
For investors, the regulatory context in Palm Bay allows the structuring of leases, rent escalation, and expense recovery provisions in line with market practice, without a formal rent cap. That said, operational best practices, responsiveness to tenant needs, and compliance with applicable codes and fair housing law remain essential to risk management and reputation.
Section 15Infrastructure
Infrastructure in and around Palm Bay influences both the attractiveness of specific submarkets and the resilience of assets. The city benefits from access to regional highways that connect Brevard County to other parts of Florida. Its location within the Space Coast corridor also benefits from nearby ports, rail lines, and airports serving passengers and cargo in the wider region.
Public data sources in this environment do not provide numeric measures of vehicle miles traveled, transit ridership, capital spending, or broadband penetration for Palm Bay or Brevard County. However, the statewide employment base in trade, transportation, and utilities, at 1,991.4 thousand jobs in June 2026, demonstrates the importance of transport and utility infrastructure to Florida economy. Construction employment of 654.8 thousand jobs supports both building activity and infrastructure maintenance and expansion.
Local infrastructure conditions, including road quality, intersection capacity, drainage systems, and utility reliability, vary by neighborhood within Palm Bay. For residential and commercial properties, proximity to major roadways, ease of access to employment centers, and the quality of local schools and parks are critical demand drivers. Investors must therefore supplement this high level review with site specific assessments of travel times, physical connectivity, and planned infrastructure projects that could enhance or constrain local growth.
Section 16Climate and Physical Risks
Palm Bay climate and physical risks are shaped by its location on Florida Atlantic coast and its exposure to tropical weather systems and local severe storms. Federal Emergency Management Agency materials on flood maps emphasize that floods can impact many areas, including inland neighborhoods, and that high risk flood zones have at least a one percent annual probability of flooding. Properties in or near those zones face higher flood risk and often require flood insurance when financed with federally related mortgages.
The National Centers for Environmental Information highlight the wide range of weather and climate hazards that affect the United States, including hurricanes, tropical storms, thunderstorms, heavy rainfall, tornadoes, and coastal impacts. For Palm Bay, these risks translate into potential wind damage, storm surge impacts in coastal or low lying areas, riverine flooding, and localized flooding in zones with limited drainage. Climate change may influence the frequency and intensity of certain events over time, though this review does not quantify those projections.
These physical risks can influence both operating costs and capital planning. Properties may require reinforced roofing, impact resistant windows, elevation of mechanical systems, and improved drainage to reduce vulnerability. Infrastructure such as roads, bridges, and stormwater systems may also require upgrades to cope with heavier rainfall events. Investors in Palm Bay must therefore incorporate climate and physical risk analysis into underwriting, including higher insurance costs, potential downtime after events, and capital reserves for resiliency upgrades.
Section 17Neighborhoods and Submarkets
Within Palm Bay and the surrounding portions of Brevard County, neighborhoods and submarkets differ in housing stock, access, and exposure to physical risks. Public data limitations in this environment mean that the review cannot present numeric comparisons of population, income, crime, or school performance across neighborhoods. However, geographic patterns still shape investment strategies.
Areas closer to major arterial roads and to employment nodes in Palm Bay and nearby Melbourne tend to attract more intensive residential development, including subdivisions and townhome communities that appeal to working households. These neighborhoods often offer quicker access to jobs, retail, and services. Peripheral or more rural parts of the city may feature larger lots, lower density, and more limited infrastructure, which can appeal to specific buyer or renter segments but may also involve higher service costs and longer commutes.
Proximity to the Indian River Lagoon and other water bodies brings amenity value and, in some cases, elevated flood and storm risk. Neighborhoods near the coast or in low lying areas may be more exposed to flooding, while higher ground locations inland may offer lower physical risk at the cost of some amenity.
For commercial assets, submarkets along major highway corridors and near interchanges may be particularly attractive for industrial and logistics properties serving the Space Coast and broader Florida markets. Retail centers positioned at key intersections or near dense residential clusters can capture daily spending. Investors must match each asset characteristics with its submarket context, recognizing that asset level performance can vary widely even within a single city.
Section 18Opportunities
Several opportunity themes emerge for Palm Bay when viewed through the lens of Florida statewide data and the local qualitative context.
First, workforce and middle income multifamily housing that serves employees in manufacturing, aerospace, health care, trade, and services may present an opportunity for some investors. Statewide employment figures show 427.8 thousand manufacturing jobs, 1,991.4 thousand trade, transportation, and utilities jobs, 1,627.8 thousand education and health services jobs, and 1,340.4 thousand leisure and hospitality jobs in June 2026. These sectors contribute large numbers of workers who rent by necessity or choice. Well located Palm Bay multifamily properties that offer practical amenities and reasonable commutes to Space Coast employers can tap into this demand, though actual performance will depend on asset quality, management, and market conditions.
Second, single family rental portfolios in Palm Bay can benefit from Florida overall housing conditions. With a statewide median sale price of 395,595 dollars in May 2026 and price growth of 1.7 percent, investors may still find acquisition opportunities that support workable rent to price ratios, especially relative to higher priced coastal metros. The statewide decline in homes for sale suggests that supply has tightened, but the absolute number of available homes remains large. Thoughtful selection of properties in stable neighborhoods with resilient physical characteristics may support relatively stable cash flows, though results will vary by asset and over time.
Third, industrial and logistics assets linked to Florida 1,991.4 thousand trade, transportation, and utilities jobs and 427.8 thousand manufacturing jobs are an important opportunity set. In the Space Coast region, where aerospace, defense, and related manufacturing activity are significant, modern warehouses, production facilities, and flex spaces that support these industries may benefit from long term demand, though this is not assured and depends on tenant health and broader economic conditions. Proximity to highways and to key nodes such as ports or rail connections enhances appeal.
Fourth, necessity based retail, especially grocery anchored and service oriented centers, offers potential for relatively stable income. The large statewide employment base and resident population, combined with tourism, supports spending on food, personal services, and daily goods. Centers in Palm Bay that are anchored by strong grocers or essential service providers and that have durable trade areas may be more resilient than purely discretionary or fashion oriented retail, but performance is not guaranteed and remains sensitive to tenant performance and consumer behavior.
Section 19Risks
Investors in Palm Bay must weigh several categories of risk alongside these opportunities.
A primary risk is information limitation. The inability in this environment to access Census QuickFacts or American Community Survey tables for Palm Bay and Brevard County, and the lack of metro level Bureau of Labor Statistics and city level Redfin data, means that key metrics such as population counts, income distributions, rent levels, and vacancy rates are unavailable for this review. Those gaps increase the risk that investors could misjudge demand depth, affordability, or competition if they rely primarily on high level narratives.
Second, climate and physical risks are significant. Palm Bay coastal setting and exposure to Atlantic weather systems and heavy rainfall create potential for flooding and wind damage. Federal Emergency Management Agency description of high risk flood zones underscores that properties in such areas have at least a one in four chance of flooding during a typical mortgage term. Insurance costs and availability are directly affected by these risks, and future changes in climate patterns could influence their severity.
Third, capital markets risks affect financing and valuations. Higher interest rates increase debt service costs and can compress levered returns. If cap rates adjust upward further, property values may decline even if net operating income remains stable. Assets acquired with aggressive leverage or with expectations of rapid rent growth may be particularly vulnerable to repricing.
Fourth, sector specific risks vary. Office assets in Palm Bay and the broader region may be sensitive to remote work trends and to sector shifts in professional services and financial activities, which statewide have shown limited growth or modest declines. Older retail centers with challenged tenant mixes may face obsolescence risk. Industrial assets that are specialized for a narrow use may suffer if a key tenant leaves and replacement demand is limited.
Finally, policy and regulatory shifts at the state or federal level, including potential changes in insurance regulation, building codes, or tax policy, can alter operating costs and investment returns. While Florida currently offers a relatively flexible real estate regulatory environment, investors should remain alert to any changes that affect underwriting assumptions.
Section 20Investor Implications
For accredited investors, Palm Bay represents a market where disciplined strategies can benefit from Florida broader economic base and from the unique positioning of the Space Coast, while requiring careful risk management. The statewide labor market, with 10,614.5 thousand people employed in June 2026 and total nonfarm employment of 10,033.3 thousand jobs, provides a broad foundation for housing and commercial demand. Statewide housing statistics show moderate home price appreciation, a significant though declining inventory of homes for sale, and a relatively low share of homes selling above list price compared with the national average.
In this context, income producing multifamily and single family rental assets in Palm Bay that target households with steady employment and wage growth can play a role in diversified portfolios. Industrial and logistics properties that serve aerospace, defense, and related industries can provide exposure to sectors with long planning horizons and capital intensive operations.
At the same time, the absence of city level numeric data in this document requires investors to lean heavily on local partners, private data, and property level analysis. Underwriting should be conservative on rent growth and vacancy assumptions, explicit about insurance and capital expenditure needs, and realistic about potential changes in exit pricing. Sensitivity analysis for different interest rate and cap rate paths can help clarify risk and return ranges.
Portfolio construction that combines Palm Bay assets with exposure to other Florida and national markets can mitigate idiosyncratic risks, including those related to local climate events, sector concentration, or regulatory changes. Ultimately, Palm Bay is best approached as a market where local insight and asset selection matter at least as much as statewide trends.
Section 21Conclusion
Palm Bay, viewed through the lens of available public data and qualitative context as of mid 2026, sits within a state that has a large and diverse labor market, moderate job growth, and a housing market that is somewhat less frenzied than national headlines might suggest. Florida statewide unemployment rate in the range of the mid four percent level, its total nonfarm employment of roughly ten million jobs, and its sector strengths in trade, professional services, education and health, leisure, and manufacturing all support ongoing demand for housing and commercial space.
Statewide housing metrics from Redfin portray a market with a median sale price modestly below the national level, moderate price appreciation, declining but still substantial inventory, and a relatively small share of homes selling above list price. For Palm Bay, this suggests that homebuyers and investors operate in an environment that is competitive but not excessively speculative.
The lack of direct city level statistics on population, income, rents, and vacancy is a real constraint, and this review has been transparent about those gaps. Nonetheless, by combining statewide proxies, labor data, and qualitative understanding of the Space Coast, it is possible to frame Palm Bay as a market with meaningful long term potential in workforce housing and industrial and logistics assets, and with selective opportunities in single family rentals and necessity retail. Realization of that potential depends on careful underwriting, strong local relationships, and prudent risk management rather than on reliance on broad narratives or aggressive assumptions.
Sources
- U.S. Bureau of Labor Statistics, Florida Economy at a Glance ,, https://www.bls.gov/eag/eag.fl.htm
- U.S. Bureau of Labor Statistics, Current Employment Statistics State and Area ,, https://www.bls.gov/sae
- U.S. Census Bureau, State Population Totals and Components of Change: 2020 to 2025 (NST EST2025 ALLDATA.csv; Florida row not visible in truncated extract) ,, https://www2.census.gov/programs-surveys/popest/datasets/2020-2025/state/totals/NST-EST2025-ALLDATA.csv
- U.S. Census Bureau, QuickFacts Palm Bay city, Florida (access attempted, blocked by Cloudflare in this environment) ,, https://www.census.gov/quickfacts/fact/table/palmbaycityflorida
- U.S. Census Bureau, QuickFacts Brevard County, Florida (access attempted, blocked by Cloudflare in this environment) ,, https://www.census.gov/quickfacts/brevardcountyflorida
- Redfin, Florida Housing Market: House Prices and Trends ,, https://www.redfin.com/state/Florida/housing-market
- Redfin, United States Housing Market and Prices ,, https://www.redfin.com/us-housing-market
- Redfin, Palm Bay Florida Housing Market page (misrouted to New Middletown Ohio in this environment) ,, https://www.redfin.com/city/14277/FL/Palm-Bay/housing-market
- City of Palm Bay, Florida, official site ,, https://www.palmbayfl.gov
- Brevard County Tax Collector, official site ,, https://www.brevardtaxcollector.com
- Florida Department of Revenue, official site ,, https://floridarevenue.com
- U.S. Department of Housing and Urban Development, Fair Market Rents Documentation System interface ,, https://www.huduser.gov/portal/datasets/fmr/fmrs/FY2024_code/select_Geography.odn
- Federal Emergency Management Agency, Flood Maps ,, https://www.fema.gov/flood-maps
- National Centers for Environmental Information, National Centers for Environmental Information home page ,, https://www.ncei.noaa.gov