In brief · summary: Richmond
Richmond, Virginia sits at the center of a diverse state capital economy with a broad employment base in government, finance, professional services, logistics, education, and health care, which provides a stable platform for residential and commercial real estate demand.
The Richmond metropolitan statistical area had a population of about 1.35 million in 2023, the fourth most populous metro in Virginia and roughly the forty fourth largest in the United States, with metropolitan gross domestic product of about 116,959.541 million dollars in 2023 in current dollars, according to the United States Census Bureau and the United States Bureau of Economic Analysis.
Labor market data from the United States Bureau of Labor Statistics show a civilian labor force of 717,400 in June 2026, an unemployment rate of 3.8 percent, and total nonfarm payroll employment of 732,800 jobs, down about 0.7 percent over the year, all not seasonally adjusted, with data extracted August 12 2026. In the city of Richmond, Census Bureau figures for the 2019 through 2023 period show a median household income of 62,671 dollars, a median value of owner occupied homes of 328,100 dollars, a median gross rent of 1,314 dollars per month, and a renter majority, with only 43.5 percent of occupied units owner occupied. On the transaction side, …
Section 01Executive Summary
Richmond, Virginia sits at the center of a diverse state capital economy with a broad employment base in government, finance, professional services, logistics, education, and health care, which provides a stable platform for residential and commercial real estate demand.
The Richmond metropolitan statistical area had a population of about 1.35 million in 2023, the fourth most populous metro in Virginia and roughly the forty fourth largest in the United States, with metropolitan gross domestic product of about 116,959.541 million dollars in 2023 in current dollars, according to the United States Census Bureau and the United States Bureau of Economic Analysis. Labor market data from the United States Bureau of Labor Statistics show a civilian labor force of 717,400 in June 2026, an unemployment rate of 3.8 percent, and total nonfarm payroll employment of 732,800 jobs, down about 0.7 percent over the year, all not seasonally adjusted, with data extracted August 12 2026.
In the city of Richmond, Census Bureau figures for the 2019 through 2023 period show a median household income of 62,671 dollars, a median value of owner occupied homes of 328,100 dollars, a median gross rent of 1,314 dollars per month, and a renter majority, with only 43.5 percent of occupied units owner occupied. On the transaction side, Redfin reports a median home sale price of about 429,766 dollars over the three months ending June 2026, up 0.2 percent year over year, with homes selling in about 12 days.
For rental housing, Yardi Matrix reports an average advertised asking rent of 1,619 dollars per month in early 2026, up 3.6 percent year over year, one of the stronger paces nationally, with stabilized occupancy near 94.8 percent, while commercial data show Richmond office vacancy in the low teens near 11 to 13 percent and industrial vacancy tight near 5 percent. For accredited investors, the picture is of a stable, diversified secondary market with reasonable pricing relative to income, supported by a broad employer base, offset by modest recent job softening and asset specific risks that require careful underwriting.
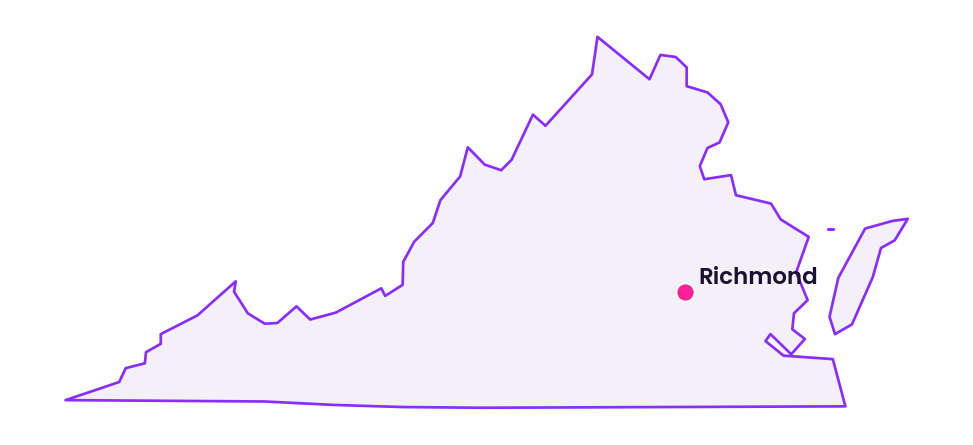
Section 02Population and Migration
Richmond functions as the core city of a multi county region that includes substantial suburban populations in counties such as Henrico and Chesterfield, and the labor market data used later in this review are reported for the metropolitan statistical area that aggregates these jurisdictions.
United States Census Bureau data place the Richmond metro population at about 1.35 million in 2023, up from 1,314,434 in the 2020 census, making it the fourth largest metro in Virginia and roughly the forty fourth largest in the country. The city of Richmond had about 227,595 residents on the American Community Survey five year 2019 through 2023 basis, with a more recent estimate near 237,000 for 2025, indicating modest ongoing growth, and a median age of about 34.5 years.
| Population metric | Geography and scope | Value | Source and date |
|---|---|---|---|
| Metro population | Richmond metro 2023 | about 1.35 million | US Census Bureau 2023 estimate |
| City population | Richmond city ACS 5 year 2019 through 2023 | about 227,595 persons | US Census Bureau ACS 5 year 2023 |
| City population, recent estimate | Richmond city 2025 | about 237,000 persons | Weldon Cooper Center and Census estimate |
| City median age | Richmond city ACS 5 year 2019 through 2023 | 34.5 years | US Census Bureau ACS 5 year 2023 |
The city population held roughly steady across the 2019 through 2023 ACS period and has edged higher on more recent estimates, consistent with Richmond role as the job and institutional hub of a growing multi county region. Migration into the metro comes largely from elsewhere in Virginia and the Mid Atlantic, with the region generally benefiting from its relative affordability compared with Washington and coastal markets. Investors should understand that population and household formation are primary long run drivers of demand for both rental and for sale housing, and Richmond steady growth supports that demand base.
Section 03Jobs and Economic Anchors
All quantitative labor market figures in this section come from the United States Bureau of Labor Statistics Economy at a Glance table for the Richmond Virginia metropolitan statistical area, not seasonally adjusted, with data extracted August 12 2026.
The first half of 2026 shows a stable labor market with a civilian labor force a little above 715,000 people and an unemployment rate in the mid three percent range, as summarized below.
| Month 2026 | Labor force thousand | Employment thousand | Unemployment thousand | Unemployment rate % | Total nonfarm jobs thousand |
|---|---|---|---|---|---|
| January 2026 | 717.8 | 690.4 | 27.4 | 3.8% | 719.1 |
| February 2026 | 714.8 | 687.3 | 27.5 | 3.8% | 717.6 |
| March 2026 | 717.2 | 690.3 | 26.9 | 3.7% | 721.6 |
| April 2026 | 716.0 | 691.5 | 24.5 | 3.4% | 724.7 |
| May 2026 | 715.7 | 690.3 | 25.4 | 3.5% | 726.1 |
| June 2026 preliminary | 717.4 | 690.0 | 27.4 | 3.8% | 732.8 |
These figures, confirmed against the Bureau of Labor Statistics source, indicate that the Richmond regional labor market is close to full employment, with unemployment rates below levels typically associated with slack and with total nonfarm payroll employment rising from about 719,000 jobs in January to about 733,000 jobs in June. Over the year, however, total nonfarm employment was down about 0.7 percent, according to the Bureau of Labor Statistics metropolitan area table, so the market is mature and slowing modestly rather than expanding rapidly. For an investor, a labor market that combines low unemployment with slight employment softening tends to support consistent but not explosive demand for rental housing and commercial space that serves local employers.
The industry composition in June 2026 shows that Richmond is not reliant on a single sector but rather has a balanced mix across trade and transportation, professional and business services, government, and education and health services, as summarized below. The employment levels sum to the confirmed total nonfarm figure of 732.8 thousand.
| Industry sector, Richmond metro | Jobs thousand June 2026 | Source |
|---|---|---|
| Mining, logging, and construction | 46.5 | BLS Economy at a Glance |
| Manufacturing | 31.1 | BLS Economy at a Glance |
| Trade, transportation, and utilities | 131.3 | BLS Economy at a Glance |
| Information | 6.2 | BLS Economy at a Glance |
| Financial activities | 59.8 | BLS Economy at a Glance |
| Professional and business services | 124.7 | BLS Economy at a Glance |
| Education and health services | 109.1 | BLS Economy at a Glance |
| Leisure and hospitality | 75.2 | BLS Economy at a Glance |
| Other services | 33.2 | BLS Economy at a Glance |
| Government | 115.7 | BLS Economy at a Glance |
| Total nonfarm | 732.8 | BLS Economy at a Glance |
The table shows that trade, transportation, and utilities form the largest employer group with about 131,300 jobs, closely followed by professional and business services with about 124,700 jobs and government with about 115,700 jobs, while education and health services and leisure and hospitality are also substantial. This diversified mix signals the presence of finance, logistics, professional services, education, health care, and government institutions that together create a broad base of tenants and residents. On the output side, Bureau of Economic Analysis data indicate that metropolitan gross domestic product reached about 116,959.541 million dollars in 2023 in current dollars, confirming the region as a mid sized but economically diverse metro.
Section 04Income
Household incomes in the city of Richmond sit below the Virginia median, which is elevated by the wealthy Washington suburbs, but the metro as a whole is more affluent, and city incomes have grown rapidly in recent years.
United States Census Bureau data for the 2019 through 2023 period report the income and poverty measures below. In the city, median household income rose about 32.6 percent since the 2019 ACS estimate, from about 47,250 dollars to 62,671 dollars, reflecting both wage growth and gentrification in central neighborhoods.
| Income metric | Geography and scope | Value | Source and date |
|---|---|---|---|
| Median household income | Richmond city ACS 5 year 2019 through 2023 | 62,671 dollars | US Census QuickFacts |
| Median household income | Richmond metro ACS 5 year | about 81,388 dollars | US Census Bureau ACS via city of Richmond |
| Person poverty rate | Richmond city ACS 5 year 2019 through 2023 | about 18.8% | US Census Bureau ACS 5 year 2023 |
| Person poverty rate | Richmond metro ACS 5 year | about 10.1% | US Census Bureau ACS via city of Richmond |
The gap between the city and metro figures is meaningful, with the city carrying both a higher poverty rate and lower median income than the suburban ring in Henrico, Chesterfield, and Hanover counties. For an investor, these income characteristics mean a deep pool of workforce and moderate income tenants in the city alongside more affluent owner and renter households in the suburbs, so multifamily and single family rental strategies must segment carefully by submarket and price point rather than assuming a uniform tenant base.
Section 05Housing and Multifamily
The city of Richmond is a renter majority market, while the surrounding suburban counties are more owner occupied, and the multifamily sector has absorbed a substantial recent supply wave.
United States Census Bureau data show that only 43.5 percent of occupied housing units in the city of Richmond were owner occupied for the 2019 through 2023 period, with a median value of owner occupied homes of 328,100 dollars, up about 42 percent since the 2019 ACS estimate. On the institutional side, Yardi Matrix reports an average advertised asking rent of 1,619 dollars per month in early 2026, up 3.6 percent year over year, with stabilized occupancy near 94.8 percent, while CoStar tracked broader market data show an inventory of about 109,117 units, a vacancy rate near 8.3 percent across the wider universe, and about 4,667 units under construction as of the second quarter of 2026.
| Multifamily metric | Geography and scope | Value | Source |
|---|---|---|---|
| Average advertised asking rent | Richmond metro stabilized multifamily | 1,619 dollars per month, change +3.6% year over year | Yardi Matrix April 2026 |
| Stabilized occupancy | Richmond metro stabilized multifamily | 94.8% | Yardi Matrix April 2026 |
| Total inventory | Richmond metro multifamily | about 109,117 units | CoStar Q2 2026 |
| Vacancy, broad universe | Richmond metro multifamily | 8.3% | CoStar Q2 2026 |
| Units under construction | Richmond metro multifamily | about 4,667 units | CoStar Q2 2026 |
The class breakdown from CoStar shows the newest product carrying higher rents and higher vacancy as it leases up, with 4 and 5 star assets at about 1,831 dollars per month and 9.6 percent vacancy, 3 star assets at about 1,572 dollars and 7.8 percent, and 1 and 2 star assets at about 1,312 dollars and 7.3 percent. The presence of government, anchored health systems, and regional service industries supports demand for centrally located multifamily near employment centers, while suburban corridors in Henrico and Chesterfield host more garden style and townhome rental communities. For investors, the current elevated vacancy appears to reflect a temporary supply overhang after two strong delivery years rather than a demand problem, given thirteen consecutive quarters of positive net absorption.
Section 06Rents
Rents in Richmond are more affordable than in the largest coastal markets, yet they have grown quickly relative to peers over the past year.
Yardi Matrix reports that the average advertised asking rent in the Richmond metro was 1,619 dollars per month on a trailing three month basis in early 2026, up 3.6 percent year over year, among the higher rent improvements in the country, even as occupancy in stabilized assets slid about 30 basis points over twelve months to 94.8 percent following two years of strong supply. Census measures show a citywide median gross rent of 1,314 dollars for the 2019 through 2023 period.
| Rent metric | Geography and scope | Value | Source and date |
|---|---|---|---|
| Median gross rent all renters | Richmond city ACS 5 year 2019 through 2023 | 1,314 dollars per month | US Census QuickFacts |
| Average advertised asking rent | Richmond metro stabilized multifamily | 1,619 dollars per month, change +3.6% year over year | Yardi Matrix April 2026 |
| Average asking rent 4 and 5 star | Richmond metro new multifamily | about 1,831 dollars per month | CoStar Q2 2026 |
| Average asking rent 1 and 2 star | Richmond metro older multifamily | about 1,312 dollars per month | CoStar Q2 2026 |
For investors, the rent environment reflects relatively strong recent growth with a still affordable base, but the elevated new supply and its associated lease up vacancy at the top end warn that underwriting should allow for concessions on newer product even as older and more affordable units remain tight.
Section 07Vacancy
Vacancy must be considered separately for multifamily, office, and industrial.
In multifamily, the Richmond metro shows stabilized occupancy near 94.8 percent per Yardi Matrix and a broader universe vacancy near 8.3 percent per CoStar, elevated relative to the market ten year average near 7.0 percent because of recent deliveries, but supported by positive net absorption for thirteen consecutive quarters. On the commercial side, office vacancy in Richmond was about 11.4 percent in the second quarter of 2026 per CBRE and about 12.9 percent per Newmark, having stabilized around 13 percent after peaking near 14.6 percent in mid 2024, so Richmond office is comparatively healthier than in many larger metros. Industrial vacancy was tight at about 5.5 percent in the second quarter of 2026 per CBRE, up modestly as new speculative space delivered.
From these figures, investors can observe that Richmond multifamily is working through a supply overhang rather than a demand shock, that office is comparatively resilient by national standards, and that industrial remains a landlord favorable segment despite recent deliveries, with variation by submarket and asset quality that must be analyzed through current data.
Section 08Supply Pipeline
Supply in Richmond has been material in multifamily and industrial but is now moderating.
On the residential side, CoStar data show about 4,667 multifamily units under construction in the metro as of the second quarter of 2026, a mid single digit share of the roughly 109,117 unit inventory, following two years of strong deliveries that pushed vacancy above its historical average. The market has continued to absorb this supply, with positive net absorption for thirteen consecutive quarters, so the overhang appears temporary rather than structural.
On the commercial side, Cushman and Wakefield data show a substantial industrial construction pipeline of about 6.2 million square feet in early 2026, including significant data center development, along key highway corridors, while the office development pipeline has slowed markedly as tenants reassess space needs and vacancy stabilizes near 13 percent. For investors, the moderating multifamily pipeline suggests that future supply pressure on rents and vacancy is manageable at the metro level, though specific submarkets with clustering of new projects, and the data center driven industrial pipeline, must be monitored closely.
Section 09Single Family Homes
The single family segment in Richmond encompasses owner occupied housing and single family rentals, and the for sale market remains competitive.
Redfin reports that over the three months ending June 2026 the median home sale price in the city of Richmond was about 429,766 dollars, up 0.2 percent year over year, with homes receiving about three offers on average, selling in about 12 days compared with 13 days a year earlier, and going for about 2 percent above list price, with 959 homes sold over that rolling three month period. Statewide, Virginia home prices were up about 4.2 percent year over year in June 2026 to a median of 463,549 dollars.
| Single family market metric | Geography and scope | Period | Value | Year over year change | Source |
|---|---|---|---|---|---|
| Median sale price | Richmond city all home types | Three months ending Jun 2026 | 429,766 dollars | +0.2% | Redfin Richmond housing market |
| Median days on market | Richmond city all home types | Three months ending Jun 2026 | about 12 days, previous year 13 days | -1 day | Redfin Richmond housing market |
| Homes sold | Richmond city all home types | Three months ending Jun 2026 | 959 homes | not stated | Redfin Richmond housing market |
| Median sale price | Virginia statewide | June 2026 | 463,549 dollars | +4.2% | Redfin Virginia housing market |
The data show a fast moving but only modestly appreciating city market, with tight inventory and homes selling above list in under two weeks. Relative to coastal metros, Richmond still offers more attainable prices for middle income households, but higher mortgage rates have created affordability challenges that support demand for single family rentals, particularly in school oriented districts and locations with good access to job centers. Investors pursuing single family rentals should align acquisition prices, renovation costs, and targeted rents with local income distributions rather than national averages.
Section 10Commercial Real Estate and Retail Centers
Commercial real estate in Richmond spans downtown and suburban office, a growing industrial base, and neighborhood retail. Early 2026 fundamentals across the major segments are summarized below.
| Commercial segment | Geography | Period | Vacancy | Source |
|---|---|---|---|---|
| Office | Richmond metro | Q2 2026 | 11.4%, and 12.9% on the Newmark definition | CBRE and Newmark Q2 2026 |
| Industrial | Richmond metro | Q2 2026 | 5.5% | CBRE Q2 2026 |
| Retail | Richmond metro | 2026 | no single published metro figure presented | brokerage commentary |
Office in Richmond has proven comparatively resilient, with vacancy of about 11.4 percent per CBRE and 12.9 percent per Newmark in the second quarter of 2026, having stabilized around 13 percent after peaking near 14.6 percent in mid 2024, which is comparatively healthier than many larger metros. The core demand base comes from professional and business services at about 124,700 jobs, financial activities at about 59,800 jobs, and government at about 115,700 jobs, and while national remote work trends persist, Richmond office has posted positive net absorption recently, so higher quality assets in strong locations can still attract tenants.
Industrial and logistics benefit from Richmond position between larger East Coast markets and its trade and transportation employment of about 131,300 jobs and manufacturing of about 31,100 jobs. Industrial vacancy near 5.5 percent with a large construction pipeline, including data centers, reflects steady demand for warehouse, distribution, and production space along major highway corridors. Retail is bifurcated, with grocery anchored and necessity centers in stable trade areas generally retaining tenants while older power centers face more pressure, and a single published metro retail vacancy figure is not presented here. For investors, industrial and necessity retail have tended to be the more defensive segments, while office and discretionary retail require asset specific analysis; no particular outcome is assured.
Section 11Transactions and Capital Markets
Capital flows into Richmond real estate reflect the metro position as a stable, cash flow oriented secondary market.
Transaction activity slowed during periods of interest rate increases but has continued, with regional and national investors targeting multifamily and industrial assets for durable income. Cap rates in Richmond have historically been higher than in coastal gateway markets, and higher interest rates over the last two years have pushed them upward, meaning lower prices per unit of income in many segments. A single published cap rate series by property type is not presented here, so entry and exit yields are set against current comparable sales and lender feedback.
The stable labor market, the diverse employment base, and multifamily rent growth of 3.6 percent year over year have made Richmond a frequently discussed market among investors seeking secondary market cash flow, but allocation will depend on each investor assessment of relative value versus other Sun Belt and Mid Atlantic markets and on their cost of debt.
Section 12Taxes
Real estate investors in Richmond face state income taxes, local property taxes, and sales taxes.
Virginia levies a graduated individual income tax with a top marginal rate of 5.75 percent that applies to all taxable income over 17,000 dollars, which makes the system effectively near flat for most earners, according to the Virginia Department of Taxation. Virginia has no state property tax, so real estate taxes are set locally, and the city of Richmond real estate tax rate for 2026 is 1.20 dollars per 100 dollars of assessed value, which the City Council voted to hold flat, higher than the surrounding counties.
| Tax | Applies to | Rate | Source |
|---|---|---|---|
| Virginia individual income tax, top marginal rate | Taxable income over 17,000 dollars | 5.75% | Virginia Department of Taxation |
| Richmond city real estate tax | Assessed value of real property | 1.20 dollars per 100 dollars | City of Richmond 2026 |
| Henrico County real estate tax | Assessed value of real property | 0.85 dollars per 100 dollars | Henrico County 2026 |
| Chesterfield County real estate tax | Assessed value of real property | 0.89 dollars per 100 dollars | Chesterfield County 2026 |
| Hanover County real estate tax | Assessed value of real property | 0.79 dollars per 100 dollars | Hanover County 2026 |
Because the city rate of 1.20 dollars per 100 dollars is meaningfully higher than the neighboring county rates, property tax expense is a material component of operating costs that differs sharply across the metro and must be modeled at the parcel and jurisdiction level, along with Virginia personal property taxes on business assets and any special district levies.
Section 13Insurance
Insurance costs for residential and commercial properties in Richmond depend on standard property and liability coverage plus flood coverage where applicable.
A single published average insurance premium by city and property type is not available, so investors should obtain property specific quotes. Richmond is not located on the Atlantic coast and therefore faces less direct exposure to storm surge than coastal cities, but it is adjacent to the James River and subject to heavy rainfall events, so flood risk is an important factor for properties in designated floodplains. Investors should consult FEMA flood insurance rate maps and local insurers to understand how base flood elevations and risk classifications translate into required flood coverage and premium levels for specific sites, and should not assume that past insurance expenses on historical statements fully capture current market premiums.
Section 14Landlord Tenant and Regulatory Environment
Virginia landlord tenant law and Richmond local regulations shape the operating environment for rental properties.
Virginia is generally viewed in the investment community as a relatively balanced to landlord friendly state compared with jurisdictions that have adopted strict rent control or expansive tenant protections. The Virginia Residential Landlord and Tenant Act governs lease requirements, notice periods, security deposit rules, maintenance obligations, and eviction procedures at the state level, with clear processes that allow landlords to enforce leases when properly documented. Local property maintenance codes and any programs governing affordable housing or tenant protections apply at the city and county level. Investors considering Richmond assets should rely on counsel to review the applicable statutes, ordinances, and eviction procedures and integrate those findings with the financial analysis in other sections of this report.
Section 15Infrastructure
Infrastructure is a critical component of real estate value in central Virginia.
Richmond International Airport served a record of about 4.92 million passengers in 2025, up 0.8 percent and a third consecutive annual record, and handled about 223 million pounds of cargo, according to the Capital Region Airport Commission, supporting business travel, logistics, and related demand. Richmond serves as a transportation hub where Interstate 95 and Interstate 64 intersect, linking it to Washington, Hampton Roads, and other East Coast metros, which supports distribution, commuting, and retail trade.
For multifamily, single family, and commercial investors, the most relevant infrastructure questions tend to be micro level, such as proximity to freeway interchanges and major arterials, as well as the capacity and reliability of utilities such as water, sewer, electric, and broadband, and these questions must be addressed at the property or neighborhood level through local due diligence.
Section 16Climate and Physical Risks
Richmond physical risk profile is shaped by its inland but river adjacent location in central Virginia.
Many properties are exposed to riverine flooding along the James River and its tributaries, as well as to heavy rainfall events associated with remnant tropical systems and thunderstorms, and to the usual risks of wind, hail, and winter weather in the Mid Atlantic. A single official metro level percentage of land or population in Special Flood Hazard Areas is not published as a summary statistic, so flood exposure is assessed parcel by parcel using FEMA flood insurance rate maps.
Properties in or near mapped floodplains carry additional risk of flood damage and likely require higher insurance coverage, while properties on higher ground away from the river may be less exposed to flooding but still face risks from severe storms and aging infrastructure. Investors should incorporate climate and physical risk assessments, including projected changes under different climate scenarios, into their underwriting using specialized tools and local expertise.
Section 17Neighborhoods and Submarkets
The Richmond market segments into downtown, historic neighborhoods near the core, inner ring residential areas, and suburban corridors in surrounding counties.
The central city contains a mix of historic housing stock, renovated multifamily properties, and newer infill projects, with strong recent rent and income growth in gentrifying neighborhoods, while suburban counties such as Henrico and Chesterfield contain more low density subdivisions, garden style rentals, and shopping centers. Each submarket has a different balance of renter and owner households, commute patterns, property tax rates, and amenity access, and the sharp difference between the city real estate tax rate of 1.20 dollars per 100 dollars and the lower county rates is itself a meaningful driver of net operating income across jurisdictions.
From a strategic perspective, submarkets that combine proximity to employment nodes, access to Interstate 95 and Interstate 64, and stable or growing resident incomes may present more favorable risk adjusted characteristics than areas with weaker access or declining socioeconomic indicators, though this is a general educational observation and no particular outcome is assured; investors should map these zones using tract level Census data and local market surveys.
Section 18Opportunities
Several opportunity themes emerge for Richmond.
First, the diverse workforce of about 733,000 nonfarm jobs spread across professional services, finance, government, education and health services, trade, and leisure and hospitality, combined with a low 3.8 percent unemployment rate, supports continued demand for both rental housing and income producing commercial real estate. Second, Richmond position as a regional logistics hub with about 131,300 trade and transportation jobs and tight industrial vacancy near 5.5 percent suggests that industrial and logistics assets near major transportation corridors may benefit from structural trends in goods movement and e commerce.
Third, for multifamily and single family rentals, the combination of a broad employment base, 3.6 percent year over year rent growth, and the national context of elevated mortgage rates creates a setting in which many working households may prefer or be compelled to rent, which can support occupancy and rent collections for well located, appropriately priced product. Fourth, the current multifamily supply overhang, reflected in vacancy near 8.3 percent, may create acquisition opportunities on newer assets still in lease up at bases that some investors find favorable relative to replacement cost, for those comfortable with near term concessions.
These are general educational observations, not recommendations, and no particular outcome is assured; actual results depend on asset specific factors, execution, and market conditions.
Section 19Risks
The region carries material risks that investors must weigh.
On the fundamental side, the Bureau of Labor Statistics data show total nonfarm employment down about 0.7 percent over the year to June 2026, which indicates that Richmond is not experiencing strong cyclical growth and may be vulnerable if national conditions weaken further. The recent multifamily supply wave has pushed vacancy above the market historical average, and while absorption has been positive, further deliveries could pressure rents and concessions in specific submarkets.
Like many United States markets, Richmond faces a bifurcation between stronger and weaker submarkets, with older office properties and less well located retail centers at risk of higher vacancy in the face of changing work and shopping patterns, and the city high real estate tax rate of 1.20 dollars per 100 dollars weighs on net operating income relative to the surrounding counties. Climate and physical risks related to flooding along the James River, along with rising insurance costs and lender requirements tied to these risks, can compress yields or make some projects difficult to finance. Finally, capital markets risk from interest rates and lender appetite must be incorporated into conservative underwriting. As with any real estate investment, a loss of some or all invested capital is possible.
Section 20Investor Implications
For United States accredited investors considering Richmond exposure, the region labor market and economic structure appear broadly supportive of real estate investment, based on confirmed federal data, though the modest recent job softening and the multifamily supply overhang call for disciplined underwriting.
Multifamily investors should treat Richmond as a market where stable employment, institutional anchors, and strong recent rent growth are positives, but should underwrite to realistic occupancy near the current 94.8 percent stabilized level and account for lease up concessions on newer product, using submarket specific data on rents and pipeline supply. Single family rental investors can view Richmond as part of a broader theme in which working households in stable employment markets facing higher mortgage rates opt to rent, but must align acquisition prices near the 429,766 dollar city median, renovation costs, and targeted rents with actual local income distributions.
Commercial investors should recognize that Richmond office at about 11 to 13 percent vacancy is comparatively healthy while industrial near 5.5 percent remains landlord favorable, and should use the Bureau of Labor Statistics employment mix as an initial guide to which property types are most deeply rooted in the regional economy, then rely on asset level leasing and performance data to complete the picture. Across all asset classes, the sharp differences in property tax rates across jurisdictions must be modeled explicitly. These are general observations, not recommendations, and no particular outcome is assured.
Section 21Conclusion
Richmond, Virginia presents a diversified, stable secondary market with reasonable pricing relative to income and a broad employment base, offset by modest recent job softening, a multifamily supply overhang, and asset specific risks.
On the strength side, public data indicate a metro of about 1.35 million people with a 116,959.541 million dollar economy, a 3.8 percent unemployment rate, city median household income of 62,671 dollars, multifamily rent growth of 3.6 percent year over year, and comparatively healthy office and industrial fundamentals. On the caution side, total nonfarm employment is down about 0.7 percent over the year, multifamily vacancy near 8.3 percent reflects a recent supply wave, and the city real estate tax rate of 1.20 dollars per 100 dollars is high relative to neighboring counties.
For accredited investors, Richmond is best viewed as a mature, diversified secondary market where long run performance will depend on careful selection of submarkets and assets, disciplined underwriting that accounts for both macro employment trends and micro neighborhood conditions, and proactive management of regulatory, tax, insurance, and climate related risks. Returns are not guaranteed and a loss of principal is possible. As always, transaction specific due diligence, including fresh data on rents, vacancy, cap rates, and regulatory conditions, is indispensable.