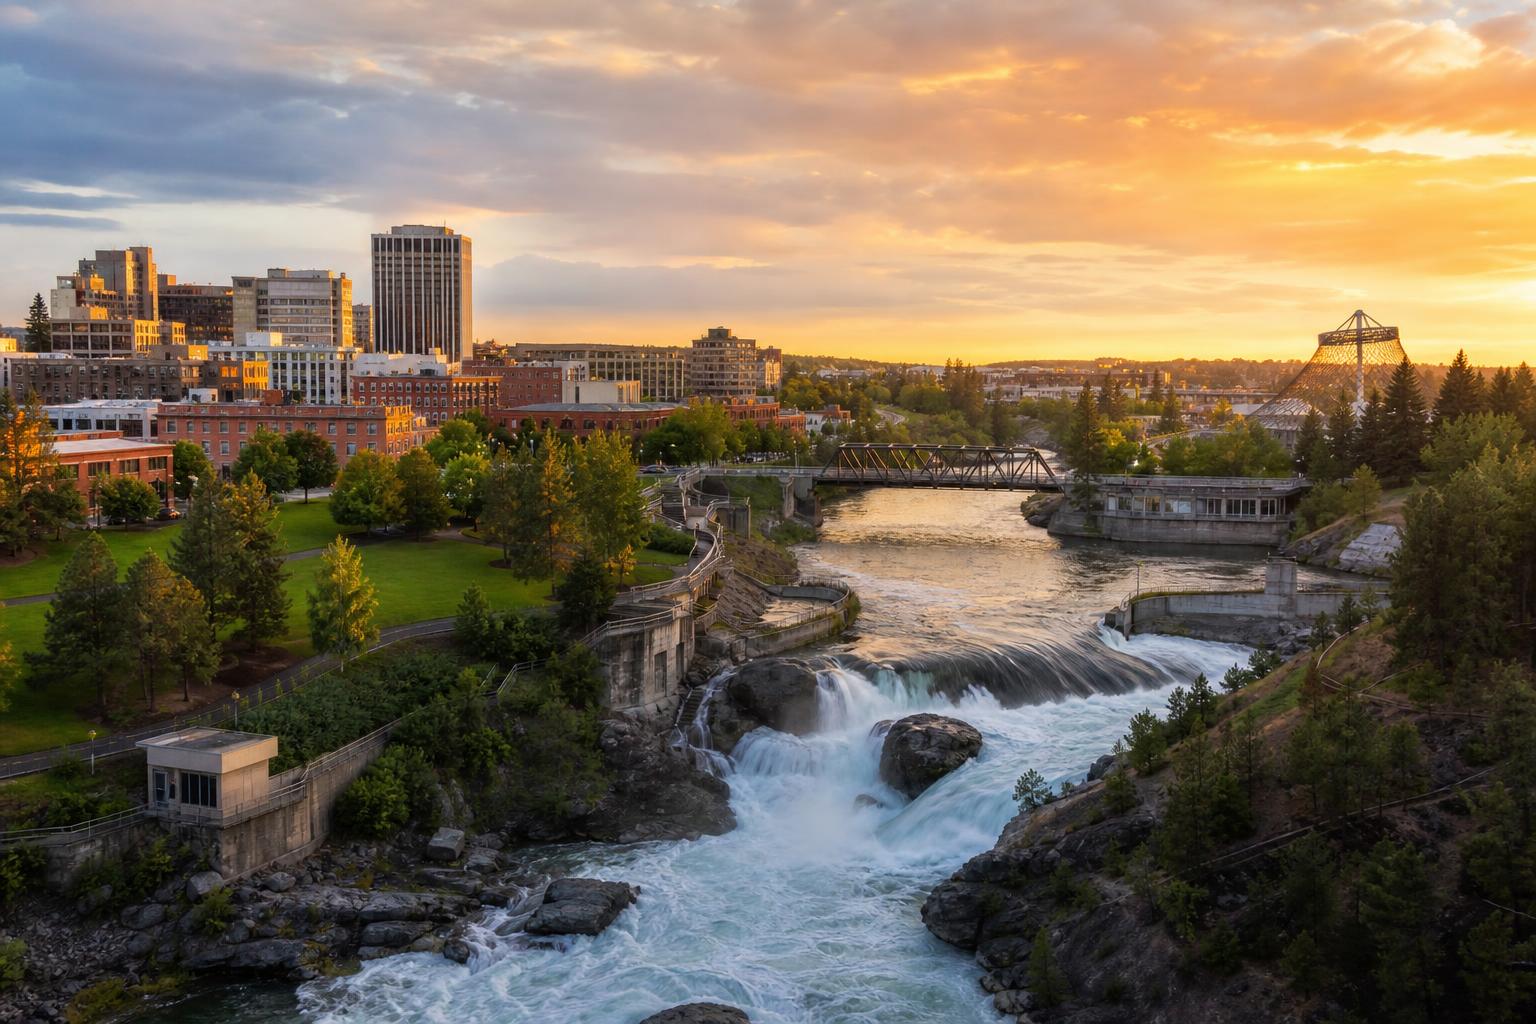
In brief · summary: Spokane
Spokane enters the second half of 2026 as a mid sized, high affordability metro whose real estate cycle looks different from the coastal Puget Sound market it shares a state with. The Spokane, Spokane Valley metropolitan statistical area, made up of Spokane and Stevens counties, had an estimated population of 608,012 as of July 1, 2025, according to Census Bureau data cited by Wikipedia and City Population, up from 585,784 at the 2020 census. That is modest growth by the standard of Sun Belt boomtowns, but it has been enough to keep the region's apartment and single family housing markets absorbing new supply even as construction cooled sharply from its 2023 to 2024 peak.
The defining fact for a Spokane investor in 2026 is the divergence between an apartment market whose supply overhang is finally clearing and a downtown office market whose vacancy keeps getting worse, not better. Spokane County multifamily vacancy, which spiked to roughly 9.2 percent in the third quarter of 2024 after 1,699 units delivered in 2023 and another 2,053 in 2024, has eased to a 7.3 to 7.7 percent range in the second quarter of 2026 as new construction slowed to just 784 units in 2025, according to SVN Cornerstone, ACTIV8 Real Estate, and Kidder Mathews. Asking rents rose only 0.6 percent year over year to about $1,395 per unit on a CoStar basis reported by ACTIV8 Real Estate, so this remains an occupancy led recovery rather than a pricing one.
The offsetting risk an investor cannot ignore is insurance. Washington homeowners insurance premiums rose 16.6 percent in 2023 and 21.7 percent in 2024, driven substantially by the 2023 Medical Lake and Elk wildfires on Spokane's western edge, before plateauing with a slight decline by May 2026, per the Washington Office of the Insurance Commissioner. Spokane County ranks in the 97th percentile nationally for wildfire exposure under FEMA's National Risk Index, a fact that is actively reshaping the local insurance market.
Section 01Executive Summary
Spokane, Washington enters the second half of 2026 as a mid sized, high affordability metro whose real estate cycle looks quite different from the coastal Puget Sound market it shares a state with. The Spokane, Spokane Valley metropolitan statistical area, composed of Spokane and Stevens counties, had an estimated population of 608,012 as of July 1, 2025, according to Census Bureau population estimates cited by Wikipedia and by City Population, up from 585,784 at the 2020 census, a gain of about 3.8 percent over five years. Spokane County alone held roughly 558,344 residents in 2025, up 3.52 percent from 539,339 at the 2020 census. That is modest growth by the standard of Sun Belt boomtowns, but it has been steady, and it has been enough to keep the region's apartment and single family housing markets absorbing new supply even as construction cooled sharply from its 2023 to 2024 peak.
The defining fact for a Spokane investor in 2026 is the divergence between an apartment market whose supply overhang is finally clearing and a downtown office market whose vacancy keeps getting worse. Spokane County multifamily vacancy, which spiked to roughly 9.2 percent in the third quarter of 2024 after a record 1,699 units delivered in 2023 and another 2,053 in 2024, well above the historical average of about 1,200 units a year, has eased to a 7.3 to 7.7 percent range in the second quarter of 2026 as new construction slowed to just 784 units in 2025, according to SVN Cornerstone's June 2026 market update, ACTIV8 Real Estate's second quarter 2026 report using CoStar data, and Kidder Mathews' Eastern Washington apartment market series. Asking rents rose only 0.6 percent year over year to about $1,395 per unit, so this remains an occupancy led recovery rather than a pricing one, a pattern many larger metros are also working through.
Single family home prices are essentially flat to modestly higher depending on the index and geography. Redfin shows the city of Spokane at a median sale price of $383,443 for the three months ending July 2026, down 0.4 percent year over year, while Spokane County as a whole, which captures more suburban and exurban demand, rose 0.6 percent to $447,687 over the same period. Commercial real estate is sharply bifurcated by submarket rather than by property type alone: downtown office vacancy has climbed toward 28 to 31 percent according to Kiemle Hagood's 2026 market review, even as metro wide office vacancy, buoyed by tight suburban submarkets such as South Hill at 2.6 percent, sits closer to 7.6 percent, while industrial vacancy of 6.1 percent and retail vacancy of 5.3 percent, both reported by the Spokane Journal of Business, remain historically tight.
The offsetting risk that a Spokane investor cannot ignore is insurance. Washington homeowners insurance premiums rose 16.6 percent in 2023 and 21.7 percent in 2024, driven substantially by the 2023 Medical Lake and Elk wildfires on Spokane's western edge, before plateauing with a slight 0.5 percent decline as of May 2026, according to Washington's Office of the Insurance Commissioner as reported by the Spokane Journal of Business. Spokane County ranks in the 97th percentile nationally for wildfire exposure under FEMA's National Risk Index, a fact that is reshaping the local insurance market in real time, including an emergency order from the state insurance commissioner covering wildfire affected zip codes through September 30, 2026. Set against that risk, Washington's new statewide rent stabilization law, effective May 2025, caps annual rent increases at the lesser of 10 percent or 7 percent plus the Consumer Price Index, a genuinely landlord relevant regulatory change that did not exist a market cycle ago. The overall case for Spokane rests on affordability, a median household income that Census Bureau data show topped the national median for the first time in 2024, and a multifamily supply pipeline that is thinning fast, weighed against wildfire driven insurance costs and a downtown office market that has yet to find its floor.
Section 02Population and Migration
Population growth in Spokane is steady rather than explosive, and that steadiness is itself the story. The Census Bureau's population estimates for metropolitan and micropolitan statistical areas, as compiled and cited by Wikipedia and by City Population using Census Bureau source data, placed the Spokane, Spokane Valley metropolitan statistical area, composed of Spokane and Stevens counties, at 608,012 residents as of July 1, 2025, up from 585,784 at the 2020 census, a gain of about 3.8 percent over five years. Spokane County, the urban core county and home to both the city of Spokane and Spokane Valley, held an estimated 558,344 residents in 2025 according to the Wikipedia entry for Spokane County citing Census Bureau data, up 3.52 percent from 539,339 at the 2020 census. Stevens County, the more rural northern county in the MSA, grew somewhat faster on a percentage basis, up 6.94 percent to an estimated 49,668 residents.
The city of Spokane itself, the second most populous city in Washington after Seattle, had 228,989 residents at the 2020 census and an estimated 230,783 residents in 2025, per Wikipedia's citation of Census Bureau figures. A broader combined statistical area that groups the Spokane metro with Kootenai County, Idaho, home to Coeur d'Alene, reported a population of roughly 785,302 to 793,285 depending on the source and vintage, according to Wikipedia and CensusReporter respectively, underscoring that the practical labor and housing market for many Spokane employers and renters extends across the state line into North Idaho. The Washington State Office of Financial Management's own April 2025 population trends report corroborates the same general order of magnitude for Spokane County, showing continued year over year gains through 2025.
| Geography | Population | Scope and source |
|---|---|---|
| Spokane, Spokane Valley MSA | 608,012 | July 2025 estimate, Census Bureau via Wikipedia and City Population |
| Spokane County | 558,344 | 2025 estimate, Census Bureau via Wikipedia |
| City of Spokane | 230,783 | 2025 estimate, Census Bureau via Wikipedia |
| Stevens County | 49,668 | 2025 estimate, Census Bureau via Wikipedia |
| Spokane, Spokane Valley, Coeur d'Alene CSA | ~785,000 to 793,000 | Combined statistical area, Wikipedia and CensusReporter |
Spokane's growth has been driven substantially by in migration from Western Washington and out of state buyers drawn by relative affordability compared with Seattle, alongside modest natural increase, rather than by the kind of large scale corporate relocation or energy sector expansion that drives Sun Belt population booms. For an investor, the conclusion is that Spokane's growth is real but modest, roughly one percent a year at the county level, concentrated in the metro's suburbs and in the exurban Stevens County ring, which is consistent with a market where rents and prices move gradually rather than spiking, and where the primary demand driver is affordability seeking migration from more expensive West Coast metros rather than raw population expansion.
Section 03Jobs and Economic Anchors
Spokane's labor market is stable but has essentially stopped growing, a meaningful difference from booming Sun Belt metros. The Bureau of Labor Statistics Economy at a Glance for the Spokane, Spokane Valley metropolitan area, with data extracted August 26, 2026, reported total nonfarm employment of 263,800 in July 2026 on a preliminary basis, down 1.0 percent from a year earlier, following readings of 266,100 in June, 266,800 in May, and 265,300 in April, a series that has drifted essentially flat to slightly negative on a year over year basis since the spring. The same source showed the not seasonally adjusted unemployment rate falling from 5.3 percent in February 2026 to a preliminary 3.9 percent in June 2026, a decline that is encouraging on its face but is consistent with a shrinking labor force as much as with robust hiring. The Mining, Logging, and Construction category, which BLS groups together for this metro, rose from 14,500 in February to a preliminary 15,900 in July 2026, the one clearly growing segment of the local economy. A separate Federal Reserve Bank of St. Louis FRED series put the Spokane metro unemployment rate at 4.3 percent in July 2026, close to but not identical to the BLS reading for the same period, a normal function of different vintages and seasonal adjustment methods.
| Indicator, Spokane metro | Value | Change | Scope and source |
|---|---|---|---|
| Total nonfarm employment | 263,800 | -1.0% YoY | July 2026 preliminary, BLS |
| Unemployment rate | 3.9% | -1.4 pts vs Feb | June 2026 preliminary, not seasonally adjusted, BLS |
| Mining, Logging, and Construction employment | 15,900 | -0.6% YoY | July 2026 preliminary, BLS |
| Washington state unemployment rate | 5.2% | not stated | June 2026 preliminary, BLS |
Spokane's economic base is anchored by federal military presence, healthcare, higher education, and logistics rather than by a single dominant industry. Fairchild Air Force Base, home to the 92nd Air Refueling Wing, is Spokane County's single largest employer, as reported in the Journal of Business 2025 Book of Lists and cited by Greater Spokane Incorporated, which notes that the region carries 75 percent more federal government and military employment than the national average for a metro of its size, at wages roughly 9 percent above the national average for those jobs. Providence Inland Northwest Washington, the region's dominant hospital system, the State of Washington, Spokane Public Schools, Amazon, and MultiCare Health System round out the next tier of major employers, according to SVN Cornerstone's compilation of Spokane Journal of Business data. Major sectors identified by the Washington State Employment Security Department's county profile are government, higher education, medical services, retail trade, and finance.
| Employer | Sector | Approx. employees |
|---|---|---|
| Fairchild Air Force Base | Federal government, military | ~7,400 |
| Providence Inland Northwest Washington | Healthcare | ~6,800 |
| State of Washington | State government | ~5,900 |
| Spokane Public Schools | Public education | ~3,750 |
| Amazon | Logistics, distribution | ~3,700 |
| MultiCare Health System, Inland Northwest | Healthcare | ~3,350 |
| Gonzaga University | Higher education | ~1,340 |
The investor conclusion is that Spokane's job base is durable and recession resistant, anchored by government, military, healthcare, and education employment that does not disappear in a downturn, but it is not a growth engine in the way a Sun Belt logistics or energy hub is. Nonfarm payrolls have been flat to modestly negative for most of 2026, and rent growth or absorption gains in Spokane real estate should be attributed to in migration and thinning supply rather than to job creation.
Section 04Income
Household income in Spokane made a genuinely notable jump in the most recent data, a fact worth underwriting carefully rather than simply extrapolating. According to 2024 American Community Survey data from the Census Bureau, as reported by National Today in March 2026, Spokane County's median household income reached $86,206 in 2024, up from $73,583 in 2023, a 17 percent single year increase that pushed the county above the national median household income of $81,439 for the first time on record. The same reporting noted that Spokane's per capita personal income was $58,600 in 2024, still only about 82 to 83 percent of the national per capita figure, meaning the county level median jump reflects household composition and dual income growth as much as it reflects individual wage gains. A separate five year American Community Survey estimate for the city of Spokane specifically, compiled by CensusFlow, put median household income at a considerably lower $70,064, a gap that reflects both the different geography, the city core versus the full county, and the different estimation window, a five year rolling average versus a single year estimate.
| Geography | Median household income | Scope and source |
|---|---|---|
| Spokane County | $86,206 | 2024, 1-year ACS via Census Bureau, cited by National Today |
| City of Spokane | $70,064 | 2024, 5-year ACS estimate via CensusFlow |
| United States | $81,439 | 2024, Census Bureau |
For an investor, the practical read is twofold. The county level income surge, if it holds up in subsequent ACS releases, would meaningfully expand the pool of households who can afford both market rate rents and move up home purchases, and it is broadly consistent with the story of Seattle area and California households relocating to Spokane and bringing higher incomes with them. At the same time, the much lower five year city level estimate is a reminder that income inside Spokane's urban core, where much of the rental housing stock sits, remains modest by national standards, which caps how quickly landlords in the city itself can push rents, a dynamic visible in the muted 0.6 percent asking rent growth reported for the broader metro in 2026.
Section 05Housing and Multifamily
The apartment market is the sector where Spokane's post pandemic supply cycle is most visible, and the second quarter of 2026 marks the clearest sign yet that the cycle is turning. ACTIV8 Real Estate, using CoStar data in its Spokane Multifamily Market Report dated August 13, 2026, reported a market vacancy rate of 7.3 percent for the second quarter of 2026, essentially flat year over year and down from a peak above 9 percent in late 2024, with average asking rent of $1,395 per unit, up just 0.6 percent year over year, and effective rent, after concessions, of $1,343. Measured against roughly 3.6 percent inflation over the same period, that means most owners lost modest ground in real terms. Trailing twelve month net absorption of 735 units roughly matched 815 units of deliveries, a tight, near balanced ratio that explains why vacancy has held rather than fallen further.
SVN Cornerstone's Spokane County Multifamily Market Update, published June 24, 2026, tells a consistent and more granular story: vacancy climbed from just 3.3 percent in the first quarter of 2021 to a peak of 9.2 percent in the third quarter of 2024, driven by a record wave of new construction that delivered 1,699 units in 2023 and 2,053 units in 2024, well above the historical average of roughly 1,200 units per year. Since construction activity slowed sharply to just 784 new units in 2025, vacancy has improved to 7.47 percent as of the second quarter of 2026, and the report's author noted that several apartment owners had begun raising rents again in select submarkets as of June 2026. Kidder Mathews' Eastern Washington apartment market research, covering a wider geography that includes Spokane, reported vacancy of 7.7 percent for the second quarter of 2026, down 10 basis points from the first quarter and down 90 basis points year over year, alongside cap rate compression to 6.2 percent from 6.5 percent in the first quarter of 2026.
| Series and scope | Level or reading | Change | Period and source |
|---|---|---|---|
| Market vacancy, CoStar sample | 7.3% | flat YoY, down from ~9% late-2024 peak | Q2 2026, ACTIV8 Real Estate |
| County vacancy, SVN Cornerstone sample | 7.47% | down from 9.2% Q3 2024 peak | Q2 2026, SVN Cornerstone |
| Eastern Washington vacancy, Kidder Mathews sample | 7.7% | -10 bps QoQ, -90 bps YoY | Q2 2026, Kidder Mathews |
| Average asking rent | $1,395/unit | +0.6% YoY | Q2 2026, CoStar via ACTIV8 Real Estate |
| Effective rent, after concessions | $1,343/unit | not stated | Q2 2026, CoStar via ACTIV8 Real Estate |
The spread between a 7.3 percent CoStar backed reading and a 7.7 percent Kidder Mathews figure is a function of different property samples and geographic scope, and an investor should treat the consistent direction, vacancy falling from a 2024 peak toward the high 6 percent to high 7 percent range, as more reliable than any single point estimate. Spokane's pre pandemic vacancy floor was closer to 3.3 percent, so the current level still sits well above what the market has historically cleared at, which is precisely why rent growth remains stuck near zero in real terms even as the headline trend improves.
Section 06Rents
Spokane rents remain modest by West Coast standards, and the current trajectory is best described as a plateau rather than a recovery. At $1,395 per unit on an average asking basis and $1,343 effective, per ACTIV8 Real Estate's second quarter 2026 CoStar based report, Spokane rents sit well below Seattle and other Puget Sound markets, which supports continued demand from affordability seeking households leaving the west side of the state. The 0.6 percent year over year gain in asking rent is a positive signal after a multi year stretch of essentially flat pricing, but ACTIV8's own analysis notes that against roughly 3.6 percent inflation, real rents were flat to slightly negative, meaning landlords are not yet recovering the ground lost during the supply wave.
Performance varies sharply by quality tier and by submarket. The 4 and 5 Star luxury segment, with asking rents around $1,620, actually saw rents slip roughly 0.6 percent as new higher end supply from the 2023 and 2024 delivery wave competed head to head for renters, while more modestly priced product has held up better. SVN Cornerstone's June 2026 update specifically flagged North Spokane and Spokane Valley as submarkets still carrying higher vacancy, while other parts of the county were seeing renewed rent growth as owners regained confidence. HUD's Fair Market Rents for the Spokane, WA metro FMR area, effective October 1, 2025 for federal fiscal year 2026, set the two bedroom standard at $1,531 a month, close to the broader market average, though HUD's small area figures vary meaningfully by zip code, from $1,340 for a two bedroom in downtown Spokane's 99201 to $1,530 in suburban 99030 and 99260, illustrating the same submarket dispersion visible in the private market data.
| Unit size | FY2026 Fair Market Rent | Scope and source |
|---|---|---|
| Studio / efficiency | $1,103 | Spokane County, HUD via City of Spokane, effective Oct 2025 |
| 1 bedroom | $1,193 | Spokane County, HUD via City of Spokane |
| 2 bedroom | $1,531 | Spokane County, HUD via City of Spokane |
| 3 bedroom | $2,088 | Spokane County, HUD via City of Spokane |
| 4 bedroom | $2,260 | Spokane County, HUD via City of Spokane |
The practical read for an investor is that Spokane is not a market to underwrite for near term rent spikes. Flat to low single digit nominal rent growth, a supply pipeline that is thinning quickly, and submarket level variation between softer North Spokane and Spokane Valley product and firmer close in neighborhoods together describe a market where operational execution and disciplined submarket selection, rather than broad rent growth assumptions, will drive returns over the next several years.
Section 07Vacancy
Vacancy is the clearest signal of where Spokane sits in its cycle, and the picture differs sharply by property type. Multifamily vacancy, at 7.3 to 7.7 percent across the CoStar, SVN Cornerstone, and Kidder Mathews samples for the second quarter of 2026, remains above the market's pre pandemic norm near 3.3 percent, but it is now falling from an August 2024 peak near 9.2 percent as new deliveries recede. Office vacancy is the outlier moving the wrong direction: ACTIV8 Real Estate's first quarter 2026 office report put metro wide vacancy at 7.6 percent, less than half the roughly 19 percent national average, with a wide submarket spread of 2.6 percent in South Hill, 7.4 percent in Spokane Valley, 5.8 percent in West Plains, and 11.3 percent in the Spokane central business district. Kiemle Hagood's 2026 Market Review, as reported by the Spokane Journal of Business, described a much higher downtown specific vacancy rate, climbing to roughly 30 percent in fall 2025, up from 19.7 percent in 2023 and 18.8 percent in 2022, a figure that reflects a narrower, downtown only definition and a different data set than ACTIV8's metro wide sample.
Industrial vacancy, at 6.1 percent across Spokane's 56.8 million square foot base according to the Spokane Journal of Business's midyear 2026 commercial real estate review, sits below the roughly 7.5 percent national figure but well above the sub 3 percent levels the market saw a decade ago, after roughly 5.1 million square feet delivered against about 3.2 million square feet absorbed over the past five years. Retail vacancy, at 5.3 percent metro wide per the same source, is the tightest of the three commercial sectors, helped by the lowest annual volume of new retail deliveries on record, roughly 13,000 square feet marketwide over the trailing year. The unifying theme is that Spokane vacancy is improving or historically tight everywhere except the downtown office core, where the overhang is concentrated in older Class B and C buildings rather than in suburban or newer product.
Section 08Supply Pipeline
The forward multifamily supply picture is the single most constructive element of the Spokane thesis. After a record wave of 1,699 units delivered in 2023 and 2,053 units in 2024, both well above the market's historical average of roughly 1,200 units per year, construction activity slowed to just 784 new units in 2025, according to SVN Cornerstone's June 2026 market update. That is a structurally favorable setup: a market with modest but steady population growth meeting a sharply reduced flow of new competition is the condition under which vacancy tightens and rents eventually regain pricing power, the same dynamic that is beginning to show up in the submarket level rent increases SVN Cornerstone documented in June 2026.
Industrial construction tells a related but distinct story. Over the past five years the Spokane industrial market added roughly 5.1 million square feet against about 3.2 million square feet of net absorption, according to the Spokane Journal of Business's midyear 2026 review, a supply surplus that explains the market's elevated but still moderate 6.1 percent vacancy. Looking forward, a new industrial park is planned on the West Plains near Spokane International Airport, with a SEPA environmental checklist filed with Spokane County describing up to 40 buildings totaling as much as 1.24 million square feet on a 93 acre site south of the airport, roughly one mile east of Amazon's existing 2.6 million square foot fulfillment center, according to the Spokane Journal of Business's reporting in July 2025, with initial site work expected between mid 2025 and late 2026. Retail construction, by contrast, is essentially dormant, with only about 13,000 square feet of new retail space delivered marketwide over the trailing year, the lowest volume on record per the Spokane Journal of Business, which removes the supply risk that weighs on some faster growing Sun Belt retail markets.
Section 09Single Family Homes
Spokane's single family market is best described as stable to modestly softening in the urban core and modestly appreciating across the broader county, a pattern that reflects continued suburban and exurban demand even as city prices plateau. Redfin reported that the median sale price for the city of Spokane was $383,443 over the three months ending July 2026, down 0.4 percent year over year, while the median price per square foot rose 4.5 percent to $207, a divergence suggesting a shift toward smaller or more modestly priced homes selling within the mix. Spokane County as a whole, which captures more new construction and suburban growth, showed a median sale price of $447,687 over the same period, up 0.6 percent year over year, with price per square foot up 0.9 percent to $218, according to Redfin's county level data.
Zillow's typical home value measure for Spokane stood at $401,824 as of July 31, 2026, down 0.4 percent over the past year, with homes typically going to pending status in around 19 days, a relatively brisk pace that indicates the market has not slowed to the degree seen in some larger metros. Zillow separately reported a median sale price of $397,867 and a median list price of $427,950 for the same period. At the neighborhood level, Zillow's data show meaningfully different price points across the city, from $290,389 in Emerson Garfield and $307,300 in Logan to $401,068 in Riverside, underscoring how much submarket selection matters within Spokane itself. A January 2026 snapshot compiled by The Collection Spokane illustrates how much these indices can diverge at a single point in time: Redfin's median sold price for that month was $350,000, Zillow's typical home value was about $385,151, and Realtor.com's median list price ran closer to $420,000, each measuring a different slice of the market.
| Metric and scope | Value | Change | Period and source |
|---|---|---|---|
| Median sale price, city of Spokane | $383,443 | -0.4% YoY | 3 months through July 2026, Redfin |
| Median price per sq ft, city | $207 | +4.5% YoY | 3 months through July 2026, Redfin |
| Median sale price, Spokane County | $447,687 | +0.6% YoY | 3 months through July 2026, Redfin |
| Typical home value (ZHVI), Spokane | $401,824 | -0.4% YoY | Through July 31, 2026, Zillow |
| Median list price, Spokane | $427,950 | not stated | 2026, Zillow |
Read together, these figures describe a for sale market that is broadly balanced: prices in the city core are flat to slightly down, county wide suburban prices are edging higher, days on market remain relatively short, and the price per square foot gap between city and county points to continued new construction activity at the edges of the metro. For an investor, moderate and largely stable prices, combined with genuine affordability relative to Seattle and Portland, support a durable pool of both renters and eventual move up buyers, though the same forces that keep prices in check, a labor market that is not adding jobs, also cap how quickly rents or values can accelerate from here.
Section 10Commercial Real Estate and Retail Centers
Spokane's commercial sectors are moving on sharply different tracks, and the divergence runs more by submarket and building class than by broad property type. Office is the clear laggard, but the weakness is concentrated almost entirely downtown. Emilie Cameron, president and CEO of the Downtown Spokane Partnership, told the Spokane Journal of Business in mid 2026 that downtown vacancy has climbed to roughly 30 percent, citing hybrid work adoption, aging buildings, rising costs, and public safety concerns, a rise from 19.7 percent in 2023 and 18.8 percent in 2022 according to Kiemle Hagood's market reviews. That distress is showing up in pricing: RenCorp's recent purchase of the distressed Class B and C building at 111 North Wall Street closed at roughly $22 per square foot, according to ACTIV8 Real Estate's first quarter 2026 office report, which also found metro wide office vacancy of just 7.6 percent, less than half the national average, with a wide submarket spread from 2.6 percent in South Hill and 5.8 percent in West Plains to 7.4 percent in Spokane Valley and 11.3 percent in the central business district on its own methodology.
Industrial and logistics is the market's steadiest performer, anchored by Spokane International Airport, the West Plains distribution corridor, and Amazon's regional footprint, which includes a 2.6 million square foot fulfillment center, an air cargo facility, and a last mile delivery building in Airway Heights. The Spokane Journal of Business's midyear 2026 review put the metro's industrial base at 56.8 million square feet with vacancy of 6.1 percent, below the roughly 7.5 percent national figure though above the sub 3 percent levels of a decade ago, and asking rents averaging about $9.60 per square foot, up a modest 1.3 percent year over year. Retail is tight and improving further at the margin outside of downtown: metro wide retail vacancy stood at 5.3 percent per the Spokane Journal of Business, and Calibre CBI's April 2026 quarterly report found that Spokane Valley retail vacancy has fallen from 12 to 15 percent a decade ago to just 4 to 5 percent currently, reflecting strong suburban fundamentals, even as downtown retail continues to struggle because it depends heavily on daytime office occupancy for foot traffic.
| Sector and scope | Vacancy | Asking rent | Period and source |
|---|---|---|---|
| Office, metro wide | 7.6% | not stated | Q1 2026, ACTIV8 Real Estate |
| Office, downtown CBD | ~28-31% | ~$22/SF, distressed Class B/C sale | 2026, Kiemle Hagood via Spokane Journal of Business |
| Industrial, metro (56.8M SF base) | 6.1% | $9.60/SF, +1.3% YoY | 2026, Spokane Journal of Business |
| Retail, metro wide | 5.3% | not stated | 2026, Spokane Journal of Business |
| Retail, Spokane Valley | 4-5% | not stated | 2026, Calibre CBI |
The unifying commercial conclusion is that a Spokane investor should be highly selective in downtown office, where distress is real and building specific, more confident underwriting suburban office in submarkets such as South Hill, and comfortable underwriting industrial and suburban grocery anchored retail, both of which are tied directly to the same population and consumption growth documented in the population and income sections.
Section 11Transactions and Capital Markets
Investment activity in Spokane multifamily remains well below its recent historical pace even as it shows tentative signs of picking up. ACTIV8 Real Estate reported trailing twelve month sales volume of about $124 million as of the second quarter of 2026, well below the market's roughly $189 million five year average, at a market cap rate near 6.2 percent, ranging from about 5.2 percent on premium product to roughly 6.9 percent on older value add assets, with private investors accounting for about 79 percent of volume. Kidder Mathews' Eastern Washington series showed transaction activity accelerating quarter over quarter in 2026, with 19 apartment sales totaling $76 million in the second quarter, up from 14 sales totaling $33 million in the first quarter, and identified Spokane as the most active market in Eastern Washington, accounting for eight of the region's sales in the second quarter alone, ahead of Yakima County and the Wenatchee Valley. Cap rates across the broader Eastern Washington sample compressed to 6.2 percent in the second quarter of 2026, down 30 basis points from 6.5 percent in the first quarter, continuing a two year stabilization trend that Kidder Mathews also documented in its full year 2025 report, which found an average in place cap rate of 6.30 percent for the year and showed that 52 of 75 Eastern Washington apartment sales, or 69 percent, involved complexes built before 1980, evidence of a market still dominated by value add rather than new construction trades.
Notable individual transactions illustrate the range of pricing across quality tiers. ACTIV8 Real Estate cited the 32 unit, 2025 built Dan Apartments in Spokane Valley, which traded in February 2026 for $7.3 million, or about $226,600 per unit, at a 6.0 percent cap rate while 97 percent leased, alongside the year's largest deal, the 210 unit Eagle Rock in Spokane Valley, which closed at $37.1 million, or $176,700 per unit, at a 5.2 percent cap rate, a yield the report noted penciled only because the buyer assumed the seller's low rate in place debt. A separate analysis by 43560.com found that Spokane cap rates have historically run 6 to 7 percent across most commercial asset types, noticeably wider than Seattle's 4.5 to 6.5 percent range, a gap the report attributed to thinner institutional buyer competition, smaller transaction volume, and higher vacancy in office and industrial relative to the coastal market, with the 58 unit Union Park Apartments trading at a 6 percent cap rate in February 2026 in line with historical norms even as coastal multifamily pricing has compressed below 5 percent.
The practical implication for an investor is that Spokane offers meaningfully wider cap rates than Seattle for comparable multifamily risk, that liquidity is real but thinner than in larger metros, with private buyers dominating volume, and that entry pricing today, at cap rates in the 5.2 to 6.9 percent range depending on vintage and quality, reflects a market that has already reset from any pandemic era peak rather than one still working through a valuation correction.
Section 12Taxes
Washington state levies no personal or corporate net income tax, a fact confirmed directly by the Washington State Department of Revenue, and this is a genuine advantage for both residents and investors relative to states with high income taxes. Washington instead relies heavily on retail sales tax, the business and occupation tax, and property tax, according to the state's own Legislative Guide to Washington's Tax Structure for 2026. The business and occupation tax is a gross receipts tax with no deduction for the costs of doing business, levied at 0.484 percent on retailing, wholesaling, and manufacturing activity and roughly 1.5 to 2.1 percent on services, and it is a real operating cost for property management and brokerage businesses even though it does not apply directly to rental income from real property, which carries a specific exemption under the tax code.
Property taxes in Spokane County are calculated by multiplying a parcel's assessed value by a consolidated levy rate set annually across the roughly 54 local taxing districts, according to the Spokane County Assessor's office, with the county's own worked example showing a home assessed at $100,000 paying $1,025 in tax at a levy rate of 10.25 per thousand dollars of value. A separate compilation by PropertyTaxRates.org placed Spokane County's overall effective property tax rate at 0.86 percent of value for 2026, translating to a median annual tax bill of $3,196 on a median home value of $370,500, modestly below the 0.91 percent national average. Washington also imposes a real estate excise tax on the sale of real property, due from the seller at closing, with a graduated state rate of 1.10 percent on the first $525,000 of a sale price, rising to 3.0 percent above $3,025,000, plus a local component, according to the Department of Revenue, a transaction cost investors should model into acquisition and disposition underwriting alongside recurring property tax and B&O exposure.
| Item | Value | Scope and source |
|---|---|---|
| Washington personal income tax | none | Washington State Department of Revenue |
| Spokane County effective property tax rate | ~0.86% of value | 2026, PropertyTaxRates.org |
| Median annual property tax | $3,196 | 2026, on median value $370,500 |
| Real estate excise tax, state portion | 1.10% to 3.0%, graduated | 2026, Washington Department of Revenue |
| Business and occupation tax, retailing | 0.484% of gross receipts | Washington Department of Revenue |
For an investor, the absence of a state income tax meaningfully improves after tax returns relative to high tax states, and Spokane's property tax burden, at an effective rate below the national average, is genuinely moderate by national standards, a contrast with high property tax, no income tax states such as Texas. The trade off is the business and occupation tax's gross receipts structure, which taxes revenue regardless of profitability and should be modeled explicitly for any property management or brokerage operation, along with the real estate excise tax due on every sale.
Section 13Insurance
Insurance has been the fastest rising and most disruptive cost in Spokane real estate ownership over the past three years, driven overwhelmingly by wildfire. The Spokane Journal of Business, citing data from the Washington state Office of the Insurance Commissioner, reported in May 2026 that homeowners insurance rates in Washington rose 16.6 percent in 2023 and 21.7 percent in 2024, primarily due to rising catastrophe claims including the 2023 wildfires in Medical Lake and Elk, both on Spokane's western edge, before growing a more modest 8.9 percent in 2025 and then declining slightly, by 0.5 percent, as of May 1, 2026, a weighted average across the state's twenty largest insurers that the office's spokesperson characterized as a plateau rather than a reversal. Independent rate surveys corroborate the elevated cost level: Insurify reported that Spokane homeowners pay an average of $1,455 a year for a $300,000 dwelling policy with a $1,000 deductible, while MoneyGeek separately put the Spokane area average at $1,463 a year, both notably above the cheapest available rates from carriers such as Allstate, which Insurify listed at $860 a year.
Wildfire is the specific driver reshaping the market, and it is a genuine, quantifiable risk rather than a background concern. RiskBeforeBuy's climate risk analysis, drawing on FEMA's National Risk Index, placed Spokane County's wildfire exposure in the 97th percentile nationally, part of an overall county risk score of 90 that the FEMA index characterizes as extreme, with wildfire, extreme heat, and flood identified as the dominant local perils. ZestyAI's wildfire analytics reported that 5.24 percent of Washington properties were identified as high wildfire risk heading into the 2026 fire season, and noted that on August 3, 2026, the state Office of the Insurance Commissioner issued an emergency order covering wildfire impacted zip codes statewide, running through September 30, 2026, that requires insurers to provide 45 day premium grace periods, waive late and reinstatement fees, halt policy cancellations for nonpayment, and extend nonrenewal notice periods from 60 to 120 days for property insurance and from 20 to 60 days for auto insurance. A pending state bill, Senate Bill 5928, would go further by requiring insurers to disclose a homeowner's specific wildfire risk score and the factors driving it.
| Item, Spokane | Value | Scope and source |
|---|---|---|
| Average homeowners premium, $300k dwelling | $1,455 to $1,463/yr | 2025-2026, Insurify and MoneyGeek |
| Washington premium change, 2023 | +16.6% | WA Office of the Insurance Commissioner via Spokane Journal of Business |
| Washington premium change, 2024 | +21.7% | WA Office of the Insurance Commissioner via Spokane Journal of Business |
| Washington premium change, 2025 | +8.9% | WA Office of the Insurance Commissioner via Spokane Journal of Business |
| Spokane County wildfire risk percentile | 97th nationally | FEMA National Risk Index via RiskBeforeBuy |
For a Spokane investor, wildfire insurance is not a tail risk to be waved away but a recurring underwriting line item that has already reshaped the cost structure of ownership. Non renewal risk is real for higher risk parcels, and where standard market coverage is unavailable, Washington's FAIR Plan functions as a residual market backstop, though at materially higher premiums than the standard market. Every Spokane acquisition should be quoted specifically, including a check of the parcel's wildfire exposure and its FEMA flood zone status, addressed further in the climate section below, with reserves stress tested for continued volatility even as the statewide rate of increase has slowed.
Section 14Landlord Tenant and Regulatory Environment
Washington's landlord tenant regulatory environment changed meaningfully in 2025 in a way that every Spokane owner must now underwrite. Residential tenancies are governed by the Residential Landlord Tenant Act, codified at RCW Chapter 59.18, and on May 7, 2025, House Bill 1217 took effect, establishing the state's first rent stabilization law. Under RCW 59.18.700, a landlord may not increase rent at all during the first 12 months of a tenancy, and after that, may not raise rent by more than 7 percent plus the Consumer Price Index, or 10 percent, whichever is less, once in any 12 month period, with certain exemptions defined in RCW 59.18.710. The Washington State Department of Commerce calculates the applicable cap each year using the June 12 month change in the Seattle area CPI published by the Bureau of Labor Statistics, and announced that the maximum allowable rent increase for calendar year 2026 is 9.683 percent. Landlords must also provide at least 90 days of advance written notice before any rent increase, per RCW 59.18.140, up from the 30 to 60 day notice periods common under prior law, and lot rent for manufactured or mobile homes in a park is separately capped at a 5 percent annual increase.
Washington law does not preempt local rent control the way Texas law does; instead the state itself has now enacted a statewide cap that applies uniformly, including in Spokane, which is a materially different regulatory posture than landlord friendly no cap states. A further set of just cause eviction protections under RCW 59.18.650, which will limit the grounds on which a landlord may decline to renew or may terminate a periodic tenancy, is scheduled to take effect January 1, 2028, according to the certified text of the statute, meaning Spokane owners have a defined runway before those additional protections apply but should plan lease renewal and turnover practices accordingly. On land use, Spokane has moved decisively toward more permissive infill policy: the city's Building Opportunity for Housing code, finalized in 2023 following an interim ordinance first passed in 2022, legalized duplexes, triplexes, fourplexes, townhomes, cottage housing, and small apartment buildings citywide with no maximum density on sites under two acres, and city data reported by the Spokane Journal of Business in May 2026 showed missing middle housing rising to 17 percent of all residential permits in 2025, up from 10 percent in 2024 and just 3 to 4 percent between 2020 and 2022. Washington's statewide accessory dwelling unit law, House Bill 1337, separately requires Spokane and other cities to allow up to two ADUs of at least 1,000 square feet per single family lot without an owner occupancy requirement, effective for Spokane by a June 30, 2025 compliance deadline.
The overall regulatory conclusion for an investor is mixed relative to a state like Texas. Washington offers no state income tax and an increasingly permissive infill and ADU framework that creates real value add and small scale development opportunity within the existing single family footprint, but it also now imposes a statewide rent increase cap, a genuine constraint on pricing power that did not exist before May 2025 and that must be modeled into every Spokane rent roll projection, alongside a lengthening list of tenant notice and eviction procedure requirements under RCW 59.18.
Section 15Infrastructure
Spokane's infrastructure is increasingly built around the West Plains, the area southwest of the city core anchored by Spokane International Airport, which has become the region's primary logistics and industrial growth corridor. Amazon's presence there includes a 2.6 million square foot, four story robotic fulfillment center at 10010 West Geiger Boulevard, an Amazon Air cargo facility at the airport itself, and a last mile delivery building in Airway Heights, and a new industrial park with up to 40 buildings and as much as 1.24 million square feet is in early planning on a 93 acre site near the airport, according to Spokane Journal of Business reporting. The airport itself has attracted significant public investment to support this growth: Spokane International Airport's own materials describe a $2 million state legislative appropriation to extend rail track from the Geiger Spur onto airport property, a $24 million Washington State Department of Transportation project to reconstruct two Interstate 90 interchanges serving the airport area, a $14.3 million federal BUILD grant to improve Geiger Boulevard, which serves the Amazon fulfillment center, and an $11.3 million BUILD grant that funded the airport's rail truck transload facility, completed in fall 2022.
Beyond the airport corridor, Fairchild Air Force Base anchors a separate but related logistics and federal employment base on the city's west side, and Interstate 90 remains the region's principal east west corridor, connecting Spokane to Seattle to the west and Coeur d'Alene and the broader Inland Northwest to the east. Avista Corporation, the region's investor owned electric and natural gas utility, and the Spokane River itself, which both generates hydroelectric power and defines much of the city's geography and recreational amenity through Riverfront Park and the Centennial Trail, are additional infrastructure anchors relevant to real estate value. For an investor, the infrastructure conclusion is that public and private capital are concentrating around the airport and West Plains logistics corridor, which is where industrial and distribution demand should be expected to grow fastest, while Fairchild Air Force Base and the Spokane River corridor through downtown and Kendall Yards anchor the region's employment base and its highest amenity residential locations respectively.
Section 16Climate and Physical Risks
Physical risk in Spokane is dominated by wildfire rather than by the hurricane and coastal flood exposure that defines Gulf Coast and Atlantic markets, and it is a risk that has already produced a direct, measurable impact on the local insurance market. The 2023 Medical Lake and Elk wildfires, both within Spokane County, were cited directly by Washington's insurance regulator as a driver of the 16.6 percent and 21.7 percent statewide homeowners premium increases in 2023 and 2024, according to the Spokane Journal of Business. FEMA's National Risk Index, as compiled by RiskBeforeBuy, places Spokane County in the 97th percentile nationally for wildfire exposure, and Insurify separately notes that eastern Washington accounts for roughly 70 percent of the state's annual wildfire activity, a genuinely regional concentration of risk rather than a diffuse statewide concern.
Flood risk, while less dramatic than wildfire, is not negligible. The City of Spokane's own Climate Impacts and Climate Justice Memo, dated January 14, 2025, found that 2.3 percent of the city's area sits within the 500 year floodplain and that 9.4 percent of properties citywide carry some flood risk, concentrated along the Spokane River and Latah Creek, or Hangman Creek, with winter streamflow at the river's Monroe Street gauge projected to rise 84 percent above the historical average by the end of the century as precipitation patterns shift toward more winter rain and less summer rainfall. FEMA flood zone designations most commonly found in Spokane are Zone AE and Zone X, according to FludZone's mapping analysis, and the Spokane County Flood Insurance Study calculates the Spokane River's 1 percent annual chance flood discharge at 52,000 cubic feet per second, with the county's official Flood Insurance Rate Maps last comprehensively revised in July 2010, meaning some mapped floodplain boundaries may not reflect more recent development and climate data. RiskBeforeBuy separately estimated a directional National Flood Insurance Program premium near $2,148 a year for exposed Spokane properties and an average historical flood claim in the county of $76,024.
The investor implications are direct. First, wildfire exposure should be checked parcel by parcel, not assumed uniform across the metro, given the concentration of risk on the county's western and southern edges near Medical Lake and Elk, and given that standard market non renewal is already occurring for some higher risk properties, pushing them toward the state FAIR Plan at materially higher cost. Second, flood zone status should be verified against current FEMA mapping for any property near the Spokane River or Latah Creek, with particular attention to whether a parcel's designation reflects the 2010 vintage maps or more recent development. Third, insurance costs, already elevated and only recently plateauing, should be stress tested for renewed increases given that wildfire severity and winter flood risk are both projected by the city's own climate analysis to continue rising through the century. Physical risk does not disqualify Spokane as a market, but unlike in many other Sun Belt and coastal metros, the dominant peril here is wildfire, and it must be priced explicitly rather than treated as background noise.
Section 17Neighborhoods and Submarkets
Spokane is a collection of distinct neighborhoods with meaningfully different price points, tenant profiles, and investment theses. South Hill, just south of downtown, is the market's most established and highest demand residential area, with a canopy of mature trees, a traditional grid layout, and a housing stock dominated by Craftsman bungalows and mid century homes, commanding median prices in the $590,000 to $600,000 range in early 2026 according to Farr Group NW, with particular premiums near Manito Park. Kendall Yards, a master planned, mixed use development on the north bank of the Spokane River adjacent to downtown, represents the newest and highest priced end of the market, with median prices between $645,000 and $700,000 and Realtor.com data showing a median listing price of $624,750, built around energy efficient condos and townhomes with direct pedestrian access to the Centennial Trail and Riverfront Park.
More affordable entry points sit just outside these two anchor neighborhoods. West Central, adjacent to Kendall Yards, and Emerson Garfield, with Zillow reporting typical values as low as $290,389, offer lower cost entry with renovation upside, according to Nick Briggs Realty's neighborhood investment guide, while Cliff Cannon and Latah Hangman have both seen recent one year price corrections after strong fifteen year appreciation, which the same guide characterizes as a buying opportunity for patient capital. Hillyard, Bemiss, Nevada Lidgerwood, Riverside, Chief Garry Park, and West Valley have consistently outpaced average citywide appreciation in recent years. On the investment sales side, Spokane Valley is the largest and most transaction dense multifamily submarket, with roughly 13,900 units according to ACTIV8 Real Estate, leading both absorption and sales volume in 2026, while the West Plains and Airway Heights corridor near Spokane International Airport is the fastest growing industrial and logistics submarket, anchored by Amazon's regional footprint.
The submarket conclusion for an investor is that South Hill and Kendall Yards offer stability and pricing power at the market's highest entry costs, that Emerson Garfield, West Central, and similar neighborhoods offer genuine value add and renovation upside at much lower basis, that Spokane Valley is where multifamily transaction liquidity is deepest, and that the West Plains and Airway Heights corridor is the region's clearest industrial growth story, tied directly to the infrastructure investment documented above.
Section 18Opportunities
The clearest opportunity in Spokane real estate today is multifamily positioned for the ongoing supply recovery. With new construction having fallen from a combined 3,752 units delivered in 2023 and 2024 to just 784 units in 2025, per SVN Cornerstone, and vacancy already easing from its 2024 peak toward the mid 7 percent range, investors who acquire during this period of near flat rents and cap rates still running 6 to 7 percent, wider than Seattle's 4.5 to 6.5 percent range, per 43560.com's analysis, stand to benefit as vacancy continues tightening and rents regain pricing power with a lag. Value add strategies on the pre 1980 stock that dominated 69 percent of 2025 Eastern Washington apartment sales, per Kidder Mathews, are one clear expression of this thesis in submarkets such as Spokane Valley where transaction liquidity is deepest.
Industrial and logistics anchored by the West Plains corridor and Spokane International Airport is a second opportunity, underpinned by Amazon's expanding regional footprint, a planned new industrial park near the airport of up to 1.24 million square feet, and industrial vacancy of 6.1 percent that remains below the national average despite recent heavy supply. Suburban grocery anchored retail, particularly in Spokane Valley, where vacancy has fallen to 4 to 5 percent from 12 to 15 percent a decade ago per Calibre CBI, is a third avenue tied directly to household growth. A fourth and more Spokane specific opportunity is small scale infill development: the city's 2023 missing middle housing reforms, which now permit duplexes, triplexes, fourplexes, and small apartment buildings on most residential lots with no maximum density on sites under two acres, combined with the statewide accessory dwelling unit mandate under House Bill 1337, create genuine density upside on existing single family parcels in neighborhoods such as South Hill and West Central, an opportunity that barely existed before 2022 and is only beginning to show up in permit data, at 17 percent of residential permits in 2025.
Section 19Risks
The risks are concrete and specific to Spokane's particular profile. Insurance is the first and most acute: Washington homeowners premiums rose a combined 38.3 percent across 2023 and 2024 alone, driven substantially by the 2023 Medical Lake and Elk wildfires, and while the rate of increase has slowed into 2026, Spokane County's 97th percentile national wildfire ranking under FEMA's National Risk Index means further volatility, including possible non renewals pushing properties toward the more expensive state FAIR Plan, should be underwritten as a realistic scenario rather than a tail event. The second risk is regulatory: Washington's statewide rent stabilization law, in effect since May 2025 and capping 2026 increases at 9.683 percent, is a genuine new constraint on pricing power in a market where owners were previously free to reprice leases without a statutory ceiling, and the pending just cause eviction protections taking effect in 2028 will add further procedural requirements.
The third risk is the labor market itself. Total nonfarm employment in the Spokane metro was essentially flat to down 1.0 percent year over year as of July 2026 per BLS data, meaning the demand side of the real estate market is being driven by in migration and affordability seeking relocation rather than by local job creation, a materially different growth engine than the Sun Belt metros many investors benchmark against, and one that could weaken if West Coast to Inland Northwest migration patterns shift. Sector specific risks round out the picture: downtown office vacancy near 28 to 31 percent, concentrated in older Class B and C towers, is a genuine value trap for anyone underwriting a turnaround on optimistic lease up assumptions, and the modest county level median household income jump to $86,206 in 2024, while encouraging, is a single year data point that should be confirmed in subsequent Census Bureau releases before being treated as a durable trend rather than a temporary composition effect.
Section 20Investor Implications
For an investor evaluating Spokane, the evidence supports a measured, income and affordability driven thesis rather than a growth story. The multifamily setup is genuinely constructive: vacancy has fallen from a 2024 peak near 9.2 percent to the mid 7 percent range as new construction collapsed from a combined 3,752 units in 2023 and 2024 to just 784 units in 2025, and cap rates in the 5.2 to 6.9 percent range, wider than comparable Seattle product, offer real yield premium for investors willing to accept Spokane's smaller, less liquid transaction market, where private buyers account for roughly 79 percent of volume. Industrial and suburban retail, both tied to the West Plains logistics corridor and to steady population growth, offer additional, more stable avenues, and the city's 2023 missing middle housing reforms open a genuinely new small scale infill development opportunity that did not exist in the prior cycle.
The discipline required is in underwriting insurance, regulation, and the labor market honestly rather than assuming Spokane behaves like a higher growth peer. Every Spokane acquisition should carry an explicit, parcel specific wildfire and flood risk assessment given the county's 97th percentile national wildfire ranking, an insurance quote rather than an assumed premium given the volatility of the past three years, and a rent growth assumption built around Washington's statutory cap, currently 9.683 percent for 2026 but a real ceiling nonetheless, rather than an uncapped market rate projection. Return expectations should be anchored in occupancy recovery, wide entry cap rates, and Washington's no income tax structure, not in job growth or population acceleration that the current data does not support. Investors comfortable pricing wildfire and regulatory risk explicitly are being offered a small, affordable, historically under capitalized market at yields meaningfully above coastal comparables; those unwilling to model insurance volatility and a statutory rent cap into their underwriting should look elsewhere, because in Spokane those factors are recurring line items, not tail risks.
Section 21Conclusion
Spokane at the midpoint of 2026 is a stable, affordable, moderately growing Inland Northwest market working through the tail end of an apartment supply cycle while its downtown office market continues to deteriorate. Population growth is real but modest, job growth has stalled even as unemployment ticks down, and median household income made a striking single year jump that bears watching rather than fully trusting. The apartment market's vacancy has meaningfully improved from its 2024 peak as new construction collapsed, industrial and retail fundamentals are historically tight outside the urban core, and the state's new rent stabilization law and Spokane's own missing middle housing reforms have both reshaped the regulatory backdrop since the last cycle. Against this stand genuinely elevated wildfire insurance costs, a downtown office vacancy rate pushing toward a third of inventory, and a labor market that is not currently a demand driver in its own right. Spokane rewards investors who price its Inland Northwest specific risks, wildfire above all, alongside its equally specific advantages, no state income tax, wide multifamily cap rates, and a thinning supply pipeline, with equal rigor, rather than investors who import assumptions from faster growing or more heavily insured coastal and Sun Belt markets.
Sources
- U.S. Census Bureau population estimates, Spokane metropolitan area, via Wikipedia, https://en.wikipedia.org/wiki/Spokane_metropolitan_area
- Wikipedia, Spokane County, Washington, https://en.wikipedia.org/wiki/Spokane_County,_Washington
- Wikipedia, Spokane, Washington, https://en.wikipedia.org/wiki/Spokane,_Washington
- City Population, Spokane-Spokane Valley Metropolitan Statistical Area, https://www.citypopulation.de/en/usa/metro/44060__spokane_spokane_valley/
- CensusReporter, Spokane-Spokane Valley-Coeur d'Alene, WA-ID CSA profile, http://censusreporter.org/profiles/33000US518-spokane-spokane-valley-coeur-dalene-wa-id-csa/
- Washington State Office of Financial Management, 2025 Population Trends, https://ofm.wa.gov/wp-content/uploads/sites/default/files/public/dataresearch/pop/april1/ofm_april1_poptrends.pdf
- U.S. Bureau of Labor Statistics, Spokane, WA Economy at a Glance, https://www.bls.gov/eag/eag.wa_spokane_msa.htm
- U.S. Bureau of Labor Statistics, Washington Economy at a Glance, https://www.bls.gov/eag/eag.wa.htm
- Federal Reserve Bank of St. Louis, FRED, Spokane BLS economic data series, https://fred.stlouisfed.org/tags/series?t=bls;spokane
- SVN Cornerstone, Spokane County's Largest Employers, https://svncornerstone.com/spokane-countys-largest-employers/
- ClearPoint HCO, Top Employers in Spokane, WA (2025), https://www.clearpointhco.com/top-employers-in-spokane-wa/
- Washington State Employment Security Department, Spokane County Profile, https://esd.wa.gov/jobs-and-training/labor-market-information/reports-and-research/labor-market-county-profiles/spokane-county-profile
- Greater Spokane Incorporated, Where Service Turns to Opportunity: Spokane's Military Legacy, https://greaterspokane.org/economic-development/where-service-turns-to-opportunity-spokanes-military-legacy/
- National Today, Spokane's Median Household Income Tops U.S. for First Time, https://nationaltoday.com/us/wa/spokane/news/2026/03/08/spokanes-median-household-income-tops-u-s-for-first-time/
- U.S. Census Bureau, Household Income in States and Metropolitan Areas: 2024, https://www.census.gov/library/publications/2025/acs/acsbr-025.html
- CensusFlow, Spokane, WA Population and Demographics, https://censusflow.com/washington/spokane/
- ACTIV8 Real Estate, Spokane Multifamily Market Report Q2 2026, https://www.activ8re.com/spokane-multifamily-market-report-q2-2026/
- ACTIV8 Real Estate, Spokane Office Market Report Q1 2026, https://www.activ8re.com/spokane-office-market-report-q1-2026/
- SVN Cornerstone, Spokane County Multifamily Market Update, June 2026, https://svncornerstone.com/spokane-county-multifamily-market-update-june-2026/
- Kidder Mathews, Q3 2026 Report on Eastern Washington Apartment Market, https://kidder.com/trend-articles/kidder-mathews-releases-q3-2026-report-on-eastern-washington-apartment-market/
- Kidder Mathews, Q1 2026 Report on Eastern Washington Apartment Market, https://kidder.com/trend-articles/kidder-mathews-releases-q1-2026-report-on-eastern-washington-apartment-market/
- Kidder Mathews, Q2 2026 Eastern Washington Apartment Market Dynamics, https://kidder.com/trend-articles/q2-2026-eastern-washington-apartment-market-dynamics/
- 43560.com, Cap Rate Trends 2026: Seattle vs. Spokane vs. Boise, https://43560.com/market-trends/cap-rate-trends-across-seattle-spokane-and-boise-where-value-is-shifting-in-2026/
- Redfin, Spokane, WA Housing Market, https://www.redfin.com/city/17154/WA/Spokane/housing-market
- Redfin, Spokane County, WA Housing Market, https://www.redfin.com/county/3100/WA/Spokane-County/housing-market
- Zillow, Spokane, WA Home Values, https://www.zillow.com/home-values/20604/spokane-wa/
- The Collection Spokane, Spokane Housing Market 2026: What It Means for Your Move, https://thecollectionspokane.com/blog/what-spokanes-market-means-for-your-next-home-move
- Spokane Journal of Business, Challenges downtown push office vacancy rate up, https://www.spokanejournal.com/articles/18466-high-office-vacancy-challenges-downtown-core
- Spokane Journal of Business, Spokane commercial real estate at midyear: holding steady, https://www.spokanejournal.com/articles/18481-spokane-commercial-real-estate-at-midyear-holding-steady
- Calibre CBI, Quarterly Eastern Washington CRE Market Intelligence, https://www.calibrecbi.com/cre-inspector-insights/quarterly-eastern-washington-cre-market-intelligence
- Spokane County, WA, Calculating Your Taxes, https://www.spokanecounty.gov/229/Calculating-Your-Taxes
- Spokane County Tax Rates, effective January 1, 2026, https://www.spokanecounty.gov/DocumentCenter/View/60078/Spokane-County-Tax-Rates?bidId=
- PropertyTaxRates.org, Spokane County Property Tax Rate, Washington, 2026, https://propertytaxrates.org/counties/washington/spokane-county/
- Washington State Department of Revenue, Income Tax, https://dor.wa.gov/taxes-rates/income-tax
- Washington State Department of Revenue, Real Estate Excise Tax, https://dor.wa.gov/taxes-rates/other-taxes/real-estate-excise-tax
- Washington State, A Legislative Guide to Washington's Tax Structure, 2026, https://fiscal.wa.gov/Revenue/2026GuideToWashingtonStateTaxStructure.pdf
- Insurify, Best Spokane Homeowners Insurance Quotes (2026), https://insurify.com/homeowners-insurance/washington/spokane/
- MoneyGeek, Average Cost of Home Insurance in Washington (2026), https://www.moneygeek.com/insurance/homeowners/average-cost-home-insurance-washington/
- Spokane Journal of Business, Rising from the ashes: Home insurance rates show signs of steadying, https://www.spokanejournal.com/articles/18278-wildfire-risks-drive-coverage-costs-higher
- ZestyAI, What Spokane 2026 Tells Carriers About Wildfire Exposure, https://zesty.ai/resource/what-spokane-2026-tells-carriers-about-wildfire-exposure
- RiskBeforeBuy, Spokane, WA Climate Risk Report, https://www.riskbeforebuy.com/city/washington/spokane
- City of Spokane, Spokane Climate Impacts and Climate Justice Memo, January 14, 2025, https://static.spokanecity.org/documents/planspokane/climate-planning/spokane-climate-impacts-and-climate-justice-memo-2025-03-07.pdf
- FludZone, Spokane, WA Flood Zones, https://www.fludzone.com/flood-zones/washington/spokane
- Spokane County Flood Insurance Study, https://static.spokanecity.org/documents/projects/floodplain/spokane-county-flood-insurance-study.pdf
- Washington State Department of Commerce, HB 1217 Landlord Resource Center, https://www.commerce.wa.gov/housing-policy/hb1217-landlord-resource-center/
- Washington State Department of Commerce, Commerce announces 9.683% rent cap for 2026, https://www.commerce.wa.gov/commerce-announces-9-683-rent-cap-for-2026/
- Washington State Office of the Attorney General, Landlord-Tenant, https://www.atg.wa.gov/landlord-tenant
- Washington State Legislature, RCW Chapter 59.18, Residential Landlord-Tenant Act, https://app.leg.wa.gov/Rcw/default.aspx?cite=59.18&full=true&pdf=true
- City of Spokane, 2026 Rent Reasonableness and Fair Market Rent Policy, https://static.spokanecity.org/documents/chhs/plans-reports/planning/2026-rent-reasonableness-and-fmr.pdf
- Tenanture, Spokane County, WA Fair Market Rent 2026, https://tenanture.com/fair-market-rent/wa/spokane-county
- Spokane Journal of Business, Industrial park planned near Spokane International Airport, https://www.spokanejournal.com/articles/17338-industrial-park-planned-near-spokane-international-airport
- Spokane International Airport, Development Site, https://spokaneaero.com/development-site/
- Farr Group NW, Is Spokane WA Safe? A 2026 Real Estate and Infrastructure Guide, https://www.farrgroupnw.com/blog/is-spokane-safe/
- Nick Briggs Realty, Best Spokane Investment Neighborhoods Guide, https://www.nickbriggsrealty.com/post/best-neighborhoods-to-invest-in-spokane
- Spokane Journal of Business, Missing middle housing gains traction in Spokane, https://www.spokanejournal.com/articles/18294-missing-middle-housing-gains-traction-in-spokane
- The Urbanist, Spokane's Permanent Middle Housing Rules Should Set a Statewide Standard, https://www.theurbanist.org/spokanes-permanent-middle-housing-rules-should-set-a-statewide-standard/
- ADUZoning.org, Spokane ADU Rules (2026), https://www.aduzoning.org/adu-rules/spokane-wa/