In brief · summary: Hawaii
Hawaii State Real Estate Market Review
Section 01Executive Summary
Hawaii combines very high housing costs, modest but stable employment, and a slowly declining population, all within a small island economy that is highly exposed to tourism and climate risk. Public data that can be accessed in this environment provide a clear picture of macro trends in population, income, employment, and house prices, but there is little state level transparency on rents, multifamily vacancy, and commercial real estate performance. Investors must therefore treat this review as a macro and qualitative frame and supplement it with proprietary local data when underwriting specific assets.
World Population Review reports that Hawaii’s total population is 1,430,688 persons in 2026, with an average population density of 131 residents per square mile and a population rank of 40 among the states. The same source shows that statewide population peaked at 1,451,130 in 2020 and has edged down since, leaving the 2026 count 20,442 persons below the 2020 figure. The Federal Reserve Bank of St. Louis resident population series, which measures persons in thousands, reinforces this pattern, indicating values of 1,451.130 thousand in 2020, 1,446.909 thousand in 2021, 1,437.812 thousand in 2022, 1,434.950 thousand in 2023, 1,434.952 thousand in 2024, and 1,432.820 thousand in 2025.
Despite this mild population decline, income levels are high in absolute terms. The Federal Reserve per capita personal income series for Hawaii shows annual values of 57,030 dollars in 2020, 61,269 dollars in 2021, 63,296 dollars in 2022, 67,571 dollars in 2023, 71,573 dollars in 2024, and 76,592 dollars in 2025. World Population Review, drawing on Census and American Community Survey data, reports an average per capita income of 52,424 dollars, a median household income of 98,317 dollars, and a statewide poverty rate of 9.97 percent. These figures indicate an income structure that is relatively high in dollar terms but still features a meaningful share of lower income households given the state’s elevated cost of living.
On the labor side, the Bureau of Labor Statistics Hawaii table shows that as of June 2026 the state’s civilian labor force was a preliminary 690.4 thousand persons, with 672.5 thousand employed and 17.9 thousand unemployed, producing a statewide unemployment rate of a preliminary 2.6 percent. Total nonfarm employment was a preliminary 643.0 thousand jobs in June 2026, with a twelve month change of a preliminary 0.5 percent, indicating that job growth is modest but positive. Leisure and hospitality, education and health services, and government are among the largest sectors by employment.
For housing, the Federal Housing Finance Agency all transactions house price index for Hawaii, reported by the Federal Reserve, increased from 640.09 in the first quarter of 2020 to 950.52 in the first quarter of 2026 on a scale where the first quarter of 1980 equals 100. This represents very strong house price appreciation over six years. For supply, the Federal Reserve permit series shows that private housing units authorized by building permits in Hawaii totaled 324 units in June 2024, 263 units in June 2025, and 306 units in June 2026. Redfin reports that there are currently 9,239 homes for sale statewide, with a median list price of 750,000 dollars and an average price of 639 dollars per square foot, and its table of popular cities shows figures such as 585,000 dollars and 668 dollars per square foot for Honolulu and 1,625,000 dollars and 862 dollars per square foot for Kailua, underscoring the high cost of for sale housing in key markets.
Public, machine readable data on statewide rents, multifamily vacancy, commercial vacancy and rent levels, and capitalization rates are not available in this environment. The U.S. Department of Housing and Urban Development provides Fair Market Rent data for Hawaii counties and metropolitan areas through large Excel and comma separated files, but these files are not practically parseable here. As a result, this review treats rents, vacancy, and cap rates qualitatively and does not assign numerical values where no reliable public figures can be extracted.
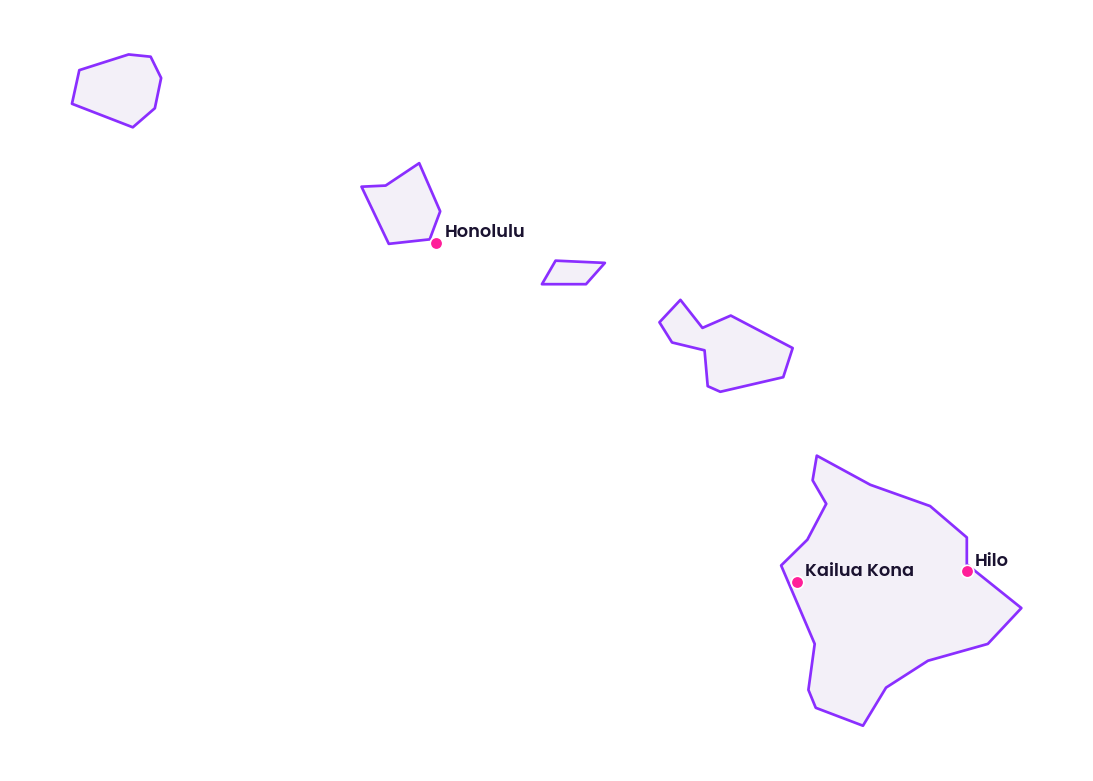
Section 02Population and Migration
World Population Review indicates that Hawaii’s 2026 population is 1,430,688 residents, with a population density of 131 persons per square mile and a population rank of 40 among the states. The same source reports that Hawaii’s population was 1,364,004 in 2010 and 1,451,130 in 2020, showing that the state grew over the 2010s but has experienced modest net out migration or natural decrease since 2020.
The Federal Reserve resident population series, which reports persons in thousands, provides a consistent annual measure. It records 1,451.130 thousand in 2020, 1,446.909 thousand in 2021, 1,437.812 thousand in 2022, 1,434.950 thousand in 2023, 1,434.952 thousand in 2024, and 1,432.820 thousand in 2025. These data indicate that Hawaii’s population decreased by 18.310 thousand persons between 2020 and 2025 in that series, reinforcing the World Population Review finding that the state has shifted from growth to slight decline.
World Population Review also provides a breakdown of population by race based on Census and American Community Survey data. It reports that the racial composition of Hawaii includes 37.27 percent Asian, 26.05 percent identifying as two or more races, 22.51 percent White, and 10.31 percent Native Hawaiian or Pacific Islander, with smaller shares for Black or African American, other races, and Native American residents. In terms of counts, the site lists 538,807 Asian residents, 376,533 residents identifying as two or more races, 325,356 White residents, and 149,030 Native Hawaiian or Pacific Islander residents. This diverse composition is a distinctive feature of the state’s demographic profile.
At the county level, World Population Review notes that Honolulu County is home to approximately 979,000 residents and has experienced a decline of about 3.3 percent since 2020, while Hawaii County has grown by about 4.7 percent to reach roughly 210,000 residents. Kalawao County remains extremely small, with just 81 residents. The neighbor island counties otherwise show smaller mixed changes rather than the concentrated decline seen in Honolulu County.
Direct Census QuickFacts tables for Hawaii are not accessible in this environment because access is blocked by a security service, so this review relies on the combination of World Population Review and the Federal Reserve population series to describe population levels and trends. The key takeaway for investors is that Hawaii’s population is no longer expanding and may be slowly shrinking in aggregate, with growth shifting toward some neighbor islands while Honolulu County declines. This dynamic can influence long term demand for housing and commercial space across different islands and submarkets.
Section 03Jobs and Economic Anchors
The Bureau of Labor Statistics Hawaii table provides a detailed snapshot of statewide labor market conditions for the first half of 2026. According to that table, Hawaii’s seasonally adjusted civilian labor force was 688.0 thousand persons in January 2026 and a preliminary 690.4 thousand in June 2026. Employment was 672.7 thousand in January and a preliminary 672.5 thousand in June, while unemployment increased modestly from 15.3 thousand to a preliminary 17.9 thousand over the same period. The unemployment rate, measured as a percentage and seasonally adjusted, rose from 2.2 percent in January to a preliminary 2.6 percent in June 2026.
Total nonfarm wage and salary employment in Hawaii was 643.3 thousand jobs in January 2026 and a preliminary 643.0 thousand in June 2026, with twelve month changes of negative 0.1 percent in January, 0.3 percent in February, negative 0.2 percent in March, 0.3 percent in April, 0.6 percent in May, and a preliminary 0.5 percent in June. This pattern indicates that overall job growth is positive but muted.
Sector breakdowns highlight the structure of Hawaii’s economy. In June 2026, mining, logging, and construction employment was a preliminary 41.6 thousand jobs, with a twelve month change of a preliminary 4.5 percent, suggesting that construction activity is expanding after prior softness. Manufacturing employment was a preliminary 12.8 thousand jobs, with a twelve month change of a preliminary negative 1.5 percent, indicating a small and slightly contracting manufacturing base.
Trade, transportation, and utilities employment was a preliminary 115.6 thousand jobs in June 2026, with a twelve month change of a preliminary negative 0.3 percent. Information employment was a preliminary 7.0 thousand jobs, with a twelve month change of zero percent. Financial activities employment was a preliminary 26.3 thousand jobs, with a twelve month change of a preliminary negative 2.6 percent. Professional and business services had a preliminary 72.5 thousand jobs, with a twelve month change of a preliminary 0.4 percent. Education and health services accounted for a preliminary 94.1 thousand jobs, with a twelve month change of a preliminary 3.6 percent, making it one of the faster growing sectors.
Leisure and hospitality, which captures much of the tourism industry that anchors real estate demand in Hawaii, had a preliminary 121.5 thousand jobs in June 2026, with a twelve month change of a preliminary 1.3 percent. Government employment was a preliminary 124.9 thousand jobs, with a twelve month change of a preliminary negative 1.4 percent.
The state’s Department of Business, Economic Development and Tourism, through its Research and Economic Analysis Division, describes Hawaii’s economy as one that depends heavily on tourism and maintains detailed statistics on tourism, labor, energy, and demographic indicators. While the accessible content from that division does not provide specific numeric values, its role as the state’s statistical arm confirms that tourism and related services remain central to Hawaii’s economic base.
For real estate investors, these sector patterns imply that demand for space is tied to tourism, education and health services, government, and construction. Leisure and hospitality employment, in particular, supports hotel, resort, and vacation rental demand, while education and health services and government generate relatively stable demand for housing and some commercial space even during economic cycles.
Section 04Income
Income levels in Hawaii can be examined through both federal macro statistics and household level survey estimates. The Federal Reserve per capita personal income series, which is derived from Bureau of Economic Analysis data, provides a long time series of statewide income. It records 57,030 dollars in 2020, 61,269 dollars in 2021, 63,296 dollars in 2022, 67,571 dollars in 2023, 71,573 dollars in 2024, and 76,592 dollars in 2025. Between 2020 and 2025, per capita personal income in Hawaii increased by 19,562 dollars, a substantial nominal gain over five years. This growth reflects a combination of wage and salary income, investment income, and government transfers in the state’s small but high cost economy.
World Population Review, drawing on American Community Survey and other Census Bureau data, reports complementary household level income figures. It notes that Hawaii’s average per capita income is 52,424 dollars, that the median household income is 98,317 dollars, and that the poverty rate is 9.97 percent statewide. The site further details that married families have a median income of 129,923 dollars and an average income of 159,570 dollars, while all families have a median income of 115,643 dollars and an average income of 143,714 dollars. Nonfamily households have a median income of 58,149 dollars and an average income of 80,680 dollars.
These figures show that Hawaii has high incomes in dollar terms compared with many states, especially among married families and dual earner households, but that nonfamily households and some single earner households have much lower incomes relative to the state’s cost structure. The nearly ten percent poverty rate underscores that a meaningful share of residents struggle with affordability despite aggregate income gains. For investors, this income distribution implies a bifurcated housing demand profile, combining strong capacity to pay at the upper end of the market with acute affordability challenges for lower and middle income households that support demand for subsidized and workforce housing.
Section 05Housing and Multifamily
Statewide house price trends in Hawaii can be tracked using the Federal Housing Finance Agency all transactions house price index for the state, reported by the Federal Reserve. This index measures changes in single family home values based on both purchase and refinance mortgages and is scaled so that the first quarter of 1980 equals 100. It stood at 640.09 in the first quarter of 2020, 662.33 in the first quarter of 2021, 797.02 in the first quarter of 2022, 857.44 in the first quarter of 2023, 908.41 in the first quarter of 2024, and 950.52 in the first quarter of 2026.
Between the first quarter of 2020 and the first quarter of 2026, the statewide index increased from 640.09 to 950.52, a rise of 310.43 index points. This large increase reflects a multi year period of intense housing demand and limited supply, especially during and after the pandemic years, with particularly rapid appreciation between 2021 and 2022.
Multifamily housing is not directly measured in this index, but the single family price environment sets the backdrop for rental and condo markets. High for sale prices tend to push some households into renting, either by preference or necessity, and also influence replacement cost and development feasibility for new multifamily projects.
On the institutional side, the Hawaii Housing Finance and Development Corporation is the state’s primary housing finance and development agency and operates as a division of the Department of Business, Economic Development and Tourism. Its accessible content emphasizes its role in supporting housing development and focuses on language access, and it does not provide numeric counts of units financed or dollars deployed. This means that while the agency clearly plays a central role in affordable and workforce housing, public numeric summaries of its pipeline and impacts are not available in this environment.
Overall, the combination of strong house price appreciation and limited land availability on each island suggests that both ownership and rental housing in Hawaii are structurally expensive. For multifamily investors, this can support rent levels and long term capital values but also increases exposure to affordability constraints and policy responses that may seek to expand subsidized housing or regulate parts of the rental market.
Section 06Rents
Public, machine readable data on statewide rents in Hawaii are limited. The U.S. Department of Housing and Urban Development’s Fair Market Rents portal provides detailed Fair Market Rent values for each county and metropolitan area in the United States, including Hawaii counties and the Urban Honolulu metropolitan statistical area. However, the 2026 Fair Market Rent data for Hawaii are presented in large Excel and comma separated value files that are too large and complex to parse in this environment. The documentation notes that the 2026 files incorporate American Community Survey data and that the Urban Honolulu values were corrected in an update dated August 29, 2025, but it does not expose specific dollar rents in a simple text table here. A statewide real estate data aggregator sometimes used for such figures returns no Hawaii page, so no statewide rent metrics can be drawn from that source either.
Private data providers such as CoStar, RealPage, and Yardi Matrix collect detailed apartment rent data for Hawaii, including class level rents and submarket breakdowns, but their datasets are subscription based and not publicly accessible. Consumer facing platforms such as Zillow and Apartment List publish rent reports for some Hawaii metros, but relevant pages either present only interactive content or are blocked from machine reading here.
As a result, this review cannot provide numerical values for average or median asking rents, effective rents, rent per square foot, rent growth rates, or rent to income ratios for Hawaii’s multifamily market. The qualitative consensus, consistent with high house prices and limited land supply, is that rents are elevated relative to national averages and that rent burdens for lower income households are significant, but these observations cannot be quantified from the public data available in this environment. Investors should rely on property level rent rolls, local broker surveys, and proprietary rental databases when evaluating Hawaii multifamily assets.
Section 07Vacancy
There is no publicly accessible, statewide time series of rental or homeowner vacancy rates for Hawaii that can be reliably extracted here. The U.S. Census Bureau’s American Community Survey publishes rental vacancy rates and homeowner vacancy rates for states and counties, but direct access to those tables through Census QuickFacts or other web interfaces is blocked in this environment by a security service, as evidenced by the error page returned when attempting to load Hawaii QuickFacts.
Similarly, there is no public statewide series for multifamily vacancy by class or for office, industrial, or retail vacancy rates that can be accessed through federal data sources. Those metrics are generally compiled by private research firms such as CoStar and CBRE, which do not provide open data tables for Hawaii vacancy.
Because of these constraints, this review does not present numerical estimates of vacancy rates in Hawaii’s rental housing or commercial real estate markets. Vacancy must therefore be treated qualitatively and analyzed using proprietary datasets, local brokerage reports, and property specific leasing histories when making investment decisions.
Section 08Supply Pipeline
The Federal Reserve permit series tracks the number of private housing units authorized by building permits each month in Hawaii. This series includes both single family and multifamily units and provides a useful indicator of statewide residential construction activity. It shows 324 units authorized in June 2024, 263 units in June 2025, and 306 units in June 2026.
These figures show that permit volumes, while modest in absolute terms, remain active and variable from year to year. The 324 units authorized in June 2024 declined to 263 units in June 2025, then increased again to 306 units in June 2026. Across the full spans of 2024 and 2025, monthly permit counts ranged widely, from a low near 133 units in the softest month to a high above 430 units in the strongest, reflecting both seasonality and project specific timing in a small market.
Because this series aggregates all private housing units, it does not distinguish between single family homes, small multifamily projects, and larger apartment or condo buildings. Nor does it indicate where within the state the permits are issued. Nevertheless, in a state with roughly 1.4 million residents and a constrained land base, a few hundred units of new permitting per month can meaningfully affect local supply in specific submarkets, especially on neighbor islands.
City level planning and permitting portals, as well as the pipeline and financing data of the Hawaii Housing Finance and Development Corporation, would be required to quantify the mix of affordable and market rate projects, unit counts by island, and the timing of major deliveries. Those details are not available in numeric form in this environment, so investors must obtain them directly from local government and agency sources or proprietary data providers.
Section 09Single Family Homes
Single family home market conditions in Hawaii can be inferred from both the statewide house price index and city level for sale listing data. As noted earlier, the Federal Housing Finance Agency’s all transactions house price index for Hawaii increased from 640.09 in the first quarter of 2020 to 950.52 in the first quarter of 2026, indicating significant appreciation in single family home values over six years.
Redfin’s Hawaii state page reports that there are currently 9,239 homes for sale statewide, with a median list price of 750,000 dollars and an average price of 639 dollars per square foot. It also provides average list prices, average price per square foot, and average days on market for popular cities, based on current for sale listings that include single family homes, condos, and townhouses. In Honolulu, the largest city, the average list price is 585,000 dollars, the average price is 668 dollars per square foot, and homes sit an average of 94 days on market. Kailua Kona on Hawaii Island shows an average list price of 662,000 dollars, 606 dollars per square foot, and 73 days on market. Kailua, an affluent community on Oʻahu, shows an average list price of 1,625,000 dollars, 862 dollars per square foot, and 65 days on market. Hilo shows an average list price of 590,000 dollars, 386 dollars per square foot, and 109 days on market.
These figures demonstrate how expensive for sale housing is across different parts of Hawaii. Honolulu’s average list price of 585,000 dollars and average of 668 dollars per square foot point to a high cost urban market, especially given that these averages likely include smaller condo units as well as houses. Kailua exhibits much higher figures, reflecting its status as an affluent, supply constrained coastal submarket. Kailua Kona and Hilo offer somewhat lower price per square foot but still show average list prices in the high 500,000 to mid 600,000 dollar range.
Redfin’s city table does not provide statewide median sale prices, months of supply, or year over year price changes in the extractable text, so this review cannot state those metrics, and it does not break out single family homes from condos and townhouses in the summary data. Nonetheless, the city list and the statewide median list price of 750,000 dollars demonstrate that typical transaction sizes for for sale homes in Hawaii are high compared with many mainland markets, even outside the most expensive neighborhoods.
For single family rental investors, these high acquisition costs mean that yields can be thin if rents do not keep pace with prices and operating expenses. At the same time, the high cost of ownership can support a sizable renter population among households that have strong incomes but are priced out of buying. Investors evaluating single family rentals in Hawaii must build property specific models using local rent data, property tax and insurance costs, and realistic maintenance and capital expenditure assumptions.
Section 10Commercial Real Estate and Retail Centers
There is no statewide, publicly accessible dataset for Hawaii that provides detailed numerical information on office, industrial, and retail inventory, vacancy rates, asking rents, or capitalization rates. Such metrics are typically tracked by private research firms, brokerage houses, and property level databases, which are not open sources.
However, the sector composition of Hawaii’s employment offers insight into the demand base for commercial real estate. The Bureau of Labor Statistics Hawaii table shows that in June 2026 trade, transportation, and utilities accounted for a preliminary 115.6 thousand jobs, professional and business services accounted for a preliminary 72.5 thousand jobs, and financial activities accounted for a preliminary 26.3 thousand jobs. These sectors collectively support demand for office, retail, and logistics space. Leisure and hospitality, with a preliminary 121.5 thousand jobs in June 2026, is particularly important for hotel, resort, restaurant, and entertainment space, reflecting the state’s heavy reliance on tourism.
Retail in Hawaii often centers on grocery anchored neighborhood shopping centers, tourist oriented retail in resort areas, and urban retail in Honolulu. Industrial and logistics space is constrained by land availability and the need to support imports and inter island distribution. Office space is concentrated in Honolulu, with additional local office and medical office nodes on neighbor islands.
Because vacancy and rent levels are not provided in public data, this review cannot quantify, for example, the office vacancy rate in Honolulu or the average industrial rent per square foot in key submarkets. Investors must obtain such figures from local brokerage research or proprietary datasets. Qualitatively, the combination of limited land, high construction costs, and a stable if modestly growing employment base suggests that well located commercial assets can maintain occupancy and pricing power but are sensitive to tourism cycles and long term shifts in demand, such as remote work for office space.
Section 11Transactions and Capital Markets
Public sources used in this review do not provide a statewide time series for the number or dollar volume of commercial or multifamily property transactions in Hawaii, nor do they provide aggregated capitalization rates by asset class. County property records list individual transactions, but those records are not summarized in accessible statewide tables here.
The Federal Housing Finance Agency house price index indirectly reflects the residential ownership capital market. The rise in the index from 640.09 in the first quarter of 2020 to 950.52 in the first quarter of 2026 indicates that capital has bid up single family home values during a period of low interest rates followed by higher rates, suggesting strong underlying demand and constrained supply.
For income producing properties, capitalization rates and deal activity are shaped by local investors, institutional players, and debt markets, but accurate measures for Hawaii require proprietary transaction databases and appraisal data. This review therefore does not state numerical cap rates or transaction volumes and instead emphasizes that Hawaii generally trades at low yields and high price levels relative to many mainland markets, consistent with its status as a small, supply constrained, and lifestyle driven market.
Section 12Taxes
The State of Hawaii Department of Taxation’s official website provides information on tax announcements, tax law changes from recent legislative sessions, and topics such as pass through entity taxation and rental collection agreements. It highlights that, for taxable years beginning after December 31, 2022, partnerships and S corporations may elect to pay Hawaii income taxes at the entity level and that eligible members may claim a credit for their share of pass through entity taxes paid. It also notes requirements for persons authorized to collect rent on behalf of owners of real property and transient accommodations in Hawaii to file specific rent collection forms electronically.
The Department of Taxation site does not present a simple numeric table of state income tax brackets, general excise tax rates, or other state level tax rates in the extractable content. Property tax administration in Hawaii is largely handled at the county level, and county property tax rate tables are not accessible in this environment in a consolidated statewide form. As a result, this review cannot state exact property tax rates, effective tax percentages, or income tax brackets for Hawaii.
For real estate investors, it is important to understand that Hawaii applies a general excise tax system rather than a conventional retail sales tax and that property taxes, transient accommodations taxes, and income taxes can all affect investment returns. Precise rate information and potential incentives must be obtained from current state and county tax publications and professional advisors when underwriting deals.
Section 13Insurance
Hawaii’s geographic position in the central Pacific exposes it to a range of natural hazards, including hurricanes, tropical storms, heavy rainfall, flooding, and in some areas volcanic and seismic risks. The Federal Emergency Management Agency’s Flood Maps overview explains that floods can occur almost anywhere, not only near rivers or coasts, and that flood maps show how likely it is for an area to flood. It notes that any place with at least a one percent annual chance of flooding is considered high risk and has at least a one in four chance of flooding during a thirty year mortgage, and it emphasizes that there is no such thing as a no risk zone, only areas with lower or moderate risk.
In Hawaii, coastal and low lying areas on each island may fall within high risk flood zones, while inland and higher elevation areas face lower flood risk but may still be affected by intense rainfall events. The absence of property specific risk data in this environment means that this review cannot map particular neighborhoods or parcels to flood zones, but the federal framework clarifies why lenders and insurers may require flood insurance and how risk assessments feed into premiums.
There is no public statewide dataset here that reports average property insurance premiums per unit or per square foot for Hawaii residential or commercial properties, nor is there a public series of year over year premium changes. Given the state’s exposure to natural hazards and its small, isolated insurance market, anecdotal evidence suggests that premiums can be high and volatile, particularly in coastal and high risk areas. Investors must obtain property specific insurance quotes and account for potential future premium increases when underwriting assets in Hawaii.
Section 14Landlord Tenant and Regulatory Environment
Public sources accessed for this review do not provide a consolidated numeric or tabular summary of Hawaii’s landlord tenant laws, eviction rates, or rent regulation measures. State landlord tenant statutes and county ordinances govern issues such as notice requirements, security deposits, habitability standards, and procedures for eviction, but those legal texts are not summarized in the data oriented sources used here.
Hawaii does not have a statewide system of rent control analogous to some mainland jurisdictions, but local ordinances and state laws can affect issues such as short term rentals, transient accommodations, and tenant protections. The Department of Taxation’s emphasis on rental collection agreements and taxation of transient accommodations underscores that rental activity, including vacation rentals, is closely monitored from a tax perspective.
Because this review cannot quote specific statutory provisions or numerical eviction statistics from public datasets, it treats the regulatory environment qualitatively. Investors should expect an environment that balances property rights with tenant protections and that contains specialized rules for transient accommodations and short term rentals in tourist areas. Legal counsel familiar with Hawaii’s state and county laws is essential for understanding regulatory risk in specific investments.
Section 15Infrastructure
There is no statewide quantitative dataset in this environment that lists Hawaii’s lane miles of road, bridge counts, port capacities, or public transit ridership. However, the state’s infrastructure context is well understood qualitatively. Hawaii’s economy and real estate markets depend heavily on ports and airports that connect each island to the mainland and to international destinations, as well as on intra island road networks that link residential areas, employment centers, and tourist destinations.
Because land is limited and transportation corridors are constrained by topography, congestion can be significant in urban areas such as Honolulu, and infrastructure investments or disruptions can have outsized effects on real estate values. The absence of numerical infrastructure indicators in the accessible public data means this review cannot rank submarkets based on commute times or infrastructure capacity, but investors should consider proximity to airports, ports, major roads, and key amenities when evaluating properties.
Section 16Climate and Physical Risks
Hawaii faces a complex array of climate and physical risks, including temperature and precipitation changes, sea level rise, coastal erosion, hurricanes and tropical storms, heavy rainfall and flooding, and in some areas volcanic and seismic activity. The National Centers for Environmental Information’s Climate at a Glance statewide time series tool provides an interactive interface for selecting state, location, parameter, time scale, and period for climate data, but the interface accessible here displays only selection fields without numeric series for Hawaii. As a result, this review cannot present specific trends in statewide average temperatures or precipitation from that source.
The Federal Emergency Management Agency’s Flood Maps overview, as discussed earlier, clarifies that high risk flood zones are defined by a one percent annual chance of flooding and that such zones have at least a one in four chance of flooding during a thirty year mortgage. In Hawaii, many coastal and low lying areas fall within such zones, especially around bays, river mouths, and low coastal plains.
The combination of sea level rise, coastal erosion, and storm events poses particular risk to oceanfront and near ocean properties, including some of the most valuable residential, resort, and commercial assets in the state. Inland and higher elevation properties may be less exposed to coastal hazards but can still face heavy rainfall events and other hazards.
Because numerical projections of sea level rise and storm frequency for specific Hawaii locations are not available in the accessible public datasets used here, this review emphasizes qualitative risk awareness rather than quantitative risk measures. Investors should incorporate property specific climate risk assessments, including flood zone mapping and resilience measures, into their due diligence.
Section 17Opportunities
Several opportunity themes emerge from the available data for Hawaii. First, income levels are high in dollar terms, with per capita personal income reaching 76,592 dollars in 2025 according to the Federal Reserve and median household income reaching 98,317 dollars according to World Population Review. These income levels support demand for high quality housing, retail, and amenities, particularly among higher income households and visitors.
Second, the statewide house price index’s rise from 640.09 in the first quarter of 2020 to 950.52 in the first quarter of 2026 indicates substantial appreciation in residential property values over six years. While past appreciation does not guarantee future performance, it reflects the pricing power of a small, supply constrained market with strong amenity value.
Third, the labor market shows low unemployment, with a preliminary 2.6 percent unemployment rate in June 2026 and a preliminary total nonfarm employment level of 643.0 thousand jobs. Leisure and hospitality, education and health services, and construction all show positive twelve month job growth in June 2026, supporting demand for hospitality, multifamily, and related commercial assets.
Finally, city level listing data from Redfin show high price points in key markets, with average list prices ranging from 585,000 dollars in Honolulu to 1,625,000 dollars in Kailua and prices per square foot ranging from 386 dollars in Hilo to 862 dollars in Kailua, against a statewide median list price of 750,000 dollars. These figures illustrate the high cost of housing in key markets, but they are not indicative of achievable rental or sale revenues for any specific property, and no particular return is assured. The observations in this section are general and educational, are not projections, forecasts, or assurances of any particular return, yield, occupancy, rent level, or appreciation, and any specific investment must be evaluated on its own facts.
Section 18Risks
Hawaii also presents significant risks for real estate investors. The most immediate macro risk is the state’s modest population decline, as shown by both World Population Review and the Federal Reserve population series. A shrinking or stagnant population can limit long term demand growth, especially if out migration is concentrated among working age residents.
Economic concentration is another risk. The Bureau of Labor Statistics data show that leisure and hospitality accounts for over 120 thousand jobs and that many other sectors, including trade, transportation and utilities, and professional and business services, are linked to tourism and service activities. Shocks to tourism, whether from global recessions, pandemics, or changes in travel patterns, can quickly affect occupancy and cash flows in hotels, resorts, vacation rentals, and related segments.
High price levels and construction costs also pose risks. The house price index’s strong run up and the high average list prices in key cities mean that investors are often buying into a market at elevated valuations. Without detailed public data on rents, vacancy, and cap rates, it can be difficult to assess whether current prices are fully supported by income streams, increasing the risk of overpayment.
Climate and physical risks, including flooding, storms, and coastal erosion, are particularly acute in Hawaii. The federal flood risk framework indicates that many coastal areas have a one in four chance of flooding over a thirty year mortgage term. These risks can raise insurance costs, require significant capital expenditures for resilience, and affect long term asset viability.
Finally, data constraints themselves are a risk. The lack of publicly accessible, machine readable data on rents, vacancy, cap rates, and infrastructure means that investors who do not have access to proprietary data or strong local partnerships may make decisions based on incomplete information. Real estate investments are speculative, are subject to market, financing, liquidity, tax, insurance, and physical hazard risks, and can result in the loss of some or all of an investor's invested capital, including the possible loss of principal.
Section 19Investor Implications
For United States accredited investors, Hawaii offers a combination of high income demand, strong historical appreciation, and scarcity that can support long term value, but also a set of structural risks that require careful underwriting. The available public data indicate that the state’s population is slightly declining, that per capita and household incomes are high in dollar terms, that unemployment is low and employment growth modest but positive, and that house prices have appreciated substantially since 2020.
At the same time, rents, vacancy, and cap rates are not transparent in public data and must be sourced from proprietary or local datasets. Climate and natural hazard risks are material and can affect both operating performance and long term asset viability. Taxation and regulatory regimes, particularly around transient accommodations and rental activity, add complexity.
Investors should treat this state level review as a macro and policy frame and ensure that any allocation to Hawaii real estate, whether multifamily, single family rental, hospitality, or commercial, is supported by detailed local market studies, property specific due diligence, and conservative assumptions about income growth, expenses, and exit pricing. Diversification across islands, sectors, and business plans may help manage concentrated risks. Nothing in this section is a recommendation to pursue any specific strategy or investment, and there is no assurance that any objective or outcome described will be achieved.
Section 20Conclusion
Hawaii’s real estate markets sit at the intersection of high incomes, high costs, constrained land, and significant environmental risk. Public data show a state with approximately 1.43 million residents in 2026, high per capita and household incomes, low unemployment, and a housing market where prices have risen sharply over the last six years. They also show a small but active construction pipeline, with a few hundred private housing units authorized per month, and city level listing data that confirm high price points in major markets.
However, important elements of the investment picture remain opaque in public statistics, particularly rents, vacancy, and cap rates. These gaps, combined with structural risks around tourism dependence and climate, mean that Hawaii is not a market for investors who rely solely on broad national datasets or high level indicators. Instead, it rewards those who pair an understanding of the state’s macro fundamentals with rigorous local research and disciplined underwriting.
Sources
- Federal Reserve Bank of St. Louis, Resident Population in Hawaii, series HIPOP, thousands of persons, annual, not seasonally adjusted, reporting 1,451.130 thousand in 2020, 1,446.909 thousand in 2021, 1,437.812 thousand in 2022, 1,434.950 thousand in 2023, 1,434.952 thousand in 2024, and 1,432.820 thousand in 2025, retrieved August 7, 2026,, https://fred.stlouisfed.org/series/HIPOP
- Federal Reserve Bank of St. Louis, Per Capita Personal Income in Hawaii, series HIPCPI, dollars, annual, not seasonally adjusted, reporting 57,030 in 2020, 61,269 in 2021, 63,296 in 2022, 67,571 in 2023, 71,573 in 2024, and 76,592 in 2025, retrieved August 7, 2026,, https://fred.stlouisfed.org/series/HIPCPI
- Federal Reserve Bank of St. Louis, All Transactions House Price Index for Hawaii, series HISTHPI, index where the first quarter of 1980 equals 100, quarterly, not seasonally adjusted, reporting 640.09 in the first quarter of 2020, 662.33 in the first quarter of 2021, 797.02 in the first quarter of 2022, 857.44 in the first quarter of 2023, 908.41 in the first quarter of 2024, and 950.52 in the first quarter of 2026, retrieved August 7, 2026,, https://fred.stlouisfed.org/series/HISTHPI
- Federal Reserve Bank of St. Louis, New Private Housing Units Authorized by Building Permits for Hawaii, series HIBPPRIV, number of units, monthly, not seasonally adjusted, reporting 324 units in June 2024, 263 units in June 2025, and 306 units in June 2026, with monthly values across 2024 and 2025 ranging from about 133 to about 438 units, retrieved August 7, 2026,, https://fred.stlouisfed.org/series/HIBPPRIV
- Bureau of Labor Statistics, Hawaii Economy at a Glance, statewide civilian labor force, employment, unemployment, unemployment rate, and nonfarm wage and salary employment by sector for January through June 2026, including a preliminary June 2026 civilian labor force of 690.4 thousand, employment of 672.5 thousand, unemployment of 17.9 thousand, an unemployment rate of a preliminary 2.6 percent, total nonfarm employment of a preliminary 643.0 thousand with a twelve month change of a preliminary 0.5 percent, and sector detail for mining, logging and construction, manufacturing, trade, transportation and utilities, information, financial activities, professional and business services, education and health services, leisure and hospitality, other services, and government, data extracted August 6, 2026,, https://www.bls.gov/eag/eag.hi.htm
- World Population Review, Hawaii Population 2026, state profile providing a 2026 population of 1,430,688 persons, a population density of 131 persons per square mile, a population rank of 40, historical population values including 1,364,004 in 2010 and 1,451,130 in 2020, racial composition including 37.27 percent Asian, 26.05 percent two or more races, 22.51 percent White, and 10.31 percent Native Hawaiian or Pacific Islander with counts such as 538,807 Asian residents and 325,356 White residents, income statistics including an average per capita income of 52,424 dollars, median household income of 98,317 dollars, and poverty rate of 9.97 percent, and county notes including Honolulu County near 979,000 residents down about 3.3 percent since 2020, Hawaii County up about 4.7 percent to roughly 210,000, and Kalawao County at 81 residents, accessed August 7, 2026,, https://worldpopulationreview.com/states/hawaii
- Redfin, Hawaii Homes for Sale, Hawaii state page reporting 9,239 homes for sale statewide, a median list price of 750,000 dollars, and an average price of 639 dollars per square foot, with a table of popular cities including Honolulu at 585,000 dollars average list price, 668 dollars per square foot, and 94 days on market, Kailua Kona at 662,000 dollars, 606 dollars per square foot, and 73 days, Kailua at 1,625,000 dollars, 862 dollars per square foot, and 65 days, and Hilo at 590,000 dollars, 386 dollars per square foot, and 109 days, retrieved August 7, 2026,, https://www.redfin.com/state/Hawaii
- U.S. Department of Housing and Urban Development, Fair Market Rents by State, County, and Metropolitan Area, portal providing fiscal year 2026 Fair Market Rent documentation and large Excel and comma separated files, including county level data and Small Area Fair Market Rents and a note that files were updated August 29, 2025 to correct values for the Urban Honolulu metropolitan statistical area, consulted qualitatively because the file formats could not be parsed here, accessed August 7, 2026,, https://www.huduser.gov/portal/datasets/fmr.html
- State of Hawaii Department of Business, Economic Development and Tourism, Research and Economic Analysis Division, describing its role in providing data, analyses, and economic forecasts for Hawaii, including tourism, labor, energy, and demographic statistics, used qualitatively to contextualize the state’s reliance on tourism, accessed August 7, 2026,, https://dbedt.hawaii.gov/economic/
- State of Hawaii Department of Business, Economic Development and Tourism, Hawaii Housing Finance and Development Corporation, official site identifying the corporation as a state housing finance and development entity, used qualitatively to note the existence of a statewide housing finance agency, accessed August 7, 2026,, https://dbedt.hawaii.gov/hhfdc/
- State of Hawaii Department of Taxation, official website listing tax announcements and information on topics such as pass through entity taxation and rental collection agreements, used qualitatively to frame the tax administration environment, accessed August 7, 2026,, https://tax.hawaii.gov
- Federal Emergency Management Agency, Flood Maps, overview explaining that any area with a one percent or higher annual chance of flooding is considered high risk with at least a one in four chance of flooding during a thirty year mortgage and that there is no such thing as a no risk zone, used to frame flood and climate risk considerations, accessed August 7, 2026,, https://www.fema.gov/flood-maps
- National Oceanic and Atmospheric Administration, National Centers for Environmental Information, Climate at a Glance Statewide Time Series, interactive interface reviewed without extractable numeric series for Hawaii, consulted qualitatively for climate context, accessed August 7, 2026,, https://www.ncei.noaa.gov/access/monitoring/climate-at-a-glance/statewide/time-series