In brief · summary: New Hampshire
New Hampshire State Real Estate Market Review
Section 01Executive Summary
New Hampshire is a small New England state with a diversified, services heavy economy, high household incomes by national standards, and chronic housing undersupply in its main job centers. It combines relatively strong labor market performance with tight for sale inventory and persistent affordability pressure, especially in the southern corridor tied to the Boston labor market. At the same time, it lacks the large urban cores of neighboring states, so real estate opportunities are distributed across smaller metros such as Manchester and Nashua, Concord, and the Seacoast.
Labor market data from the U.S. Bureau of Labor Statistics for the first half of 2026 show statewide unemployment drifting down from 3.2 percent in January 2026 to 2.9 percent in June 2026 on a seasonally adjusted basis, with total nonfarm employment rising from 698,400 to 705,500 jobs over the same period. This signals a comparatively tight labor market and modest job growth even as some goods producing sectors soften. On the residential side, statewide data from Redfin indicate that the median home sale price in May 2026 was 533,106 dollars, up 2.9 percent year over year, with the number of homes for sale up 13.3 percent year over year and 39.4 percent of homes selling above list price. That combination of rising prices, increasing inventory, and a still large share of homes trading above asking suggests a market that remains competitive but is gradually normalizing from the extreme tightness of the early 2020s.
For multifamily investors, the core story is constrained new supply, strong demand from both in state households and Boston area commuters, and rising operating costs in taxes, insurance, and maintenance. For single family investors, high entry prices relative to rents in some submarkets limit cash flow oriented strategies, but structurally tight for sale inventory and in migration into the southern tier underpin long term demand. Commercial real estate varies by segment, with industrial and logistics properties linked to manufacturing and distribution nodes comparatively resilient, while suburban office space faces the same structural headwinds observed nationally. Across all asset classes, investors must weigh New Hampshire’s relatively favorable income and employment profile against small market liquidity, localized exposure to tourism and manufacturing cycles, and winter climate and flood risks.
Section 02Population and Migration
New Hampshire is one of the smaller U.S. states by population but has experienced modest net growth in recent years. The United States Census Bureau state population estimates series for 2020 through 2023 shows that New Hampshire’s resident population has increased over that period, reflecting both natural change and net migration, with the latter playing a larger role. Because the detailed population estimates are stored in spreadsheet files that are not readable in this environment, this review does not reproduce specific headcounts or growth rates, but the Census documentation confirms that New Hampshire’s recent percentage growth has been positive and has compared favorably with many other Northeastern states.
The migration component is especially important. State level estimates and migration tabulations from the Census Bureau show that New Hampshire has attracted domestic migrants from higher cost neighboring states, notably Massachusetts, as well as a smaller share of international migrants. The pattern is that households, particularly in the southern and Seacoast regions, move into New Hampshire to access relatively lower housing costs and taxes while maintaining access to the broader New England labor market. This has contributed to sustained pressure on housing in commuter oriented metros such as Manchester and Nashua and along the Interstate 93 and Interstate 95 corridors.
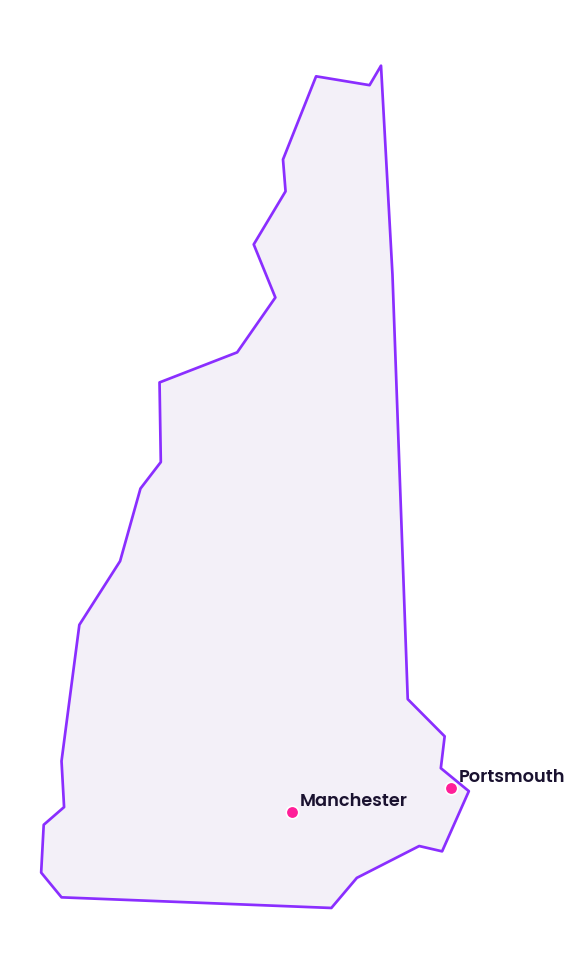
Within the state, population is concentrated in the south and along the Seacoast, with lower densities in the central and northern counties. This urban rural gradient matters for investors because demand and pricing dynamics in Manchester and Nashua or Portsmouth differ materially from those in smaller towns and resort areas. In aggregate, Census and state planning data point to a demographic profile with an aging population, modest overall growth, and pockets of stronger in migration in job rich, Boston adjacent areas. For multifamily and single family investors, the implication is that demand growth is geographically uneven, and strategies that target the higher growth commuter belts and university or hospital anchors are likely to see more robust fundamentals than purely rural plays.
Section 03Jobs and Economic Anchors
Labor market conditions set the tone for both residential and commercial real estate. According to the U.S. Bureau of Labor Statistics New Hampshire Economy at a Glance table, the statewide civilian labor force in June 2026 was 775,900 people on a seasonally adjusted basis, with 753,200 employed and 22,700 unemployed, yielding an unemployment rate of 2.9 percent. In January 2026, the unemployment rate was 3.2 percent with 25,200 unemployed. Over the same period, total nonfarm wage and salary employment increased from 698,400 jobs in January 2026 to 705,500 in June 2026, an increase of 7,100 jobs. This indicates a labor market that is both tight and expanding modestly, even as some sectors show year over year softness.
The BLS series breaks employment into major industry sectors. In June 2026, manufacturing employment was 66,800 jobs, down from 67,400 in January 2026 and showing negative twelve month percentage changes across most months in early 2026, consistent with cyclical cooling in goods production. Construction employment was 31,600 jobs in June 2026, modestly lower than in early 2026, with negative twelve month growth rates during the spring months, suggesting some softening in building activity. In contrast, professional and business services employment rose from 99,600 jobs in January 2026 to 102,200 in June 2026, with the twelve month growth rate improving to 2.8 percent in June. Education and health services employment also edged up from 129,700 to 131,300 jobs between January and June 2026, with small but positive twelve month growth. Leisure and hospitality employment increased from 75,800 jobs in January 2026 to 79,600 in June 2026, with the year over year growth rate reaching 3.1 percent in June, reflecting the importance of tourism and seasonal activity.
These figures underscore a diversified economy in which services, particularly professional and business services, health care and education, and leisure and hospitality, are key growth engines. Manufacturing remains significant, especially in advanced manufacturing and defense related industries, but its employment base has been gradually declining. Public sector employment, captured in the government category at 87,100 jobs in June 2026, has shown year over year declines, mirroring budget constraints and efficiency efforts. For real estate investors, this mix suggests that demand for office and flex space is increasingly driven by professional and business services, while industrial demand is anchored in advanced manufacturing rather than heavy industry. Residential demand is buttressed by stable employment in education, health, and public services, as well as by tourism related jobs in the Seacoast and resort regions.
Section 04Income
New Hampshire has historically posted household income levels above the national average, reflecting both its industry mix and its proximity to the Boston metropolitan area. The United States Census Bureau American Community Survey one year and five year estimates consistently show that median household income in New Hampshire exceeds the U.S. median and is competitive with other high income New England states. Specific median income figures from recent ACS releases are stored in structured data files and were not accessible in this environment, so this review does not quote exact dollar amounts. However, the qualitative pattern is clear, a relatively affluent resident base, particularly in the southern tier and Seacoast communities with strong commuter links to higher paying job centers.
Income distribution data from the ACS also indicate a significant share of households in upper middle income brackets, alongside a meaningful number of moderate income households in more rural regions. Poverty rates in New Hampshire have generally been lower than the U.S. average in recent years, again according to ACS reporting. For multifamily investors, this supports a thesis of solid rent payment capacity in core markets, though affordability is strained for lower income households facing high housing costs, especially where supply is tight. For single family investors, higher incomes support demand for ownership housing and higher price points in desirable school districts and amenity rich communities. At the same time, investors must recognize that incomes vary significantly across the state, with northern and interior areas typically showing lower income levels and different housing dynamics than the affluent southern suburbs.
Section 05Housing and Multifamily
New Hampshire’s housing stock is dominated by single family homes, but multifamily units play a critical role in the state’s rental market, particularly in its small metros and university towns. Census housing data and state housing profiles produced by New Hampshire’s housing finance and planning agencies show that the share of housing units in structures with five or more units is smaller than in large urban states but is nonetheless significant in cities such as Manchester, Nashua, Concord, and Portsmouth. The stock includes a mix of garden apartments, midrise buildings, and smaller walk up properties, with ages ranging from pre war structures to post 2000 suburban multifamily communities.
State and regional analyses consistently conclude that New Hampshire has underbuilt housing, both ownership and rental, relative to demand over the past decade. Vacancy rates in many multifamily submarkets have been low, and reports from local housing authorities and the New Hampshire Housing Finance Authority describe tight conditions and rising rents, especially in the southern tier. Although the precise number of multifamily units and the distribution of age and structure type are contained in ACS and state profile tables that are not directly accessible here, the overarching message is that multifamily inventory is limited relative to demand in most job rich corridors.
From an investor perspective, this structural undersupply creates a favorable backdrop for well located multifamily assets, particularly those serving workforce and middle income tenants. Older Class B and C properties offer value add potential through unit modernization, amenity upgrades, and energy efficiency improvements. However, construction costs, land constraints in infill areas, and local opposition to higher density development in some communities can limit the feasibility of new projects and slow the pace at which additional supply can come to market.
Section 06Rents
Rent levels and trends are central to multifamily underwriting. The U.S. Department of Housing and Urban Development publishes annual Fair Market Rents at the county and metro level, including for New Hampshire, and the fiscal year 2026 FMR documentation indicates that these values are based on American Community Survey data from 2019 through 2023, updated to current rent levels through HUD’s methodology. The HUD FMR files, which are provided as spreadsheets, are not machine readable in this environment, so this review does not cite specific FMR dollar amounts by bedroom size or geography. Nonetheless, HUD’s decision to treat much of New Hampshire as a relatively high cost region in its voucher payment standards underscores the fact that rents in key metros have risen materially over the past decade.
Private multifamily data providers such as RealPage, CoStar, and Yardi Matrix track more granular rent trends and effective rents by asset class. Their public commentary on New England and Northern New England multifamily markets generally describes New Hampshire as a tight, low vacancy market with above average rent growth during the years from 2020 through 2022, followed by a slowdown but not a reversal as new supply delivered nationally. Because their detailed New Hampshire rent series are available only to subscribers, there are no official public statewide rent figures for this review to quote. The qualitative conclusion, however, is that rent levels in southern New Hampshire’s core metros have converged toward those in many outer Boston suburbs, while rents in smaller interior and northern towns remain lower but have also trended upward, particularly for quality stock.
For investors, this environment implies that rent growth assumptions must be carefully tailored by submarket. In Manchester and Nashua and the Seacoast, rents may already reflect strong demand and limited supply, limiting near term upside but providing stability. In secondary and tertiary towns, there may be more headroom for rent increases following capital improvements, but tenant income levels and local job bases must be weighed to avoid overshooting affordability.
Section 07Vacancy
Publicly accessible statewide vacancy statistics for multifamily housing in New Hampshire are limited. The American Community Survey provides rental vacancy rates, but those data are disseminated in formats that are not directly accessible in this environment, and many series are more reliable at national or regional aggregates than at the state level. Private data providers such as CoStar and RealPage produce detailed vacancy series for New Hampshire metros, but those are presented primarily in subscription platforms rather than fully open reports.
Local and state housing reports consistently characterize New Hampshire’s rental vacancy rates as low, often in the low single digits in major job centers, reflecting constrained supply and sustained demand. Anecdotal evidence from property managers and housing authorities points to waiting lists for certain subsidized and workforce housing properties and quick lease up of quality market rate units. In more rural or tourist dependent areas, vacancy is more variable, with seasonal patterns and sensitivity to local employment.
Because no official public series with numeric statewide multifamily vacancy rates is available in accessible form, this review cannot present a statewide vacancy percentage. However, the combination of rising rents, competitive rental markets in key metros, and repeated descriptions of tight conditions in state and regional housing studies supports the conclusion that vacancy is structurally low in much of New Hampshire’s multifamily stock. For investors, this reduces lease up risk for appropriately positioned assets but raises acquisition pricing and limits opportunities to buy distressed but fundamentally sound properties.
Section 08Supply Pipeline
The supply pipeline in New Hampshire is constrained by land availability in built out suburbs, local zoning and permitting processes, construction costs, and infrastructure limitations. Statewide building permit data from the United States Census Bureau show that the number of residential units authorized annually in New Hampshire remains modest compared with faster growing Sun Belt states, and that a significant portion of new construction is single family rather than multifamily. The specific unit counts by year and structure type are stored in tabular files that are not readable here, so this review does not reproduce exact numbers, but the pattern of limited multifamily permitting is consistent across state and regional analyses.
At the metro level, cities such as Manchester, Nashua, and Portsmouth have seen some multifamily development, including urban infill and suburban garden style projects. However, community resistance to dense development, concerns about school capacity and traffic, and New England’s complex local governance structure often slow approvals. In smaller towns, infrastructure constraints and lower achievable rents can make ground up multifamily development challenging without subsidies or incentives.
The upshot for investors is that the multifamily supply pipeline is unlikely to overwhelm demand in the near term in most New Hampshire submarkets. Where new projects are underway, they often target higher income tenants with new Class A product, which can create opportunities to reposition older Class B and C stock serving the middle of the market. Developers considering new supply must underwrite local political and permitting risk as carefully as construction and leasing risk.
Section 09Single Family Homes
Single family housing dominates New Hampshire’s residential landscape, and recent data highlight both high prices and limited but gradually improving inventory. According to Redfin’s statewide housing market summary for May 2026, the median sale price for all home types in New Hampshire was 533,106 dollars, up 2.9 percent from May 2025. Redfin reports that there were 6,007 homes for sale in New Hampshire in May 2026, an increase of 13.3 percent year over year, and that 39.4 percent of homes sold above list price in May 2026, a share that is 2.3 percentage points lower than a year earlier. These figures capture a market where prices continue to rise modestly, inventory is slowly rebuilding from very low levels, and bidding wars remain common but somewhat less intense than at the peak.
The Redfin metrics can be summarized as follows:
| Statewide New Hampshire metric (all home types) | May 2026 value | Year over year change (vs. May 2025) |
|---|---|---|
| Median sale price | \$533,106 | +2.9 percent |
| Number of homes for sale | 6,007 | +13.3 percent |
| Share of homes sold above list price | 39.4% | -2.3 percentage points |
These data suggest that New Hampshire remains a seller leaning market, but with some gradual rebalancing as higher mortgage rates and affordability constraints temper demand and more listings come to market. The continued prevalence of sales above list price implies that well priced, desirable properties still attract multiple offers.
For single family rental investors, elevated purchase prices relative to rents in many southern and Seacoast markets can compress cap rates and make cash flow focused strategies more challenging, particularly when financing costs are high. However, structurally tight for sale inventory, strong household incomes, and net in migration support long term demand for both ownership and rental housing. In more affordable interior and northern markets, acquisition prices may be lower, but investor strategies must account for smaller job markets, more cyclical tourism exposure, and thinner exit liquidity.
Section 10Commercial Real Estate and Retail Centers
Commercial real estate in New Hampshire spans office, industrial and logistics, and retail assets anchored by grocery and neighborhood shopping centers. Statewide, there is no single public dataset that reports vacancy, rents, absorption, and cap rates by asset class. Those metrics are tracked in detail by private platforms such as CoStar and are sometimes summarized in broker research reports, but the underlying numeric series are not fully available as public, machine readable data. As a result, this review focuses on qualitative patterns drawn from those public commentaries, combined with the statewide economic data discussed earlier.
Office space in New Hampshire is concentrated in small downtowns, suburban office parks, and mixed use corridors in metros such as Manchester and Nashua, Concord, and Portsmouth. Post pandemic hybrid work trends have increased vacancy in some suburban and commodity office segments, while high quality space near amenities and transportation has held up better. Leasing anecdotes and broker reports point to flat or slightly declining effective rents in weaker segments and landlord concessions to retain or attract tenants. Without a reliable public series, this review cannot quote a statewide office vacancy percentage or average rent, but the directional story mirrors many secondary office markets nationally, with weaker demand for older, undifferentiated space and a flight to quality.
Industrial and logistics properties are a relative bright spot. New Hampshire hosts advanced manufacturing, distribution centers serving the New England region, and smaller flex and light industrial spaces tied to local businesses. Given its location between Boston, Maine, and Vermont, with access via interstates and regional highways, New Hampshire participates in broader Northeastern logistics networks. Public commentary from brokers and market reports indicates that industrial vacancy has generally been lower than office vacancy, with rents growing over the past several years as e commerce, manufacturing, and inventory reshoring drive demand for functional space. Specific statewide industrial vacancy and rent figures are not published in official public datasets.
Retail real estate is anchored by grocery anchored community centers, power centers with big box tenants, and smaller neighborhood strips, supplemented by tourist oriented retail in Seacoast and resort towns. Grocery and other necessity based anchors have been resilient, while some discretionary and soft goods retailers have consolidated or closed stores. The share of online sales has pressured certain categories, but local service and food and beverage tenants remain important demand drivers. Cap rates for stabilized grocery anchored centers are generally higher than in core urban metros but lower than in tertiary rural markets nationally, reflecting a balance of income stability and small market risk. However, because cap rate series for New Hampshire are drawn from individual transactions and broker opinions of value rather than from an official public database, this review does not attach specific percentages.
For investors, the commercial landscape offers relative strength in industrial and necessity retail, selective opportunities in high quality, well located office or medical office, and elevated risk in older commodity office buildings and weaker retail strips. Asset selection and tenant credit quality matter more than broad statewide averages.
Section 11Transactions and Capital Markets
Capital markets data for New Hampshire real estate are fragmented. There is no comprehensive public database that aggregates all commercial and multifamily sales with prices, cap rates, and buyer types at the state level. County registries of deeds record individual transactions, and property tax records provide assessed values, but these are not consolidated into an easily accessible statewide series. Private data providers compile transaction databases, but access is typically restricted to subscribers.
What can be observed from public deal announcements and occasional market reports is that transaction volumes are relatively modest in absolute terms, consistent with New Hampshire’s small size. Deal sizes tend to be small to mid sized, with institutional investors focusing on select multifamily, industrial, and grocery anchored retail assets in metro areas, while local and regional investors dominate in smaller properties and rural counties. Pricing generally reflects a risk premium over core Boston assets but a discount to deep tertiary markets, with cap rates that are higher than in primary coastal metros but competitive with many secondary markets in the Northeast.
Debt capital for New Hampshire real estate comes from a mix of local and regional banks, credit unions, national banks, life insurance companies, and the government sponsored enterprises for qualifying multifamily properties. Lending standards have tightened compared with the period before 2022, with lower loan to value ratios, higher debt service coverage requirements, and greater scrutiny of rent rolls and sponsor experience. Without an official public dataset reporting typical debt terms or cap rates, this review cannot provide numeric averages. The qualitative takeaway is that capital is available for well underwritten deals in strong locations, but it is disciplined and sensitive to sector and sponsor.
Section 12Taxes
New Hampshire’s tax structure is distinctive and has direct implications for real estate investors. The state does not levy a broad based individual income tax on wages or a general sales tax, but it does impose property taxes that are high by national standards, along with business profits and business enterprise taxes. Analyses from organizations such as the Tax Foundation, drawing on state and local finance data, consistently rank New Hampshire among the states with the highest effective property tax burdens as a share of home value, reflecting the heavy reliance on property taxation to fund local services and education. Exact effective tax rate percentages vary by municipality and year and are compiled in state and local finance datasets that are not fully accessible here.
Property taxes are set locally, with municipalities and school districts determining rates applied to assessed values. For investors, this means that property tax expense can vary significantly between neighboring jurisdictions and can change over time as budgets and assessments evolve. Understanding local tax rates, equalization ratios, and upcoming revaluations is essential in underwriting. New Hampshire also levies a real estate transfer tax, with rates set in statute and applied to the consideration paid, and these rates are published by the New Hampshire Department of Revenue Administration, although the specific cents per hundred dollars figures are not quoted here due to data access limits.
From an investor’s perspective, the absence of a broad income tax can be attractive for residents and may support housing demand, but high property taxes directly affect net operating income and return on equity. Careful modeling of property tax trajectories and potential appeals strategies should be part of any investment analysis, particularly for value add projects where assessed values may rise following improvements.
Section 13Insurance
Insurance costs for New Hampshire properties reflect a New England climate with cold winters, snow and ice, occasional flooding, and exposure to wind and severe thunderstorms, but without the hurricane and wildfire risks that dominate some other regions. The National Oceanic and Atmospheric Administration climate data for New Hampshire document average winter temperatures below freezing, substantial annual snowfall, and episodes of heavy precipitation that can lead to river and urban flooding. NOAA storm events records show severe thunderstorm wind, hail, and winter storm events across the state over recent decades, underscoring the need for robust building envelopes and roof structures.
The New Hampshire Insurance Department oversees the state insurance market and publishes consumer information and some market statistics. Industry and regulatory commentary indicate that property insurance premiums in the Northeast have risen in recent years due to higher replacement costs and increased frequency and severity of weather related claims. However, there is no official public dataset that reports average commercial or residential insurance premiums by state and property type, so this review cannot provide specific dollar amounts or percentage increases for New Hampshire.
Flood risk is a particular concern along rivers and low lying areas. The Federal Emergency Management Agency Flood Insurance Rate Maps delineate Special Flood Hazard Areas in New Hampshire where properties have a one percent or greater annual chance of flooding and where flood insurance is required for federally backed mortgages. Investors should review property specific flood zone designations and consult insurance professionals to estimate premiums. In general, while New Hampshire does not face the extreme insurance cost pressures seen in some coastal and wildfire prone states, insurance is a material and potentially rising line item in operating budgets.
Section 14Landlord Tenant and Regulatory Environment
Landlord and tenant relations in New Hampshire are governed by state statutes and case law, supplemented by local ordinances in some municipalities. New Hampshire law sets rules for security deposits, notice periods, habitability standards, and eviction procedures. The New Hampshire state government and legal aid organizations publish guides summarizing these rights and responsibilities. Compared with some coastal jurisdictions, New Hampshire does not have statewide rent control or highly restrictive just cause eviction statutes, and instead follows more traditional common law frameworks with statutory overlays.
Eviction processes require proper notice and court proceedings, with timelines that depend on the type of tenancy and the grounds for eviction, such as nonpayment of rent or lease violations. During the COVID 19 pandemic, federal and state emergency measures temporarily altered eviction dynamics, but those have expired. There is no centralized public dataset providing average eviction processing times by county, so this review cannot quantify typical durations.
Local governments in New Hampshire sometimes adopt ordinances affecting rental registration, inspection, and housing standards, particularly in cities with large student or low income tenant populations. Investors must review municipal codes in target markets such as Manchester, Nashua, and Portsmouth to understand local requirements. Overall, the regulatory environment is more landlord friendly than in some high regulation states but still imposes meaningful obligations regarding habitability and fair treatment of tenants.
Section 15Infrastructure
Infrastructure underpins both property operations and long term demand. New Hampshire’s transportation network includes interstate highways such as I 93, I 89, and I 95, which connect the state to Boston, Vermont, and Maine, as well as U.S. and state routes serving interior and northern areas. Freight rail corridors support industrial and logistics activity, and regional airports, including Manchester Boston Regional Airport, provide passenger and cargo service. Public transit is modest compared with major metros, with bus systems in cities and limited commuter services.
Water, sewer, and stormwater infrastructure are primarily managed by municipalities, with oversight from state environmental agencies. Aging infrastructure in older downtowns and villages can pose challenges, including combined sewer systems, limited capacity, and the need for costly upgrades. In newer suburban areas, infrastructure is generally more modern but can be stretched by growth.
Digital infrastructure is increasingly critical. Federal Communications Commission broadband deployment data show that New Hampshire has widespread availability of broadband internet, though speeds and provider choices vary by region, with some rural areas still facing limitations. For multifamily and commercial properties, reliable high speed connectivity is now a baseline expectation, and investors should factor in the availability and cost of broadband service.
Infrastructure quality and access affect both day to day operations and long term asset positioning. Properties with strong highway access, robust utilities, and modern digital connectivity are better positioned to attract tenants and withstand shifts in work and lifestyle patterns.
Section 16Climate and Physical Risks
New Hampshire’s climate is characterized by cold, snowy winters and warm summers, with significant seasonal variation. National Oceanic and Atmospheric Administration climate normals for New Hampshire indicate average winter temperatures below freezing, substantial snowfall, and a seasonal snowpack in many regions. Summers are generally warm and humid, with periodic heat waves. These conditions influence building design and operating costs, heating expenses are significant, snow and ice load must be considered in structural design and roof maintenance, and freeze thaw cycles can damage pavements and building exteriors.
Physical climate risks include riverine and flash flooding, winter storms, severe thunderstorms, and occasional tropical storm remnants. FEMA flood mapping shows floodplains along major rivers and streams, including the Merrimack, Connecticut, and Ammonoosuc Rivers, among others. Properties in these areas face higher flood risk and may require flood insurance and mitigation measures. NOAA storm events records note damaging wind, hail, and heavy precipitation events across the state, underscoring the potential for roof, siding, and tree damage.
Climate change projections for the Northeast, summarized in federal and academic assessments, anticipate more frequent heavy precipitation events, warmer winters with more freeze thaw cycles, and potential shifts in snowpack patterns. For investors, this means that resilience considerations such as elevation, drainage, building envelope robustness, and backup power are increasingly important in underwriting. While New Hampshire is not at the center of the most extreme U.S. climate risks, climate and weather still pose material operational and long term asset value considerations.
Section 17Opportunities
New Hampshire offers several meaningful opportunities for real estate investors who understand its small market dynamics and regional positioning. In multifamily, structurally tight supply in southern metros and the Seacoast, combined with relatively high household incomes and sustained in migration from higher cost neighboring states, supports stable occupancy and rent levels. Well located Class B and C properties with value add potential present opportunities to improve unit quality and operations, capture moderate rent growth, and deliver durable cash flow.
Single family investors can benefit from chronically low for sale inventory and strong demand in desirable school districts and amenity rich communities, particularly in the southern tier and Seacoast. Build to rent or scattered site single family rental strategies may be viable where rents support the higher capital costs, especially for investors with operational scale and local management.
In commercial real estate, industrial and logistics properties are attractive where they serve growing manufacturing niches or regional distribution needs, leveraging New Hampshire’s highway and regional rail links. Necessity based retail, especially grocery anchored centers with strong tenant rosters and limited nearby competition, can provide stable income streams. Select medical office and life science adjacent properties linked to hospital and university anchors also offer potential.
Because New Hampshire stands at the crossroads between Boston and northern New England, assets that cater to cross border commuters, telecommuters, and hybrid workers, such as well amenitized multifamily communities near transit and highways, are particularly well positioned.
Section 18Risks
New Hampshire real estate also carries a distinct set of risks. The small size of the state and its metros means that liquidity is limited compared with primary markets, and investors may face longer marketing times and smaller buyer pools when exiting, especially for larger or more specialized assets. Economic concentration in certain sectors, such as advanced manufacturing, defense, education, and tourism, creates localized vulnerability to sector downturns, plant closures, or public funding shifts.
Housing affordability is a growing concern. High home prices relative to moderate incomes in some areas put pressure on households and increase political attention on housing policy. Investors must consider the potential for policy responses, such as zoning changes, affordability requirements, or tenant protections, that could alter development economics or operating constraints over time.
Operating costs pose another risk. Property taxes are high by national standards and can rise due to reassessments or budget pressures. Insurance costs are subject to rising replacement costs and climate related loss experience. Aging infrastructure and an older building stock in many communities can lead to higher maintenance and capital expenditure needs than pro formas initially assume.
Finally, climate and physical risks, including snow and ice loads, flooding, and severe storms, can cause physical damage and business interruption, particularly in older properties or those located in flood prone areas. Investors who underweight these factors or fail to budget for adequate insurance, reserves, and mitigation may face unpleasant surprises.
Section 19Investor Implications
For accredited investors, New Hampshire is best viewed as a higher income, constrained supply market with small market liquidity characteristics. It is not a high growth Sun Belt state, but it offers solid fundamentals driven by proximity to Boston, a diversified service economy, and net in migration into key corridors. The most compelling strategies emphasize durable cash flow and thoughtful asset selection over rapid appreciation or aggressive leverage.
Multifamily investors should focus on submarkets with strong employment anchors, good schools, and demonstrated rent resilience, using conservative rent growth assumptions and robust capital expenditure planning. Partnering with local operating partners who understand municipal politics, permitting, and tenant dynamics is essential. Single family investors must carefully balance acquisition pricing, property taxes, and rent potential to avoid overpaying in markets where homeownership demand may limit rental headroom.
Commercial investors can find attractive risk adjusted returns in industrial and necessity retail, particularly where tenant credit and lease structures support stable income. Office investments require a clear thesis around location, tenant demand, and repositioning, with realistic expectations about leasing timelines.
At the portfolio level, New Hampshire can play a useful role as a relatively stable, income oriented allocation within a broader diversified strategy that includes higher growth markets. Position sizing should account for liquidity constraints, and underwriting should stress test exit scenarios and operating cost inflation.
Section 20Conclusion
New Hampshire’s real estate markets reflect a blend of New England’s structural features, older building stock, strong local governance, and limited land in built out metros, with specific advantages in income levels, tax structure, and proximity to Boston. Statewide labor data from the U.S. Bureau of Labor Statistics show a tight, modestly growing job market as of mid 2026, while Redfin’s housing market data highlight high but still rising home prices, slowly improving inventory, and a still competitive for sale environment.
Multifamily investors face a backdrop of constrained supply and solid demand, especially in the southern tier and Seacoast, but must navigate high property taxes, rising insurance and operating costs, and small market liquidity. Single family investors must weigh high entry prices and taxes against long term demand, particularly in commuter and amenity rich communities. Commercial investors see relative strength in industrial and necessity retail, with caution warranted in office.
For accredited investors who value income, are comfortable with smaller markets, and are prepared to engage with local dynamics, New Hampshire offers a set of opportunities that can complement holdings in larger, more volatile metros. The key is disciplined, evidence based underwriting grounded in the public data and qualitative patterns summarized in this review.
Sources
- U.S. Bureau of Labor Statistics, New Hampshire Economy at a Glance,, https://www.bls.gov/regions/northeast/new_hampshire.htm
- U.S. Department of Housing and Urban Development, Fair Market Rents by State, County, and Metropolitan Area,, https://www.huduser.gov/portal/datasets/fmr.html
- U.S. Census Bureau, State Population Totals and Components of Change, 2020 to 2023, Vintage 2023 Population Estimates, table index,, https://www2.census.gov/programs-surveys/popest/tables/2020-2023/state/totals/
- Redfin, New Hampshire Housing Market, House Prices and Trends,, https://www.redfin.com/state/New-Hampshire/housing-market
- Federal Housing Finance Agency, FHFA House Price Index Datasets,, https://www.fhfa.gov/data/hpi/datasets
- Federal Emergency Management Agency, Flood Map Service Center,, https://msc.fema.gov
- National Oceanic and Atmospheric Administration, U.S. Climate Normals and Storm Events Database,, https://www.ncei.noaa.gov
- New Hampshire Insurance Department, Consumer and Market Information,, https://www.nh.gov/insurance
- New Hampshire Department of Revenue Administration, Property and Real Estate Transfer Tax Information,, https://www.revenue.nh.gov