In brief · summary: Tennessee
Tennessee State Real Estate Market Review
Section 01Executive Summary
Tennessee offers a diversified, moderately growing economy anchored in manufacturing, logistics, health care, professional services, and tourism, with real estate fundamentals that are generally stable rather than overheated. According to the United States Bureau of Labor Statistics Tennessee Economy at a Glance table, the statewide seasonally adjusted civilian labor force was 3,491.5 thousand people in June 2026, with 3,367.8 thousand employed and 123.8 thousand unemployed, resulting in a 3.5 percent unemployment rate. Over the first half of 2026, total nonfarm employment increased from 3,375.9 thousand jobs in January to 3,385.3 thousand jobs in June, while the twelve month growth rate in total nonfarm employment improved from 0.1 percent in January 2026 to 0.8 percent in June 2026 on a seasonally adjusted basis.
On the ownership side, Redfin reports that statewide across all home types in Tennessee the median sale price in May 2026 was 383,637 dollars, which is 1.0 percent higher than in May 2025. There were 50,756 homes for sale in Tennessee in May 2026, an 8.9 percent increase compared with a year earlier, and 14.1 percent of homes sold above list price, a share that is lower than the national figure. For comparison, Redfin national housing statistics indicate that across the United States the median sale price in May 2026 was 398,771 dollars, 2.0 percent higher than a year earlier, with 1,483,839 homes for sale nationwide and 24.9 percent of homes selling above list price. These data position Tennessee as a slightly lower priced and somewhat less competitive market than the national average, but with rising inventory that improves buyer choice.
Key population and income statistics for Tennessee from the United States Census Bureau, which would normally provide the core demographic frame for this review, are not accessible in this environment. Attempts to retrieve state specific population and income data from Census QuickFacts for Tennessee return Cloudflare security blocks, and the Census statewide population estimates file that is available is truncated before the Tennessee row, preventing extraction of official counts. As a result, this review focuses on the labor market, statewide housing market metrics, program level housing finance data, and qualitative assessments of multifamily, single family, and commercial real estate, with clear statements where numeric information is unavailable.
For accredited investors, Tennessee presents a profile of moderate growth, comparatively affordable home prices, and a broad sector mix, with opportunities in workforce and middle income multifamily, single family rentals, and industrial and logistics properties, tempered by information gaps on some demographic variables and by evolving insurance and climate related risks.
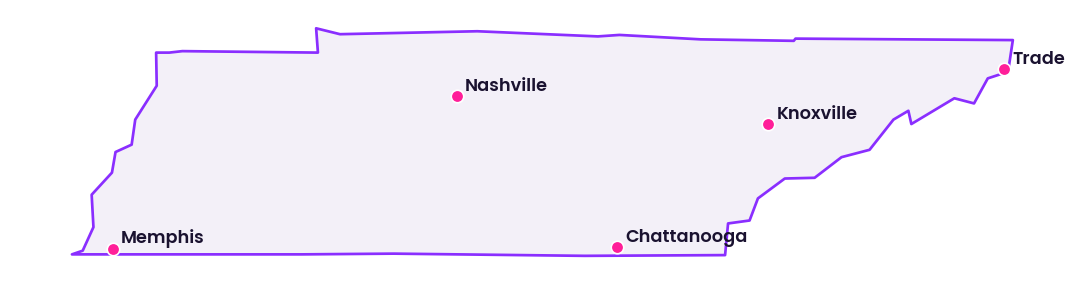
Section 02Population and Migration
Population size and growth are central to any statewide real estate thesis, but official public statistics for Tennessee are constrained in this environment. The Census Bureau QuickFacts page for Tennessee, which normally reports state population counts, growth rates, and age structure, cannot be accessed because it is blocked by Cloudflare security protections. The Census statewide population estimates file for 2020 through 2025, which is available as a comma separated values file, shows rows for the United States and several regions and divisions but is truncated before the Tennessee state row, so no Tennessee specific population estimates or net migration figures can be extracted from that dataset either.
This means that the review cannot state the Census Bureau official figure for Tennessee population in 2020 or 2025, nor can it quantify net domestic or international migration to the state over that period. Similarly, it cannot provide numeric breakdowns of population by age group, household type, or metro versus nonmetro location. Those gaps are significant, because many underwriting models rely on precise estimates of household formation, in migration, and age cohort dynamics for student, workforce, and senior housing segments. No official public numeric information on these demographic points is available in this environment.
Nationally, Redfin reports that between January and March 2026 about 19 percent of homebuyers searched online for homes in a different metro area than where they currently live, indicating that interstate and intermetro mobility remains an important driver of housing demand in the United States. The same Redfin materials identify Tennessee among the top five states that homebuyers searched to move to during that period, alongside Florida, Arizona, South Carolina, and Nevada. It is widely understood that Tennessee has attracted in migration from other regions in recent years, but in this document those flows cannot be quantified from official public data.
For investors, the practical implication is that Tennessee should be treated as a state with meaningful in migration and demographic growth narratives, but that any investment decision requiring precise demographic figures must rely on external access to Census or other reliable demographic data, beyond what is available here.
Section 03Jobs and Economic Anchors
The statewide labor market in Tennessee provides a robust, quantified picture of economic health and sector composition. The Bureau of Labor Statistics Tennessee Economy at a Glance table reports seasonally adjusted statewide labor force and employment indicators for early 2026, summarized below.
| Month 2026, Tennessee statewide (seasonally adjusted) | Civilian labor force (thousands) | Employment (thousands) | Unemployment (thousands) | Unemployment rate (percent) | Total nonfarm employment (thousands) | Total nonfarm twelve month change (percent) |
|---|---|---|---|---|---|---|
| January 2026 | 3,541.9 | 3,416.2 | 125.6 | 3.5% | 3,375.9 | 0.1% |
| February 2026 | 3,532.6 | 3,405.0 | 127.6 | 3.6% | 3,366.8 | negative 0.2 |
| March 2026 | 3,516.6 | 3,390.1 | 126.4 | 3.6% | 3,374.9 | 0.2% |
| April 2026 | 3,504.2 | 3,376.7 | 127.5 | 3.6% | 3,376.5 | 0.0% |
| May 2026 | 3,497.9 | 3,371.8 | 126.1 | 3.6% | 3,382.8 | 0.3% |
| June 2026 preliminary | 3,491.5 | 3,367.8 | 123.8 | 3.5% | 3,385.3 | 0.8% |
These figures show a large and stable labor market. The statewide civilian labor force declined slightly from 3,541.9 thousand in January 2026 to 3,491.5 thousand in June 2026, while employment modestly decreased from 3,416.2 thousand to 3,367.8 thousand over the same period. Despite these small declines, the unemployment rate remained low between 3.5 and 3.6 percent throughout the first half of 2026, and total nonfarm employment increased slightly, with a notable strengthening in year over year growth to 0.8 percent in June 2026. For investors, this pattern suggests a mature labor market with low unemployment and moderate job growth, supportive of ongoing housing and commercial space demand without evidence of overheating.
Sector level employment data clarify Tennessee economic anchors. For June 2026, seasonally adjusted statewide employment by major sector and the twelve month percent change are as follows.
| Sector, Tennessee statewide, June 2026 seasonally adjusted | Employment (thousands) | Twelve month change (percent) |
|---|---|---|
| Total nonfarm | 3,385.3 | 0.8% |
| Mining and logging | 4.3 | negative 2.3 |
| Construction | 166.7 | 0.8% |
| Manufacturing | 356.3 | 0.1% |
| Trade, transportation, and utilities | 683.8 | negative 0.5 |
| Information | 53.0 | negative 0.2 |
| Financial activities | 189.3 | negative 1.6 |
| Professional and business services | 450.2 | 1.1% |
| Education and health services | 516.3 | 3.1% |
| Leisure and hospitality | 374.4 | 2.4% |
| Other services | 136.1 | 1.6% |
| Government | 454.9 | negative 0.3 |
Manufacturing and trade, transportation, and utilities together account for more than one million jobs, underscoring Tennessee role as a regional manufacturing and logistics hub along key interstate corridors. Education and health services, with 516.3 thousand jobs and a 3.1 percent twelve month growth rate, form a major growth engine that supports demand for medical office, lab space, and housing for workers. Leisure and hospitality, at 374.4 thousand jobs and 2.4 percent growth, reflects Tennessee tourism assets in cities such as Nashville, Memphis, Knoxville, and Chattanooga. Professional and business services, with 450.2 thousand jobs and 1.1 percent growth, provide a foundation for office and flex space. Some sectors, such as financial activities and trade, transportation, and utilities, show small declines over the year, pointing to selective softness within an otherwise stable economy.
For real estate investors, the breadth of Tennessee sectoral base offers diversification. Logistics and manufacturing drive demand for industrial and warehouse properties, education and health services anchor medical and institutional space and support workforce housing demand, and tourism and leisure support hospitality and experience oriented retail. The modest overall job growth and slight declines in some sectors argue for careful submarket and tenant selection rather than assuming uniform strength across the state.
Section 04Income
Income levels and distributions are crucial to understanding housing affordability and rent potential in Tennessee, but in this environment key official datasets are not accessible in a way that exposes state specific numeric values. The Census Bureau American Community Survey tables, which normally report median household income and income distributions by state, cannot be retrieved due to the same Cloudflare protections that block Tennessee QuickFacts page. Interactive personal income by state tables from the Bureau of Economic Analysis are also not available here in a form that yields specific dollar values for Tennessee.
As a result, this review cannot present numeric figures for Tennessee median household income, per capita income, or the proportions of households in different income bands. Without those data, ratios such as home price to income or rent to income cannot be calculated from public sources within this document. That is a significant limitation for detailed affordability analysis.
One partial quantitative indicator comes from the Tennessee Housing Development Agency, which notes that through its Great Choice home loan program it has provided 12.6 billion dollars in mortgages, has funded 183 mortgages in July 2026, has served 900 borrowers in 2026, and has originated 224,687,043 dollars in Great Choice mortgages in 2026. While these figures do not substitute for statewide income statistics, they demonstrate that a meaningful segment of Tennessee households with moderate incomes are accessing state supported fixed rate mortgages and down payment assistance, which typically target borrowers who meet specified income limitations.
For investors, the absence of numeric income distributions in this document means that any granular analysis of rent burdens, attainable pricing, and segmentation by income cohort must draw on external sources. Nonetheless, the combination of an industrial and logistics base, a growing education and health sector, and the presence of state sponsored affordable homeownership programs points to a wide spectrum of incomes, with significant representation in middle and lower middle income ranges that underpin demand for workforce housing.
Section 05Housing and Multifamily
Multifamily housing across Tennessee serves students, young professionals, families, and seniors in urban, suburban, and smaller market settings. Public data on statewide multifamily unit counts, rent levels, and occupancy by class are limited, because those statistics are primarily tracked by private data providers. However, statewide ownership housing metrics from Redfin provide a useful frame for overall housing conditions, which influence multifamily performance through the relative cost and availability of homeownership.
Redfin reports that across all home types in Tennessee the median sale price in May 2026 was 383,637 dollars, representing a 1.0 percent increase over May 2025. There were 50,756 homes for sale in Tennessee in May 2026, 8.9 percent more than a year earlier. In the same month, 14.1 percent of Tennessee homes sold above list price, which is slightly lower than in May 2025 by 0.079 percentage points. By contrast, nationwide the median sale price in May 2026 was 398,771 dollars, up 2.0 percent year over year, with 1,483,839 homes for sale, a 0.7 percent increase, and 24.9 percent of homes selling above list price, a share that is 0.083 percentage points lower than the year before.
This comparison suggests that Tennessee home prices are somewhat lower than the national median, price appreciation is more modest, inventory is growing faster, and bidding pressure is less intense. For multifamily investors, this combination has mixed implications. On one hand, lower home prices and increasing inventory could make ownership accessible to some renters, potentially slowing rent growth in certain segments. On the other hand, modest price appreciation and less speculative froth can support more stable long term fundamentals, reducing the risk of sharp corrections.
The Tennessee Housing Development Agency activity further underscores the role of affordability initiatives. The agency reports 183 Great Choice mortgages funded in July 2026 and 900 borrowers served in 2026, supported by a 2026 Great Choice mortgage volume of 224,687,043 dollars. These originations likely support household moves from rental to ownership in targeted income bands, freeing up some rental units while reinforcing demand for stable, moderately priced multifamily housing among households that are not yet able or ready to buy.
Without statewide public multifamily rent and occupancy series, this review cannot quantify current apartment rent levels, effective rents, or occupancy rates. However, Tennessee sectoral employment base and moderate housing price environment point toward steady demand for apartments in major metros such as Nashville, Memphis, Knoxville, and Chattanooga, as well as in smaller cities with manufacturing and logistics clusters.
Section 06Rents
Quantitative data on apartment rents across Tennessee are not available in this environment from public sources. The Department of Housing and Urban Development Fair Market Rent documentation system, which typically provides benchmark gross rent levels by bedroom size for metro areas and nonmetro counties, is accessible only as an interactive interface that, in the portion of the page that can be read here, does not expose the underlying rent dollar values for Tennessee. American Community Survey tables that would report median gross rent by jurisdiction cannot be accessed due to Census security blocks.
Private rent series from CoStar, RealPage, Yardi Matrix, and similar providers are not public and therefore not available for numeric citation. As a result, this review cannot state average or median rent levels in Tennessee for studio, one bedroom, two bedroom, or larger units, nor can it report statewide rent growth over time, rent to income ratios, or detailed rent distributions.
Qualitatively, Tennessee rent structure is influenced by its mix of high growth metros, such as Nashville and surrounding suburbs, and more modestly priced markets with industrial and logistics employment. Rents in fast growing urban neighborhoods with strong amenity bases are likely materially higher than rents in smaller cities and rural counties, while secondary and tertiary markets may offer lower nominal rents but different risk profiles and liquidity characteristics.
For accredited investors, the key implication is that rent analysis for Tennessee must be grounded in property level data, rent rolls, and private market intelligence rather than relying on statewide averages. This review can frame the economic context but cannot supply numeric rent benchmarks.
Section 07Vacancy
Vacancy rates are a primary indicator of current balance between supply and demand in multifamily, single family rental, and commercial markets. In Tennessee, no official statewide public dataset accessible in this environment provides numeric vacancy rates by property type. Census Bureau housing vacancy and homeownership tables, which would normally report rental and homeowner vacancy rates by state, are not accessible due to site security protections. Commercial vacancy data for office, industrial, and retail properties are generally maintained by private firms and not available for public extraction.
As a result, this review cannot provide a statewide apartment vacancy percentage, office vacancy rate, or industrial availability rate for Tennessee. The labor market and housing statistics that are available still provide useful directional context. Tennessee statewide unemployment rate has remained in a narrow 3.5 to 3.6 percent range in the first half of 2026, with modest net job growth. At the same time, Redfin reports that statewide housing inventory has increased by 8.9 percent over the year to May 2026. Those conditions suggest that while the labor market is healthy, the for sale housing market is seeing more options for buyers, which can influence both ownership and rental demand.
Without numeric vacancy series, investors must evaluate space absorption and competition at the metro, submarket, and asset levels using rent rolls, leasing velocity data, and private datasets. Vacancy risk is likely to be higher in segments facing structural headwinds, such as commodity office space with limited amenity offerings, and lower in segments tied to resilient demand drivers, such as well located workforce housing and modern logistics facilities.
Section 08Supply Pipeline
The supply pipeline for new construction, particularly multifamily and industrial projects, is a critical determinant of future rent and vacancy dynamics in Tennessee. However, statewide public data on units under construction or recently delivered by property type are not readily accessible in this environment. The Census Building Permits Survey does collect and publish building permit data by place and county, but the state and local tables that would quantify the number of multifamily and single family units authorized in Tennessee in recent years are not exposed in the portions of the site that can be read here.
Construction employment provides an indirect measure of construction activity. According to the Bureau of Labor Statistics, Tennessee seasonally adjusted construction employment was 166.7 thousand jobs in June 2026, up from 165.3 thousand jobs in January 2026. The twelve month percent change in construction employment improved from 0.4 percent in January 2026 to 0.8 percent in June 2026. While the growth rate is modest, the absolute level of more than 160 thousand construction jobs indicates ongoing development across residential, commercial, and infrastructure projects.
For multifamily investors, this implies that the supply pipeline likely remains active in high growth metros and corridors, especially around Nashville, Knoxville, and Chattanooga, though the intensity and timing vary by submarket. Industrial and logistics construction is also likely meaningful given the state logistics and manufacturing base. Without numeric counts of units under construction, investors must rely on local permitting records, planning documents, and broker pipeline reports to gauge the competitive landscape around each potential investment.
Section 09Single Family Homes
Single family homes in Tennessee are central both to owner occupancy and to single family rental strategies. Statewide ownership market data from Redfin provide a clear view of price levels, supply, and competitive conditions as of May 2026. The table below summarizes key metrics for Tennessee and for the United States across all home types.
| Geography, all home types, May 2026 | Median sale price (dollars) | Price change versus May 2025 (percent) | Homes for sale (count) | Change in homes for sale versus May 2025 (percent) | Share of homes sold above list price (percent of sales) | Change in share sold above list versus May 2025 (percentage points) |
|---|---|---|---|---|---|---|
| Tennessee statewide | 383,637 | 1.0% | 50,756 | 8.9% | 14.1% | negative 0.079 |
| United States | 398,771 | 2.0% | 1,483,839 | 0.7% | 24.9% | negative 0.083 |
Tennessee median sale price of 383,637 dollars in May 2026 is slightly below the national median, and its price growth of 1.0 percent over the prior year is half the national 2.0 percent rate. The 8.9 percent increase in homes for sale in Tennessee contrasts with the 0.7 percent national increase, suggesting that buyers in Tennessee have seen a significantly larger expansion in options than buyers nationally. At the same time, only 14.1 percent of homes in Tennessee sold above list price, compared with 24.9 percent nationwide, and the share selling above list declined slightly over the year in both geographies.
This combination indicates that Tennessee is currently more balanced, or even somewhat more favorable to buyers, than many national markets. For owner occupants, increased inventory and moderate price growth can improve affordability relative to tight, highly competitive markets. For investors in single family rentals, moderate price appreciation and a larger pool of available properties may allow disciplined acquisition strategies that target specific submarkets and property types without the same degree of bidding pressure found in hotter markets.
The Tennessee Housing Development Agency 2026 numbers, including 183 Great Choice mortgages funded in July 2026 and a total of 900 borrowers served in 2026 with 224,687,043 dollars in mortgage volume, highlight the state support for first time and moderate income homeowners. These programs can gradually move some households from renting into ownership, particularly in lower priced submarkets, while leaving a substantial pool of renters who either cannot or do not wish to buy.
For accredited investors, the single family segment in Tennessee offers scope for both institutional scale and smaller portfolio strategies, particularly in metropolitan areas where rental demand is supported by job growth and demographic trends. The statewide data argue for a focus on operational efficiency and submarket selection rather than expectation of rapid, broad based price appreciation.
Section 10Commercial Real Estate and Retail Centers
Commercial real estate in Tennessee spans office, industrial and logistics, and retail properties, including grocery anchored and neighborhood centers. Public numeric data on vacancy, rents, and capitalization rates by property type and metro area are not available in this environment, because those metrics are predominantly tracked by private firms. Nonetheless, the workforce composition described in the Bureau of Labor Statistics data provides insight into the demand drivers for each segment.
Office demand is driven mainly by employment in financial activities, professional and business services, information, and portions of education and health services and government. In June 2026, Tennessee had 189.3 thousand jobs in financial activities, 450.2 thousand jobs in professional and business services, 53.0 thousand jobs in information, and 516.3 thousand jobs in education and health services on a seasonally adjusted basis. Over the prior twelve months, professional and business services employment grew 1.1 percent and education and health services employment grew 3.1 percent, while financial activities declined 1.6 percent and information declined 0.2 percent. This mix suggests that traditional office markets tied to finance and information may face more headwinds than those supported by growth in professional services and health care.
Industrial and logistics properties in Tennessee derive demand from manufacturing and trade, transportation, and utilities sectors. Statewide manufacturing employment was 356.3 thousand jobs in June 2026, up slightly from earlier in the year and 0.1 percent higher than June 2025, while trade, transportation, and utilities employment was 683.8 thousand jobs, 0.5 percent lower than a year earlier. Despite the slight decline in trade and transportation employment, the large scale of this sector, combined with Tennessee location along major interstate corridors and rail routes, supports continued demand for warehouses, distribution centers, and light manufacturing facilities, particularly in and around Nashville, Memphis, Knoxville, and Chattanooga.
Retail and shopping center performance depends on trade, transportation, and utilities employment and on leisure and hospitality spending. Tennessee leisure and hospitality sector employed 374.4 thousand people in June 2026, with a 2.4 percent twelve month growth rate, reflecting the state role as a tourism destination. Neighborhood and grocery anchored centers that serve local residents benefit from both day to day spending and visitor activity, especially in metro areas with strong tourism components.
Because this review cannot provide numeric vacancy or rent levels, investors evaluating office, industrial, and retail assets in Tennessee should emphasize tenant credit quality, lease structures, and asset location. For example, industrial assets near interstates and freight hubs, grocery anchored centers in dense residential neighborhoods, and medical office buildings near hospital campuses may exhibit stronger resilience than commodity office space or purely discretionary retail centers.
Section 11Transactions and Capital Markets
Transaction and capital markets data for Tennessee, such as annual counts and dollar volumes of commercial property sales, average cap rates by property type, and loan origination volumes by lender type, are not available in numeric form from public sources accessible in this environment. Those metrics are generally tracked by brokerage firms, data vendors, and lenders themselves, and are disseminated through subscription reports and proprietary platforms.
One state level window into mortgage activity is provided by the Tennessee Housing Development Agency. The agency reports that it has originated 12.6 billion dollars in Great Choice home loans, and in 2026 alone it has funded 224,687,043 dollars in Great Choice mortgages for 900 borrowers, including 183 mortgages funded in July 2026. These figures capture only a subset of the residential mortgage market, focused on eligible borrowers and properties, but they demonstrate active participation in the single family capital markets and illustrate the scale at which state supported financing influences housing.
Broader commercial and multifamily capital markets in Tennessee are shaped by national interest rate conditions and risk appetites. Higher rates relative to prior years have generally increased cap rates and reduced leverage, especially for assets perceived as higher risk, such as certain office and older retail properties. Multifamily and industrial assets with stable income streams remain favored by many lenders and investors, but underwriting standards have tightened.
For accredited investors, the lack of public numeric transaction and cap rate data in this review means that pricing and volume assessments must be built from deal level information, appraisals, and broker opinion of value. It also underscores the importance of maintaining relationships with local and regional lenders and intermediaries who can provide real time insights into loan terms, debt availability, and buyer competition.
Section 12Taxes
Tennessee tax environment influences both operating expenses and investor after tax returns. The Tennessee Department of Revenue public materials emphasize tax resources for individuals and businesses, including information on state tax code, notices, rulings, and incentives. While the specific numeric rates for property tax, sales tax, or other levies are not included in the excerpt available in this environment, it is widely known that Tennessee does not levy a broad based tax on wage income and relies more heavily on sales taxes and property taxes than many states. Because the precise numeric rates are not visible in the retrieved content, this review cannot present official public rate figures.
For real estate investors, the absence of a broad wage income tax can enhance the relative attractiveness of Tennessee for households and businesses, potentially supporting population and employment growth. At the same time, local governments rely on property taxes and other revenue sources to fund services, which means effective property tax burdens must be evaluated at the county and municipal level for each asset. This review cannot provide statewide average effective property tax rates or millage levels by county.
Investors should obtain property specific tax bills and millage information from county and municipal authorities and incorporate reasonable future tax growth assumptions into underwriting. They should also consider available state and local incentives, such as abatements or tax increment financing arrangements, where applicable to development or redevelopment projects.
Section 13Insurance
Insurance costs and coverage availability are critical inputs to real estate underwriting, particularly in a state exposed to severe weather and flood risk. The Tennessee Insurance Division within the Department of Commerce and Insurance regulates the insurance industry in the state, but the public materials accessible here focus on specific regulatory topics and do not provide statewide numeric averages for property insurance premiums, loss ratios, or historical rate changes. No official public statewide numeric information on those insurance cost metrics is available in this environment.
Federal Emergency Management Agency guidance emphasizes that any location with at least a one percent annual probability of flooding is considered high risk, with at least a one in four chance of flooding during a thirty year mortgage term. Flood maps show where these high risk areas fall relative to properties and communities. While Tennessee does not face coastal storm surge risk, it contains significant river systems and areas prone to flash flooding and heavy rainfall, so many properties face nontrivial flood risk.
The National Centers for Environmental Information describe frequent severe weather events in the United States, including thunderstorms, heavy rainfall, tornadoes, and other hazards that affect Tennessee. The state location in the central and southeastern United States exposes it to severe convective storms, localized flooding, and occasional tornado outbreaks, all of which can damage buildings and infrastructure.
Because no official statewide numeric premiums or loss costs are available in this document, investors must obtain insurance quotes or pro forma estimates for each asset, taking into account flood zone designation, construction type, age, and mitigation measures. They should also consider the potential for future premium increases or changes in coverage terms as insurance markets respond to evolving risk profiles.
Section 14Landlord Tenant and Regulatory Environment
The landlord tenant and regulatory environment in Tennessee shapes the rights and obligations of owners and renters. Tennessee law governs residential leases, security deposits, habitability standards, notice requirements, and eviction procedures. While this review does not reproduce statutory text, Tennessee is generally regarded as having a relatively balanced or landlord friendly framework compared with some coastal jurisdictions that impose more extensive rent regulation and eviction protections.
Local governments in Tennessee exercise zoning and land use authority, adopt building codes, and may implement ordinances that affect property operations. However, the state does not have a broad statewide rent control regime. Properties that participate in federal or state affordable housing programs, such as those supported by low income housing tax credits that the Tennessee Housing Development Agency administers, are subject to regulatory agreements that restrict rents, tenant incomes, and property use over specified compliance periods.
For investors, the regulatory environment in Tennessee generally allows predictable lease enforcement and flexibility in setting rents in market rate properties, subject to fair housing laws and contractual obligations. It also offers programmatic opportunities in the affordable housing space, which bring additional compliance requirements but can provide stable income streams and support from state and federal programs.
Section 15Infrastructure
Infrastructure in Tennessee underpins both economic activity and real estate performance. The state central geographic position in the eastern United States is reinforced by major interstate highways and freight rail corridors that support manufacturing and logistics clusters. Airports in Nashville, Memphis, Knoxville, and Chattanooga provide passenger and cargo connectivity that benefits a range of industries.
Publicly accessible datasets in this environment do not provide numeric figures for Tennessee infrastructure spending, vehicle miles traveled, transit ridership, or broadband penetration. However, the size of the trade, transportation, and utilities sector, which employed 683.8 thousand people statewide in June 2026, highlights the importance of transportation and utility infrastructure to the state economy. Construction employment of 166.7 thousand jobs further suggests ongoing investment in buildings and infrastructure.
For real estate investors, infrastructure considerations include proximity to highways, rail hubs, and airports for industrial and logistics assets, accessibility and parking for retail properties, and road and transit connectivity for multifamily and office properties. Planned infrastructure investments, such as highway expansions or transit improvements, can enhance submarket prospects, while infrastructure deficits can constrain growth or increase operating costs.
Section 16Climate and Physical Risks
Tennessee climate and physical risk profile reflects its inland location, varied topography, and exposure to severe weather. Federal Emergency Management Agency guidance emphasizes that floods occur naturally and can happen almost anywhere, including away from visible bodies of water, and that any area with at least a one percent annual chance of flooding is considered high risk, with at least a one in four chance of flooding during a typical mortgage term. Tennessee river valleys, low lying areas, and urban neighborhoods with limited drainage infrastructure can experience riverine and flash flooding during heavy rain events.
The National Centers for Environmental Information note that the United States experiences frequent severe weather events. Tennessee lies in a region where severe thunderstorms, heavy rainfall, hail, and tornadoes are common hazards. While the state does not face ocean storm surge, remnants of tropical systems can bring intense rainfall and wind, contributing to flooding and wind damage. Winter storms are less severe than in more northern states but can still affect infrastructure and operations in parts of Tennessee.
These risks influence insurance costs, capital expenditure needs, and long term asset resilience. Properties located in or near Federal Emergency Management Agency mapped high risk flood zones may face mandatory flood insurance requirements and higher premiums. Buildings constructed to more recent codes, with improved structural systems, roof assemblies, and drainage, may be better positioned to withstand severe weather. Investors should incorporate climate and physical risk assessments into site selection, due diligence, and long term capital planning.
Section 17Opportunities
Within this statewide context, several opportunity themes emerge for Tennessee real estate investors.
First, workforce and middle income multifamily housing in and around major employment centers appears well supported by the labor market. Statewide employment in education and health services reached 516.3 thousand jobs in June 2026, and leisure and hospitality employment reached 374.4 thousand jobs, both sectors with positive twelve month growth. Combined with stable professional and business services employment, this points to durable demand for rental housing among workers across income levels, particularly in and near metros such as Nashville, Memphis, Knoxville, and Chattanooga.
Second, single family rental strategies can benefit from Tennessee price and inventory dynamics. With a statewide median sale price of 383,637 dollars, 1.0 percent annual price growth, and an 8.9 percent increase in homes for sale in May 2026, investors have access to a growing pool of potential acquisitions without extreme bidding pressure, as reflected in the 14.1 percent share of homes selling above list price. Well located single family rentals near job centers and quality schools can offer attractive risk adjusted returns if acquisition prices and operating costs are disciplined.
Third, industrial and logistics assets aligned with Tennessee 356.3 thousand manufacturing jobs and 683.8 thousand trade, transportation, and utilities jobs present compelling opportunities. Modern warehouses and distribution centers near major interstates and freight hubs can capture demand from regional and national supply chains, ecommerce, and manufacturing logistics. The state central location makes it a natural candidate for multi market distribution strategies.
Fourth, necessity based retail and grocery anchored centers in established neighborhoods, supported by the large trade and services employment base, can provide stable cash flows, especially when tenanted by essential service providers and complemented by local convenience offerings. These assets can be less sensitive to economic cycles than discretionary retail centered on luxury or purely experiential offerings.
Section 18Risks
Balanced against these opportunities are several key risks that investors must weigh.
One risk is the information gap on core demographic and housing variables. The inability to access Census Bureau population, income, and housing tables for Tennessee, and the absence of public statewide multifamily rent, vacancy, and cap rate series, make it more challenging to benchmark performance and to calibrate expectations. Without those data, investors risk overestimating demand or underestimating competition in particular submarkets if they rely solely on high level narratives.
A second risk is sector specific exposure. While statewide employment is diversified, certain sectors show weakness. Financial activities employment declined 1.6 percent over the year to June 2026, and trade, transportation, and utilities employment declined 0.5 percent, suggesting headwinds in some parts of the service and logistics economy. Office assets heavily dependent on shrinking or restructuring sectors may face elevated vacancy and downward pressure on rents.
Third, climate and insurance risks may be increasing. Although this review cannot quantify statewide insurance premium trends, the combination of flood exposure in riverine and low lying areas and frequent severe weather events can drive higher insurance costs, potential coverage limitations, and greater volatility in operating expenses. Older assets or those not hardened against severe weather may require significant capital expenditures over time to remain insurable and competitive.
Fourth, capital markets conditions represented by higher interest rates and more conservative underwriting standards can impair leverage, reduce returns, and increase the cost of capital, particularly for transitional or speculative projects. In a moderate growth state like Tennessee, aggressive capital structures that assume rapid rent growth or major cap rate compression may be vulnerable if those assumptions do not materialize.
Section 19Investor Implications
For accredited investors, Tennessee offers a combination of moderate growth, relative affordability, and sectoral diversity that can contribute to a balanced real estate portfolio. The statewide unemployment rate around 3.5 percent in the first half of 2026, a total nonfarm employment base of 3,385.3 thousand jobs in June 2026, and positive growth in education and health services and leisure and hospitality all support ongoing demand for housing and commercial space. Statewide housing metrics show a market with rising inventory, modest price appreciation, and limited bidding pressure compared with the national average.
These conditions favor investment strategies that emphasize stable income and careful asset selection over speculative appreciation. Multifamily and single family rental assets that target workforce and middle income tenants in growing metros and corridors can benefit from the employment base and housing affordability profile. Industrial and logistics properties aligned with manufacturing and trade corridors can provide resilient cash flows tied to essential economic functions.
At the same time, investors must navigate information gaps, climate and insurance risks, and uneven sector performance. Underwriting should incorporate conservative rent and occupancy assumptions, explicit sensitivity analyses for insurance and tax expenses, and realistic exit cap rate scenarios. Local partnerships, data from private providers, and detailed submarket research become especially valuable given the limitations of publicly accessible data in this document.
Section 20Conclusion
Tennessee statewide real estate landscape, viewed through the lens of available public data as of mid 2026, is characterized by a large and relatively stable labor market, modest but positive job growth, and a housing market that is more balanced and less overheated than the national average. Statewide employment in manufacturing, logistics, health care, professional services, and tourism creates a diversified base of demand for residential and commercial property. Redfin housing statistics indicate that Tennessee home prices are slightly below national medians, price growth is moderate, inventory is expanding, and bidding intensity is lower than in many other parts of the country.
The absence of accessible Census population and income tables, statewide rent and vacancy series, and public transaction and cap rate data means that this review cannot provide a fully quantified picture of all dimensions of the market. Nonetheless, the labor, housing price, and program level housing finance data that are available support a narrative of steady, sustainable conditions rather than bubble like excess.
For accredited investors, Tennessee should be considered as a market where disciplined, data informed strategies focused on multifamily, single family rental, and industrial and logistics assets can play a constructive role in a diversified portfolio. Success in this market will depend on asset level and submarket level insights, conservative capital structures, and proactive management of operational and physical risks rather than on broad macro bets.
Sources
- U.S. Bureau of Labor Statistics, Tennessee Economy at a Glance ,, https://www.bls.gov/eag/eag.tn.htm
- U.S. Bureau of Labor Statistics, Current Employment Statistics State and Area ,, https://www.bls.gov/sae
- U.S. Bureau of Labor Statistics, Local Area Unemployment Statistics ,, https://www.bls.gov/lau
- U.S. Census Bureau, State Population Totals and Components of Change: 2020 to 2025, NST EST2025 ALLDATA.csv, Tennessee row not visible in truncated extract ,, https://www2.census.gov/programs-surveys/popest/datasets/2020-2025/state/totals/NST-EST2025-ALLDATA.csv
- U.S. Census Bureau, QuickFacts Tennessee, access attempted, blocked by Cloudflare in this environment ,, https://www.census.gov/quickfacts/TN
- Redfin, Tennessee Housing Market: House Prices and Trends ,, https://www.redfin.com/state/Tennessee/housing-market
- Redfin, United States Housing Market and Prices ,, https://www.redfin.com/us-housing-market
- Tennessee Housing Development Agency, Tennessee Housing Development Agency home page ,, https://thda.org
- Tennessee Department of Revenue, Department of Revenue home page ,, https://www.tn.gov/revenue
- Tennessee Department of Commerce and Insurance, Tennessee Insurance Division ,, https://www.tn.gov/commerce/insurance-division.html
- U.S. Department of Housing and Urban Development, FY 2024 Fair Market Rents Documentation System, Select Geography interface ,, https://www.huduser.gov/portal/datasets/fmr/fmrs/FY2024_code/select_Geography.odn
- Federal Emergency Management Agency, Flood Maps ,, https://www.fema.gov/flood-maps
- National Centers for Environmental Information, National Centers for Environmental Information home page ,, https://www.ncei.noaa.gov